


<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/cost-of-living-in-casablanca#article","headline":"What is the cost of living in Casablanca?","description":"Discover the cost of living in Casablanca, from rent in CFC and Ain Diab to utilities, food prices, and expat living expenses.","inLanguage":"en","url":"https://grey.co/blog/cost-of-living-in-casablanca","mainEntityOfPage":{"@id":"https://grey.co/blog/cost-of-living-in-casablanca#webpage"},"datePublished":"2025-10-31T21:47:50.797Z","dateModified":"2026-06-15T16:57:29.121Z","author":{"@type":"Person","@id":"https://grey.co/authors/priscila-marotti#person","name":"Priscila Marotti","url":"https://grey.co/authors/priscila-marotti","jobTitle":"Content Writer","sameAs":["https://www.linkedin.com/in/priscila-marotti/"]},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/cost-of-living-in-casablanca#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a300e08ab3c2cc771e695b6_6a300e08ab3c2cc771e694a1_cost-of-living-in-casablanca__header-image.webp","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a300e08ab3c2cc771e695b6_6a300e08ab3c2cc771e694a1_cost-of-living-in-casablanca__header-image.webp","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/cost-of-living-in-casablanca#webpage","url":"https://grey.co/blog/cost-of-living-in-casablanca","name":"What is the cost of living in Casablanca?","description":"Discover the cost of living in Casablanca, from rent in CFC and Ain Diab to utilities, food prices, and expat living expenses.","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/cost-of-living-in-casablanca#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/cost-of-living-in-casablanca#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/cost-of-living-in-casablanca#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"What is the cost of living in Casablanca?","item":"https://grey.co/blog/cost-of-living-in-casablanca"}]}] </script>

What is the cost of living in Casablanca?

Priscila Marotti

TABLE OF CONTENT

SHARE THIS POST

Casablanca might not have Marrakech’s desert charm or Chefchaouen’s blue alleys, but it’s Morocco’s beating economic heart. It’s a modern, fast-paced coastal city where global companies meet French cafés, street markets, and the Atlantic breeze.

Living here feels a bit like balancing two worlds: the polished side of Morocco, with its shopping malls, business districts, and seafront restaurants, and the local rhythm of markets, bakeries, and friendly neighbourhood cafés.

So, how much does it actually cost to live comfortably in Casablanca? Here’s a breakdown of rent, utilities, food, transport, and more, with a closer look at what different neighbourhoods offer.

Rent in Casablanca

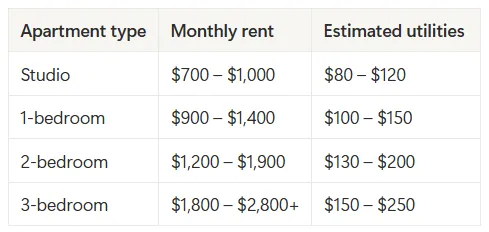
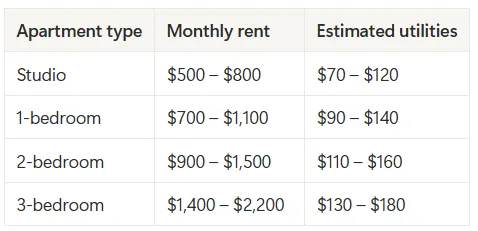
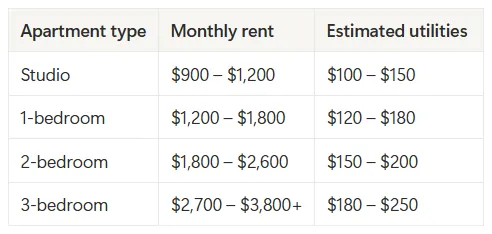
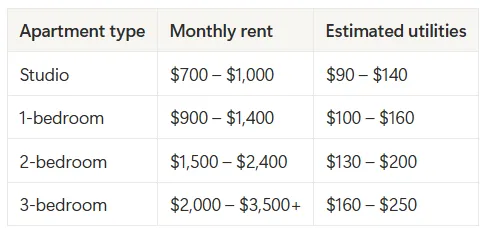
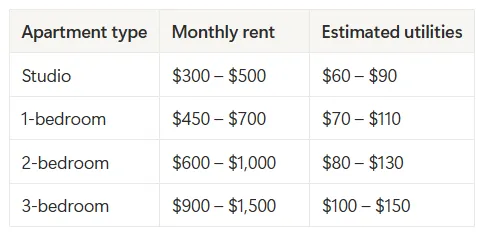
Casablanca has one of the most expensive housing markets in Morocco, but you’ll find a wide range of options, from modern apartments near the Corniche to older but charming flats downtown. Prices vary based on location, building age, and whether utilities are included.

Below are some of the most popular areas for expats and professionals, from luxury seaside spots to more budget-friendly residential zones.

Ain Diab

Ain Diab is Casablanca’s seaside escape, home to beach clubs, ocean-view apartments, and a lively restaurant scene. It’s perfect if you want a more Westernised, coastal lifestyle (and don’t mind paying for it).

__wf_reserved_inherit

Maarif / Gauthier

Maarif and neighbouring Gauthier are central, trendy, and popular among young professionals. You’ll find cafés, coworking spaces, and international restaurants everywhere. Apartments are usually modern and well-located, though parking can be tricky.

__wf_reserved_inherit

Casablanca Finance City (CFC)

CFC is one of the city’s newest and most upscale neighbourhoods, designed as both a business and lifestyle hub. It’s become a hotspot for expats, executives, and returning Moroccans thanks to its sleek apartment buildings, green spaces, and proximity to major companies. Think of it as Casablanca’s modern “Cartier”, being elegant, secure, and well-connected.

__wf_reserved_inherit

Racine / Bourgogne

Close to both the city centre and the sea, Racine and Bourgogne are elegant and convenient. Racine is more upscale, with boutiques and French-style cafés, while Bourgogne is more relaxed but still well-connected.

__wf_reserved_inherit

Anfa / Californie

These are Casablanca’s high-end residential neighbourhoods. They’re quiet, green, and ideal for families or anyone looking for space and privacy. Expect modern villas and gated communities rather than apartments.

__wf_reserved_inherit

Centre-ville (City centre)

Casablanca’s downtown is bustling, walkable, and full of older art deco buildings. Apartments here are more affordable, but often smaller or less modern. Great if you enjoy city energy and proximity to the tram.

__wf_reserved_inherit

Sidi Maarouf

Further from the city centre, these residential areas are quieter and more affordable. Many families and professionals who work in business parks or tech zones live here.

__wf_reserved_inherit

Why prices vary:

Casablanca’s rent depends on your location, building type, and whether the apartment is furnished. Sea views, new constructions, and areas near tram lines or international schools tend to cost significantly more.

Transport in Casablanca

Casablanca is Morocco’s busiest city, so getting around is part of everyday life. Between the tram lines, taxis, and ride-hailing apps, moving through the city is relatively easy, though traffic during rush hour can test anyone’s patience.

Expats and locals usually mix different transport modes depending on distance, time of day, and comfort.

Taxis (Petit & Grand)

Like in other Moroccan cities, Casablanca has two main types of taxis. Petit Taxis (usually red) handle trips within city limits, while Grand Taxis are larger vehicles that serve longer routes or nearby towns like Mohammedia or Rabat.

  • Cost: Petit Taxi starts at around 8.5 MAD (~$0.70) during the day, with typical short rides costing 15–35 MAD ($1.50–$3.50). Grand Taxis usually start around 40 MAD ($4) for longer distances and can go up to 150 MAD ($15) for intercity trips.
  • Tip: Always ask the petit taxi driver to turn on the meter (compteur). If they refuse, agree on a price before the ride starts, especially at night or in tourist areas. White taxis have their own pricing depending on the destination.

Ride-hailing apps (Heetch, Yango)

Casablanca is one of the best cities in Morocco for ride-hailing apps. Services like Heetch and Yango are popular among expats who prefer cashless payments and predictable fares.

  • Cost: 20–50 MAD ($2–$5) for short rides; slightly higher during peak hours.
  • Tip: App drivers usually know English or French, and prices are displayed upfront, so no haggling needed.

Tramway

Casablanca’s modern tram network is one of the most efficient public transport systems in Africa. It connects key neighbourhoods like Sidi Maarouf, Ain Diab, and the city centre, with two main lines covering over 40 km.

  • Cost: 8 MAD (~$0.60) per ticket or 230 MAD ($23) for a monthly pass.
  • Tip: Trams are reliable and clean, but can get crowded during rush hours (especially between 7–9am and 5–7pm).

Buses

Public buses cover the entire city, offering the cheapest rides. They’re modernising quickly, with newer fleets and air conditioning, but routes can still be slow and inconsistent in timing.

  • Cost: Around 5 MAD (~$0.50) per ride.
  • Tip: Better for regular commutes than quick trips. Use Google Maps or the ALSA app to check schedules.

Driving and car rentals

Driving in Casablanca gives you flexibility, but you’ll need patience for traffic and parking. Roads are well-maintained, but driving habits can feel chaotic for newcomers.

  • Cost: Car rentals range from 300–500 MAD/day ($30–$50) for a small car. Fuel costs around 14–15 MAD/L ($1.40–$1.50).
  • Tip: Many expats prefer apartments with parking, as street parking can be limited and guarded spots are often paid separately.

Motorbikes and scooters

Scooters are becoming more common, especially among younger locals and delivery drivers. Expats sometimes rent one for short commutes.

  • Cost: Around 120–180 MAD/day ($12–$18).
  • Tip: Always wear a helmet — traffic rules can be loosely followed, especially downtown.

Walking and cycling

Casablanca isn’t as walkable as smaller Moroccan cities, but areas like Maarif, Racine, and Gauthier have wide pavements and safe crossings. The Corniche (Ain Diab) is perfect for walking or cycling by the sea.

  • Cost: Free; bike rentals from 50–80 MAD/day ($5–$8).
  • Tip: Early mornings and evenings are best for walking, especially during summer when temperatures soar.

Quick cost overview:

__wf_reserved_inherit

Food prices in Casablanca

In Casablanca, you’ll find everything from traditional Moroccan eateries tucked between office buildings to sushi bars, French brasseries, and seaside restaurants along the Corniche. For expats, the city offers both affordable local flavours and an expanding international food scene.

Restaurants

Dining out in Casablanca can be a daily indulgence or a weekend treat, depending on your budget. The city’s restaurant scene mirrors its cosmopolitan vibe, with casual snack bars and cafés dominating central neighbourhoods, while fancy lounges and fine-dining spots cluster around Ain Diab, Gauthier, and Racine.

  • Street food / local cafés: Expect to spend 25–60 MAD ($2.50–$6) for Moroccan staples like tagine, pastilla, or grilled sardines. A fresh juice or mint tea adds about 5–10 MAD ($0.50–$1).
  • Mid-range restaurants: In areas like Gauthier, Maarif, or Anfa, a meal with drinks typically costs 100–180 MAD ($10–$18) per person. You’ll find Italian, Lebanese, and Asian restaurants alongside Moroccan favourites.
  • Fine dining / Corniche restaurants: A dinner for two with starters and mains at a high-end restaurant can cost anywhere between 500–900 MAD ($50–$90), excluding wine.

Casablanca also has a buzzing café culture. From stylish French-style cafés on Boulevard d’Anfa to beachside spots in Ain Diab, a coffee and pastry combo costs around 25–50 MAD ($2.50–$5).

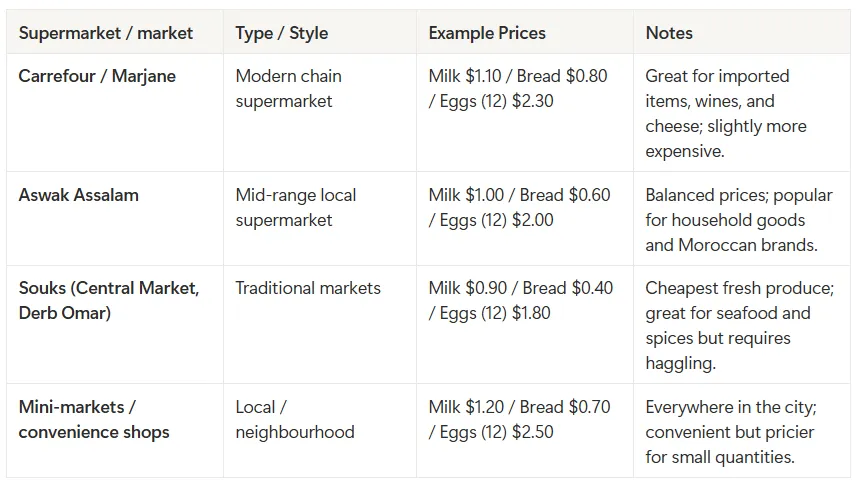
Supermarkets and markets

As Morocco’s largest city, Casablanca has the widest variety of supermarkets, from global chains to traditional souks. Prices vary depending on whether you shop local or imported.

__wf_reserved_inherit

People living in Gauthier, Racine, and Anfa tend to split shopping between Carrefour (for international goods) and neighbourhood markets for produce. Those in less central areas like Hay Hassani or Sidi Maarouf often rely more on Aswak Assalam or local shops.

Utilities costs in Casablanca

Casablanca, as Morocco’s economic capital, has a slightly higher cost of living than other cities, and utilities are no exception. Still, the prices are reasonable compared to major global cities, and expats find them manageable once they settle in.

Electricity

Electricity use varies depending on the season. Coastal breezes keep Casablanca cooler than inland cities like Marrakech, so you’ll spend less on air conditioning, though heating might be needed during the damp winter months.

  • Average monthly cost for a 1–2 bedroom apartment: $35–65
  • Tips: Energy-efficient bulbs and unplugging appliances when not in use can help keep bills low. Electricity is billed monthly by ONEE, Morocco’s national provider.

Water

Water costs are moderate. Casablanca’s water supply is managed by Lydec, and most apartments have reliable access. Some landlords include water in the rent, especially for furnished flats.

  • Average monthly cost: $12–25
  • Tip: Always check whether your rental includes water and sewer fees, as billing can vary.

Gas

Most homes use bottled gas for cooking and hot water, just like in other Moroccan cities. Delivery is quick and easy to arrange through local vendors.

  • Cost: Around $8–15 per month
  • Tip: Keep an extra bonbon de gaz at home, especially during colder months or if you cook frequently.

Internet

Casablanca has Morocco’s best internet infrastructure, with fast fibre-optic connections widely available in neighbourhoods like Maarif, Racine, and Gauthier.

  • Average monthly cost: $25–50 for fibre (~200–500 Mbps)
  • Tip: Maroc Telecom, Inwi, and Orange are the main providers. Installation is usually quick, especially in newer buildings.

Mobile/cell phone

Mobile data plans are affordable and efficient, ideal for both short-term and long-term stays.

  • Average monthly cost: $10–20 for 10–20 GB data
  • Tip: Prepaid SIMs are widely available at airports, malls, and convenience stores. Coverage in Casablanca is excellent across all providers.
__wf_reserved_inherit

Healthcare in Casablanca

As Morocco’s largest and most cosmopolitan city, Casablanca offers some of the country’s best healthcare facilities. Expats will find both public and private options, with the private system being the preferred choice for quality care, shorter wait times, and multilingual staff.

Public healthcare

Public hospitals in Casablanca are suitable for basic care and emergencies but not ideal for specialised or ongoing treatments.

  • Cost: Low or free for residents; small fees for consultations or prescriptions
  • Pros: Inexpensive and widely available
  • Cons: Long waits, limited English-speaking staff, and varying service quality

Private healthcare and insurance

Casablanca’s private healthcare sector is modern, reliable, and significantly more affordable than in Europe or North America. The city is home to several excellent hospitals and clinics, such as Clinique Littorale, Clinique Jerrada, and Clinique Yasmine, which cater to both locals and foreigners.

  • Basic consultation (without insurance): $25–50
  • Specialist visit: $50–90
  • Hospital stay (per night, private room): $120–250

Private hospitals usually offer bilingual (French-English) services and well-equipped facilities. For peace of mind, most expats opt for private health insurance that covers both outpatient and inpatient care.

__wf_reserved_inherit

Many expats pay cash for smaller visits since local consultation fees are quite affordable. Pharmacies are abundant throughout Casablanca, especially in central districts like Maarif and Gauthier, and most medications are available without a prescription.

Average living costs in Casablanca

Casablanca is more expensive than most Moroccan cities, but still far cheaper than major Western capitals. Your living costs will depend largely on your neighbourhood and lifestyle choices.

__wf_reserved_inherit

You can live comfortably in Casablanca on around $1,800–2,000 per month, though costs rise significantly if you prefer a central neighbourhood or dine out often.

Earning abroad, living well in Casablanca

Casablanca blends Morocco’s coastal charm with a fast-paced urban rhythm — where business meets culture and the Atlantic breeze meets city lights.

With Grey, you can receive international payments in USD, GBP, or EUR, exchange when the rates are best, and withdraw MAD directly to a Moroccan bank account. Seamless, transparent, and made for people who live globally but spend locally.

Open your Grey account today and focus on growing your life in Casablanca and not worrying about cross-border transfers.

‍

Last updated:

October 8, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

How to receive YouTube earnings in Nigeria

•

•

2 min read

If you’re a Nigerian YouTuber close to monetisation, first congratulations. You’ve earned it, or at least you’re about to. Now it’s important to understand how YouTube will pay you and how to properly set up your payment details, so you don’t lose out on your funds.

In this article, I will share exactly how YouTube pays creators, and what Nigerian creators need to do to maximise earnings.

How YouTube actually pays creators

YouTube doesn’t pay you directly. Instead, they pay through Google AdSense, which is Google’s advertising platform. When you’re accepted into the YouTube Partner Programme, you link your YouTube channel to an AdSense account, and that’s where your earnings accumulate.

AdSense pays in US dollars (USD). There’s a minimum payout threshold of $100, meaning you won’t receive anything until your earnings reach at least $100. Once you cross that threshold, AdSense processes payments monthly, typically between the 21st and 26th, for the previous month’s earnings.

So if you earn $150 in January, AdSense will pay you sometime between 21st and 26th February. Simple enough in theory, but where does that money actually go, and how do you access it in Nigeria?

Also read: How Indian YouTube creators receive their earnings from overseas

What do Nigerian creators need to be eligible?

To receive YouTube earnings in Nigeria, you need a few things in place:

A monetised YouTube channel: This means you’ve been accepted into the YouTube Partner Programme (1,000 subscribers, 4,000 watch hours in the past 12 months, and adherence to YouTube’s policies).

A Google AdSense account: You’ll create this when applying for monetisation. Make sure your AdSense account has your correct legal name and address.

A valid payment method: This is where it gets tricky for Nigerian creators. AdSense needs a way to send you money, and not every method works smoothly in Nigeria. I’ll discuss this in-depth later.

Tax information: AdSense requires you to submit tax details, even if you’re not in the US. Nigerian creators typically complete a W-8BEN form, which confirms that you’re a foreign person not subject to US tax withholding on most AdSense earnings.

Also read: How South Africans can receive YouTube payments from abroad

The problems Nigerian creators run into with receiving YouTube earnings

The first time I set up an AdSense payout, I added a Nigerian bank account and assumed everything would work smoothly. It didn’t.

First problem, delays. My first payment took nearly two weeks to arrive after AdSense marked it as sent. I had no visibility into where the money was or why it was taking so long.

The second problem was the fees and exchange rates. When the money finally arrived, I lost around 5 - 6% due to a combination of receiving fees and a terrible exchange rate set by my bank. On a $200 payout, that’s $10 - $12 gone, money I’d worked hard to earn.

I realised quickly that relying solely on wire transfers to a Nigerian bank wasn’t sustainable. I needed a better system.

Also read: How Ghanaian YouTubers can collect USD earnings

LDMAG1

How to receive YouTube payouts properly

After some research and talking to other Nigerian creators, I eventually figured out what actually works. The key is using a service that provides a US bank account or a more efficient way to receive USD payments than traditional Nigerian banks.

Here’s what I did:

Step 1: I opened an account on a platform that provides virtual USD accounts. Most people recommended Grey, and I obliged. Platforms like this give you US banking details (account number and routing number) that you can add to AdSense as your payout method. When AdSense sends payments, they go to this account instead of directly to a Nigerian bank.

Step 2: I updated my AdSense payment settings. In AdSense, under Payments > Payment methods, I added my new US bank details. AdSense verified the account by making small test deposits, which I confirmed.

Step 3: I waited for my next payout cycle. Once my earnings crossed $100 again, AdSense sent the payment to my US account. It arrived within 3 - 5 days, much faster than wire transfers to Nigerian banks.

Step 4: Instead of being forced to convert USD to naira immediately at whatever rate my bank decided, I held the money in USD and converted it when rates were favourable. I also had the option to spend directly from a USD card or withdraw to my Nigerian bank account.

This setup solved every problem I’d been facing: faster payments, better control over exchange rates, and no rejected transfers.

Also read: Valentine’s Day trips that work for remote couples

Tips I’d give a Nigerian YouTuber

Set up your payment method before you hit $100: Don’t wait until you’ve earned your first payout to sort this out. Get your USD account ready early so there are no delays when you finally qualify for payment.

Don’t rely on traditional wire transfers unless you have no other option: The fees and delays aren’t worth it. Get a free USD account with Grey, Wise to gain better control and faster access to your money.

Keep your AdSense details accurate: Make sure your name, address, and tax information match your official documents. Mismatches can delay payments or cause verification issues.

Track your earnings and fees: Know how much you’re actually receiving after conversion and fees. This helps you plan better and understand the real value of your content.

Focus on creating consistent content: The payment setup is important, but your primary job is still making videos people want to watch. Sort out the money side once, then get back to creating.

Create more, stress less

Once you’ve sorted out a reliable payment method, you can focus on making great videos and growing your audience.

Set up your USD receiving account now, link it to AdSense, and get back to creating. Your content deserves to be rewarded properly, and you deserve to receive that money without unnecessary stress.

Open your free Grey account today, or download the app, and start receiving your YouTube earnings faster, at better rates, and with full control over your money. Because you’ve earned it, you should actually get to keep it.


‍

Online work platforms growing fastest in 2026

•

•

2 min read

As a freelancer, understanding which platforms are growing fastest tells you where opportunity is concentrating. It reveals which business models are working, which professional categories are in demand, and where geographic expansion is creating new markets for remote workers. Growth doesn’t automatically mean “best,” but it absolutely signals where attention, investment, and users are flowing.

In this article, I identify the platforms experiencing significant growth in 2026, explain why they’re expanding, and explore what it means for freelancers and remote workers navigating an increasingly fragmented marketplace.

First, what do I mean by growth?

Growth isn’t one-dimensional. A platform can be growing rapidly in user acquisition but struggling with revenue. Another might have modest user growth but explosive increases in transaction volume. When evaluating platform growth, several metrics matter.

User acquisition rates indicate that platforms are adding workers and clients quickly, particularly in previously underserved markets. Revenue growth indicates transaction volume and platform fees are increasing significantly. Geographic expansion reveals platforms successfully entering new countries and regions where they previously had minimal presence. Feature adoption demonstrates that new tools or services are scaling quickly within existing user bases. Market share shifts show platforms taking users from established competitors.

These dimensions don’t always move together. A platform might be growing users rapidly in Southeast Asia, whilst mature markets stagnate. Another might have steady user counts but rapidly increasing revenue per user as they roll out premium features. Understanding these nuances matters when deciding where to invest your time building profiles and reputations.

Why platform growth patterns matter for workers

Growing platforms create opportunity, but they also introduce complexity. When a platform is scaling quickly, job opportunities typically expand as the client base grows. Platform revenue funds feature development, improving tools and user experience. Payment infrastructure often improves to support scaling across geographies. Competition between platforms benefits users by lowering fees and improving terms.

But rapid growth isn’t universally positive. Quality control sometimes suffers when platforms prioritise expansion over moderation. Policies change frequently as companies figure out what works at scale. Early adopter advantages diminish as competition increases. Payment and support systems occasionally struggle to keep pace with user growth.

Understanding growth helps you identify emerging opportunities before markets saturate, diversify strategically across platforms, anticipate which skills will be in demand, and position yourself where opportunity is expanding rather than contracting.

Commission-free and alternative model platforms

Contra has positioned itself as the anti-Upwork, and it's working. The platform doesn't charge freelancers commissions, instead monetising through premium features. This model has resonated particularly with mid-career to senior freelancers tired of paying 10–20% platform fees on every project.

Contra's growth is concentrated among designers, developers, marketers, and other creative professionals who want portfolio-focused presentation rather than bid-based competition. The platform emphasises direct client relationships without heavy platform intermediation. User acquisition has expanded from primarily US-based freelancers to a genuinely global base, and transaction volume is rising despite the commission-free structure.

What's driving this growth is straightforward: experienced freelancers do the maths and realise they're losing thousands annually to platform fees. Contra's sleek portfolio system appeals to creatives who want their work showcased well. The younger demographic comfortable with newer platforms is willing to experiment beyond established marketplaces.

One implication: commission-free platforms mean freelancers handle their own payment infrastructure. You're not routing money through the platform's payment system, but invoicing clients directly and managing how you receive funds. This creates both flexibility and responsibility around choosing payment methods that work internationally.

Braintrust takes a different approach: user ownership via a token-based governance model. Originally focused on blockchain and crypto projects, it's expanded into mainstream enterprise clients seeking vetted developers. The platform's growth is driven by its ownership structure — users who contribute (by working, referring clients, or participating in governance) earn tokens that give them stake in the platform's success.

For senior developers and tech professionals interested in Web3 models, Braintrust offers both competitive rates (by eliminating traditional platform overhead) and philosophical alignment with decentralised ownership. Growth has been strong in developer communities, particularly those already familiar with crypto ecosystems.

Vertical-specific platforms dominating niches

Toptal isn't new, but it continues growing by slowly expanding which specialisations it accepts. Started exclusively for developers, it now includes designers, finance experts, product managers, and recently added interim executives. This controlled expansion lets Toptal maintain its exclusivity whilst accessing new markets.

Growth indicators include geographic reach into emerging tech hubs and enterprise client acquisition. Companies willing to pay premium rates for vetted talent have proven to be a sustainable market, and remote work normalisation has made global hiring standard practice rather than experimental.

For workers, Toptal's continued growth signals that the premium talent segment remains strong. If you're senior in your field and can pass their vetting (which remains genuinely difficult as acceptance rates stay around 3%), the platform offers high-quality, well-paying projects.

Maven has grown rapidly in the cohort-based course and expert knowledge space. Post-pandemic, there's been an explosion in practitioners monetising their expertise through teaching. Maven makes it technically simple to run cohort-based courses — live sessions, community interaction, structured curriculums — without building your own platform infrastructure.

Course creator numbers are rising fast, particularly among industry practitioners rather than traditional educators. A senior product manager at a tech company can run a cohort on product strategy. An experienced designer can teach a workshop on design systems. Growth is driven by low barriers to entry, high profit margins on courses, and enough success stories to prove the model works.

For workers with specialised knowledge, Maven and similar platforms represent income diversification beyond client services.

LDMAG1

Geographic expansion into emerging markets

Upwork and Fiverr aren't growing fastest in the US or Western Europe but they're growing in Africa, Southeast Asia, and Latin America. As internet penetration improves and digital payment infrastructure develops in these regions, platforms are expanding their user bases significantly.

This creates more competition for existing workers in these regions but also expands opportunities for clients seeking talent in these markets. Importantly, platform features are increasingly adapted for emerging market needs: local payment methods, better currency support, mobile-first interfaces.

Andela started focused on African tech talent but has expanded into Latin America. It connects developers with global companies whilst providing training and community support. Growth has accelerated as companies seek talent beyond traditional tech hubs and as developers in emerging markets gain access to tools and training that improve their competitiveness.

Turing uses AI-powered matching to connect developers — initially focused on India, now global — with long-term remote roles at companies primarily in the US. It's grown by handling employment logistics, compliance, and payments, making it easier for companies to hire internationally and for developers to access stable income.

The challenge with rapid geographic expansion: payment infrastructure often lags. A platform might operate in 50 countries but only offer reliable, affordable payouts in 15. Workers in newly served markets frequently face limited withdrawal options, forced currency conversions at poor rates, or long delays in accessing earnings.

This is where external payment solutions become essential. If you're working on a platform that's expanding into your region but hasn't yet optimised payment infrastructure, you need your own system for receiving and managing international income efficiently.

Creator economy and content platforms

Substack continues expanding as writers monetise directly without traditional publishing infrastructure. Many top writers continue to earn  through paid subscriptions. The platform has moved beyond newsletters into podcasts and video, and its international writer base is growing steadily.

Growth is driven by writers leaving traditional media, audiences willing to pay for quality content directly, and a subscription model that’s proven sustainable. Substack takes 10% of subscription revenue, which writers find reasonable compared to traditional publishing economics.

Patreon has matured into a reliable income source across creative categories — visual artists, musicians, podcasters, video creators, and even writers. The recurring revenue model works, and the platform keeps improving tools for community management and tiered memberships.

Growth indicators include the creator count increasing in non-US markets and the average revenue per creator rising, suggesting creators are getting better at converting audiences to paying members. International payment infrastructure improvements have made it easier for creators globally to receive funds and for supporters worldwide to subscribe.

Kajabi, Teachable, and Thinkific are course platforms where anyone with expertise can create and sell courses. These three are growing as more practitioners realise they can monetise knowledge. Course creator counts are rising, particularly among people who aren’t professional educators but have industry experience worth teaching.

Their growth is fuelled by low barriers to entry (you don’t need technical skills to set up a course), high profit margins on digital products, and enough success stories to make it feel achievable. For workers, this represents another income diversification option: package your expertise into courses that generate revenue whilst you’re doing other work.

The payment infrastructure challenge

A pattern emerges across fast-growing platforms: they expand geographically and add users faster than they can optimally support payment infrastructure. A platform might accept workers from 60 countries but only offer reliable, affordable payouts in 20 of them.

This creates friction. You’re earning in USD from US clients via one platform, EUR from European clients via another, and GBP from UK clients directly. One platform pays via PayPal, another via bank transfer, and a third via Payoneer. Each method has different fees, timelines, and exchange rate markups.

Workers on growing platforms often face forced conversion to local currency at unfavourable rates, inconsistent payout methods across platforms they use, payment delays as platforms scale transaction processing, and geographic limitations where the platform accepts your work but doesn’t support payouts in your country yet.

How do workers adapt?

  • By building a personal payment infrastructure that works across multiple platforms.
  • Using services like Grey, Wise, or Payoneer to receive payments in multiple currencies.
  • Maintaining accounts that give control over when and how currency conversion happens.

Platforms that solve payment infrastructure well grow faster because they retain workers better, while those that neglect it face churn as workers get frustrated trying to access their earnings efficiently.

This is where Grey fits naturally into remote workers’ infrastructure. Grey provides multicurrency accounts, transparent conversion rates, and control over when you move money, regardless of which platforms you’re working on.

What platform growth means for workers

The platforms growing fastest in 2026 aren’t necessarily the biggest, they're the ones solving problems traditional platforms haven’t addressed. User ownership structures, vertical specialisation, and successful emerging market expansion define where growth is happening.

For workers, several implications stand out. Specialisation is winning: vertical-specific platforms are growing faster than generalist ones in many cases. Geographic barriers are dissolving: platforms succeeding in emerging markets create opportunities for workers in those regions and for clients seeking global talent. Direct relationships are valued: experienced professionals are moving toward platforms that enable less intermediation and more control.

Being early to growing platforms often provides advantages, better visibility, less competition, and sometimes preferential treatment. But don’t abandon established platforms entirely. Growth doesn’t mean existing platforms are dying. Diversification across mature and growing platforms balances stability with opportunity.

Most importantly, invest in your payment infrastructure. As you work across more platforms and geographies, having solid payment systems becomes essential, not optional. The fragmented nature of online work in 2026, which involves multiple platforms, multiple currencies,and  multiple client locations, demands infrastructure that works across all of it.

Grey answers all of that. You can receive international payments in USD, EUR, and GBP, hold multiple currencies, and convert at transparent rates, regardless of which platforms you use. Open your free account today and build payment systems that keep pace with how you actually work.

‍

The best long-stay destinations for remote workers

•

•

2 min read

Choosing a long-stay destination is really different from short visits. If you just need to go out and touch grass or escape from work briefly, you might not have to plan too much. But if you are going to be staying for months, you need to think beyond waking up on a beach or watching the sunset hitting the horizon. A lot more factors come into play with long-stay destinations, and if you don’t carefully pick your destination, you might get frustrated and have to leave sooner than planned

This guide covers some of the best places for remote workers to stay long-term. Before we get into the list, let’s look at what you should think about when picking your next spot.

Also read: Best countries to move to on a digital nomad visa in 2026

What should you consider before choosing a long-stay destination?

Travelling as a remote worker is different from a regular vacation. You need to balance work and fun, so it’s important to think about what will help you stay productive and comfortable during your stay.

  • Internet: Fast, reliable internet is a must for remote workers. It helps you stay connected with your team, work smoothly, and join meetings without issues.
  • Legal requirements: Make sure to check visa rules, taxes, and travel insurance before you go.
  • Cost of living: Look up the average prices for housing, food, and transport to be sure you can afford to live there on your budget.
  • Infrastructure: Check if there are coworking spaces, cafes, good public transport, and other things that will help you work comfortably.
  • Safety: Choose safe neighbourhoods that are close to good medical care. It’s also smart to check your country’s travel advice before you go**.**
  • Lifestyle: Think about the weather, time zone differences with your job, fun things to do, and whether there’s a community for networking.
  • Accommodation: Try to find places with a kitchen to save money on food and enough space for a good work setup.

Also read: How global workers plan income, location, and lifestyle together

The best long-stay destinations for remote workers

With all these factors in mind, here are some of the top long-stay destinations for remote workers.

Lisbon, Portugal

Lisbon has long been a favorite in Europe for long-term stays. The D8 visa lets you stay for up to two years, and the city offers rich culture and a lower cost of living than many other European cities. You’ll find fast fiber internet (100+ Mbps) and coworking spaces like Second Home and Lisbon WorkHub. With a Schengen visa, it’s easy to visit other European countries too. Lisbon is a great choice if you want a European base that’s affordable.

Here’s what the average budget of a digital nomad living in Lisbon looks like.

Valencia, Spain

If you want a city with a Mediterranean vibe and strong digital infrastructure, Valencia is a great pick. Earning about $3,500 per month lets you apply for Spain’s Digital Nomad Visa. You can live well for under $1,500 a month, or up to $2,000 if you want more comfort. Valencia has fast fiber internet (often 100+ Mbps) and plenty of coworking spaces like Vortex Centro and ExpressHub. There’s lots to do, from exploring modern architecture to enjoying the historic sites and relaxing by the coast.

Marrakech, Morocco

Morocco is a crossroads between the Arab world, Africa, and Europe, making Marrakech a unique place for remote workers. The city’s cultural mix is welcoming, and it’s easy to meet people from different backgrounds. While Morocco doesn’t have a specific digital nomad visa, visitors are generally welcomed. The city has strong digital infrastructure and coworking spaces like L’BLASSA, Targa, and Goworking. You can live comfortably in Marrakech on $1,200 to $2,000 per month, and find accommodation in the medina for as little as $400 a month.

Also read: Remote-work friendly cities in Morocco: Rabat, Casablanca or Marrakech?

Chiang Mai, Thailand

Many Southeast Asian cities stand out to remote workers for their affordable living costs, warm residents, and peaceful natural environments. Chiang Mai's the OG nomad hub in Southeast Asia, and with Thailand's DTV visa now valid for 5 years for remote workers, it's even better for long stays. The Internet's solid at 200+ Mbps in coworking cafes like Punspace, and you can live well on $1,000-1,500 monthly. Temples, night markets, and mountain hikes keep things exciting, plus a huge expat scene for meetups. It's great for budget-conscious folks who want culture without chaos.

LDMAG1

Mexico City, Mexico

If you want a lively city, Mexico City is a great choice. The temporary resident visa lets many people stay for up to four years if they can show an income of about $2,600 per month. The city has reliable internet and growing coworking spaces. You can get by on $1,000 to $1,600 a month. Enjoy the tacos, museums, and nice weather. It can get busy at times, but there’s always something to do.

Managing your finances on the go

If you want an easy way to manage your money while traveling, try using multicurrency accounts. Grey lets you hold USD, GBP, or EUR, switch between them easily, and make low-fee transfers. You can also withdraw in local currencies at fair rates and use a USD debit card for online payments wherever you are.

Get started on Grey today and download the app to seamlessly manage your finances on the go.

‍

Countries attracting remote workers the most in 2026

•

•

2 min read

The digital nomad scene has evolved over the years, and 2026 feels like the year of maturity. Today, entire countries are rolling out red carpets for remote workers, and honestly, some of these programmes are incredible.

What’s in it for these countries? A remote worker earning a London or San Francisco salary but spending it in Lisbon or Mexico City. That's pure economic gold, as that’s money that will be pumped directly into the economy through the said freelancers’ spending.

I’ve spent some time researching which countries are genuinely attracting remote workers in 2026, not just talking about it, but actually making it happen. Here’s what I’ve found.

Portugal

Let me start with the obvious one. Portugal has been the poster child for remote work migration since 2020, and in 2026, it remains at the forefront.

Entire neighbourhoods in Príncipe Real and Santos are now essentially expat hubs. You’ll hear more English than Portuguese in some co-working spaces, and the average rent has tripled in five years. Some locals aren’t always thrilled about that, but the government certainly is.

What makes Portugal attractive to remote workers?

The D7 visa (passive income visa) and the newer Digital Nomad Visa make it absurdly easy for remote workers to settle here legally. You need proof of income, which is around €3,040 per month for a single person, and you’re basically in. Processing times are reasonable, and you get access to Europe’s Schengen zone.

Portugal offers a lifestyle that’s hard to beat. It’s affordable, at least compared to London or Paris, has a stunning coastline, incredible food, and a time zone that works for both European and US East Coast clients.

Are there any drawbacks to working remotely in Portugal?

Rent in Lisbon and Porto has become genuinely expensive. A one-bedroom flat in a decent neighbourhood will set you back €1,200 - €1,800 per month now. And if you’re not earning in EUR or USD, the cost of living might surprise you.

Still, for most remote workers, especially those in tech, design, or marketing, Portugal remains one of the safest, easiest, and most attractive options in Europe.

Spain

Some say Spain spent years watching Portugal steal its thunder, but in 2023, it launched a proper Digital Nomad Visa, and by 2026, the results are showing.

I’ve got friends who moved to Valencia and Barcelona in the last year, and the quality of life they describe is impressive. Spain’s visa requires proof of a monthly income of at least € 2,000, a clean criminal record, and health insurance. The visa is valid for 12 months (renewable for up to five years) and you get to live and work remotely in one of Europe’s most liveable countries.

What makes Spain attractive to remote workers?

The weather, obviously. But also the infrastructure. Spain’s internet speeds are excellent, co-working spaces are everywhere, and cities like Madrid, Barcelona, and Valencia offer that perfect mix of metropolitan energy and Mediterranean ease.

Spain's tax regime for new residents can be favourable. The Beckham Law (yes, named after that Beckham) allows qualifying remote workers to pay a flat 24% tax on Spanish-sourced income for up to six years. If you structure things correctly and most of your income is foreign-sourced, Spain can be surprisingly tax-efficient.

Are there any drawbacks to working remotely in Spain?

A minor downside is that obtaining your TIE (residence card) can take several months, and navigating local government offices often requires considerable patience. But if you can navigate the admin, you’ll absolutely love your stay.

Mexico

I’ll be honest, I didn’t expect Mexico to dominate the remote work conversation the way it has, but here we are. In 2026, Mexico City, Playa del Carmen, and Tulum are absolutely crawling with remote workers, particularly from the U.S. and Canada.

Mexico’s Temporary Resident Visa is designed for remote workers who earn at least $3,500 per month or hold at least $60,000 in savings. Once approved, you can live in Mexico for up to four years.

What makes Mexico attractive to remote workers?

The timezone compatibility with the U.S. is a plus if you're working for American clients or companies. Mexico’s Central or Eastern time zones mean you're not taking calls at 2 a.m. The cost of living is significantly lower than in the U.S. You can live comfortably in Mexico City on $2,000–$3,000 per month, including rent, food, and entertainment.

The lifestyle is vibrant. Mexico City boasts world-class restaurants, an incredible cultural scene, and a creative energy that rivals any major global city. The variety is there, and it's affordable.

Are there any drawbacks to working remotely in Mexico?

It’s essential to acknowledge that safety concerns are real in certain areas. Mexico City is generally safe in expat-friendly neighbourhoods like Roma, Condesa, and Polanco, but it’s essential to stay vigilant. Internet reliability can vary significantly, being fine in major cities but patchy in beach towns. And whilst Mexico is affordable, the influx of high-earning remote workers has driven up rents in popular neighbourhoods. A flat in Roma Norte that cost $800 per month in 2021 now costs $ 1,500 or more.

Still, for North American remote workers, Mexico remains the most convenient, accessible, and practical option.

UAE

Dubai and Abu Dhabi have always attracted expats, but the UAE’s remote work visa (launched in 2020 and refined since) has turned it into a genuine hub for high-earning digital professionals.

The UAE’s remote work visa requires proof of a monthly income of $5,000 or more (or an annual income of $50,000 or more), valid employment, and health insurance. The visa grants you one year of residency (renewable), exempts you from income tax, offers world-class infrastructure, and provides a lifestyle that's... well, very Dubai.

What makes Mexico attractive to remote workers?

No income tax is the headline. If you’re earning six figures (a term that I’ve now come to dislike) and paying 40% tax in the UK or EU, moving to Dubai can mean keeping significantly more of your income. The infrastructure is phenomenal and everything runs on time. The UAE is one of the safest countries in the world, and for remote workers with families, that's a huge draw.

Are there any drawbacks to working remotely in Mexico?

It’s expensive. Rent in Dubai is high (think $2,000-$4,000 per month for a decent one-bedroom), and while there's no income tax, the cost of living offsets some of those savings. The culture also isn’t for everyone. There are many strict laws, conservative social norms, and a car-dependent lifestyle that can feel restrictive if you’re used to European walkability.

But for high earners prioritising tax efficiency and luxury, the UAE is hard to beat.

LDMAG1

Estonia

Estonia doesn't get enough credit, but that’s why I’m here. This tiny Baltic nation launched the world's first Digital Nomad Visa in 2020, and whilst it's not as sunny as Portugal or as buzzy as Mexico, it’s carved out its own loyal following.

Estonia's visa requires proof of a monthly income of € 4,500 or more and allows you to live and work remotely for up to 12 months. Extensions are possible, and the entire application process is digital.

What makes Estonia attractive to remote workers?

Everything happens online, from company registration to tax filing. For tech workers and entrepreneurs, Estonia feels like home.

Estonia also offers the e-Residency programme, which allows you to run a business remotely from an EU-based location without needing to reside there. Pair that with the Digital Nomad Visa, and you've got a powerful setup for location-independent entrepreneurs.

Are there any drawbacks to working remotely in Estonia?

It's cold. Proper cold. If you’re chasing sunshine, Estonia isn't it. The expat community is relatively small, which can make it feel isolating. And whilst Tallinn is lovely, the rest of Estonia is quite rural; if you need urban energy, options are limited.

But for a certain type of remote worker, tech-focused, digitally savvy, unbothered by winter, Estonia is brilliant.

Also read: The best countries in Europe to land a remote job

Indonesia

Bali has perhaps been the most popular digital nomad hotspot in Indonesia. For over a decade, it's always existed in a legal grey area. Most people worked on tourist visas and did "visa runs" every few months. In 2024, Indonesia finally launched a proper remote work visa.

The visa costs around $130, requires proof of a monthly income of $2,000 or more, and grants you 12 months (renewable for up to five years) to live and work remotely.

Also read: Real budgeting tips for nomads living in Bali

What makes Indonesia attractive to remote workers?

It’s cheap. You can live well in Bali on $1,500 per month. The lifestyle is unbeatable: surf, yoga, co-working spaces overlooking rice paddies, and a massive community of like-minded remote workers. Canggu, Ubud, and Sanur are now essentially purpose-built for this crowd.

Are there any drawbacks to working remotely in Indonesia?

Infrastructure is hit-or-miss. The internet can be unreliable during the rainy season, power cuts happen, and healthcare isn’t comparable to that in developed countries. The visa process, whilst improved, still involves typical Indonesian bureaucracy.

But if you’re earning in USD or GBP and want a low-cost, high-lifestyle base in Southeast Asia, Bali remains hard to beat.

Also read: Everything you need to know about the Indonesian digital nomad visa

So what country is best for you?

The countries attracting remote workers in 2026 aren’t just the ones with the nicest beaches or the coolest co-working spaces. They’re the ones that understand the economics, make visas accessible, and offer a genuine quality of life improvement over wherever you’re leaving.

Portugal, Spain, Mexico, the UAE, Estonia, and Indonesia are leading the pack, and they’re leading for different reasons. Portugal offers European ease and Schengen access. Spain brings scale and variety. Mexico offers affordability and time zone alignment for Americans. The UAE is the tax-free luxury option. Estonia is the digital pioneer. Bali is the lifestyle escape.

Your ideal destination depends on what you value most: tax efficiency, cost of living, weather, community, or infrastructure. However, wherever you land, ensure that you have the necessary financial infrastructure in place. Because the visa might get you in the door, but a proper payment setup is what lets you actually enjoy it.

Getting paid across borders

I’ve watched friends move to Portugal or Mexico, land great clients, then lose 3 - 5% of every payment to terrible exchange rates and international transfer fees. Over a year, that adds up to thousands of pounds, dollars, or euros just... gone.

If you’re working remotely and getting paid in USD, EUR, or GBP whilst living abroad, you need a proper payment setup. Many traditional banks are often problematic in this regard, as they have slow transfers, hidden foreign exchange markups, and fees that make little sense.

Personally, I’d recommend Grey come in. You receive virtual USD, EUR, and GBP accounts, allowing clients to pay you directly without the headaches of international transfers. You convert currency at real rates, and you can withdraw to your local account quickly. It’s the kind of setup that saves you actual money every month.

Create your free Grey account today or download the app and start receiving international payments with better rates, faster transfers, and zero hassle.

‍

Best global banking setups for remote workers

•

•

2 min read

I’ve been watching remote workers struggle with banking for years, and the pattern is, rather interestingly, almost always the same. A remote worker lands a great remote job or signs their first international client, celebrates the win, then hits a wall when they try to receive their payment. The bank transfer takes two weeks. Fees take 4% of the payment. The exchange rate is mysteriously bad.

Traditional banking wasn’t designed for people who live in one country, work for clients in another, and get paid in different currencies. It’s built for the old model: one employer, one country, one currency. Remote workers need something different. A banking setup that handles complexity without leaking money at every step.

This article breaks down how to build a global banking system that actually works for remote work. Not just finding “the best bank,” but creating a setup that gives you control, transparency, and flexibility regardless of where you are or where your income comes from.

Why remote workers need different banking setups

Traditional banks assume you live, work, and earn money in one place. That model breaks immediately when you go remote.

Here’s what happens: you’re living in Nairobi, working for a client in San Francisco, getting paid in USD, but your local bank only handles KES. Every payment triggers international transfer fees, intermediary bank charges, and currency conversion at rates that include a 3 - 5% markup. A $5,000 payment loses $200 - $300 just moving from your client’s account to yours.

Remote workers also face account freezes when banks flag “unusual” international activity, limited access to holding foreign currency, poor customer support for cross-border issues, and surprise restrictions that only surface when you’re trying to access your own money.

A proper remote work banking setup solves these problems. You can receive payments in multiple currencies without forced conversion, hold foreign currency until rates are favourable, move money across borders affordably, and maintain access regardless of where you’re physically located. Most importantly, you get transparent fees with no surprises.

Core components of a solid banking setup

Before diving into specific solutions, you should understand what a complete setup typically includes:

Local bank account: Still necessary for rent, utilities, and local expenses. It’s your “home base” where you eventually convert and hold money in local currency.

Multi-currency account: Holds USD, EUR, GBP, and other currencies. It lets you receive international payments without immediate conversion and gives you control over when and how you exchange money.

Payment processor or fintech layer: Bridges the gap between international clients and your accounts, handles cross-border transfers efficiently, and often provides better FX rates than traditional banks.

Not everyone needs all three components, but understanding them helps you build what works for your situation.

Best multi-currency solutions for remote workers

Wise

Wise offers multi-currency accounts holding 50+ currencies, a debit card, and the ability to receive payments like a local in multiple countries—USD routing numbers, EUR IBANs, GBP account details.

Why remote workers use Wise: Real mid-market exchange rates with transparent fees (typically 0.5–1%), fast international transfers, and the ability to hold money in multiple currencies and convert when you choose, if a client pays you in USD but you don’t need the money immediately, leave it in USD until exchange rates improve.

Who Wise is best for: Remote workers receiving payments from multiple countries, freelancers with diverse client bases, and anyone tired of traditional bank FX markups.

Limitations: Not a full-service bank (no loans or credit facilities), and some countries have limited features.

Cost structure: Small percentage-based fees on conversions (0.4 - 2% depending on currency pair), minimal monthly fees.

Grey

Grey provides virtual USD, EUR, and GBP accounts, which are great for receiving international payments, with a focus on markets where traditional banking creates barriers for cross-border income.

Why remote workers use Grey: Simplified international payment reception, transparent FX rates, and faster setup than traditional banks. If you’re earning in foreign currencies but living elsewhere, Grey removes the friction.

Who Grey is best for: Remote workers in emerging markets, freelancers receiving regular USD/EUR/GBP payments, and anyone frustrated by local bank conversion rates.

Cost structure: Transparent fees focused on competitive FX rates, no hidden conversion markups.

Payoneer

Payoneer offers multi-currency receiving accounts, payment collection from platforms and marketplaces, and a prepaid debit card.

Why remote workers use Payoneer: Integrates seamlessly with freelance platforms (Upwork, Fiverr, Amazon), is widely accepted globally, and is good for receiving payments from US companies that prefer ACH transfers.

Who Payoneer is best for: Remote workers earning through platforms, e-commerce businesses, and anyone receiving regular payments from US companies.

Limitations: Higher fees than Wise (typically 2 - 3% on currency conversion), and withdrawal fees vary by country.

Cost structure: 2 - 3% currency conversion fees, withdrawal fees depend on method and destination.

Revolut

Revolut provides multi-currency accounts with excellent exchange rates (up to a monthly limit), budgeting tools, and various account tiers.

Why remote workers use Revolut: Competitive FX rates for moderate volumes, good for personal finance management.

Who Revolut is best for: Remote workers who travel frequently, those wanting banking and budgeting in one app, and people needing moderate multi-currency capabilities.

Limitations: Free tier has monthly FX limits, premium tiers cost £6.99 - £12.99/month, and some features vary by country.

Cost structure: Free tier available, paid tiers for higher limits and features, and competitive FX rates within limits.

Tax and compliance considerations

While it’s best to consult qualified professionals for your specific situation, you should know that your banking setup affects compliance.

Know where you’re tax resident. Your banking providers should generate proper documentation for wherever you file taxes. Keep detailed records of cross-border payments, currency conversions, and business expenses. Choose banking solutions that provide clear transaction histories, proper currency conversion records with dates and rates, and professional statements accepted by tax authorities.

If you’re running a business, integration with accounting software (Xero, QuickBooks) makes quarterly and annual reporting much easier.

Building your setup: Practical steps

Don’t try to set everything up at once.

Start by assessing your situation: How many currencies do you receive? How often are you paid? What payment methods do clients prefer? Calculate what you’re currently losing to fees and FX.

Choose one primary multi-currency solution based on your profile. Start with Wise, Grey, or Payoneer, depending on your needs. I recommend Grey.

Test with small amounts first. Don’t route your entire income through a new system immediately. Verify everything works and understand timing.

Keep your local bank but minimise what stays there. Use it for local expenses and as the final destination for converted funds.

Review quarterly. Check if fees are increasing, exchange rates remain competitive, or better solutions have emerged. Banking tech evolves quickly.

Red flags to watch for

All banking providers occasionally freeze accounts for security checks, but frequent unexplained freezes are a red flag. Monitor for sudden fee increases. Some fintech companies sometimes change structures without much warning. Test customer service before you need it urgently. Stay informed about regulatory changes in countries where you hold accounts. And remember: fintech platforms can shut down or change business models. Don’t put all your eggs in one basket.

What should you do?

Remote work banking isn’t about finding one perfect account; instead, it’s about building a system that handles complexity efficiently. Good banking is invisible: money flows smoothly, fees are minimal, and you have control. Bad banking is constant friction: frozen accounts, surprise fees, money lost to poor FX rates.

The cost of optimising your banking gives you reliable access to your money regardless of where you are or where it’s coming from. Audit your current setup. Calculate what poor banking is actually costing you. Then build something better.

Open your free Grey account today and build a banking setup that works as hard as you do. Receive international payments in USD, EUR, and GBP with transparent rates, fast transfers, and the flexibility remote work demands.

‍

Offshore bank accounts: What’s realistic in 2026

•

•

2 min read

For years, offshore bank accounts were seen as tools for billionaires and secretive wealth structures. In 2026, that perception is changing. Freelancers, remote founders, and global professionals earning across borders are exploring offshore options for practical reasons, currency flexibility, asset diversification, and smoother international transactions.

Offshore banking is not new, but the environment around it has evolved. Stricter compliance rules and global transparency standards mean it is no longer about secrecy, but structure and regulation. Unlike standard international accounts, offshore accounts are opened outside your country of residence and may offer broader multi-currency access. For freelancers, this can support better global income management. This article explains what is realistic and relevant in 2026.

Also read: Offshore accounts vs international bank accounts explained

Why offshore accounts make sense for global freelancers

As global work expands and borders matter less, offshore accounts are becoming a practical option for internationally minded freelancers and founders.

1. Investment opportunities

With more freelancers earning from global clients and building wealth independently, access to international investment options matters more. Some offshore accounts open the door to foreign funds and markets beyond your home country. If your income is global, aligning your investments with that reality can feel more strategic.

2. Asset protection

Economic uncertainty, policy shifts and currency swings are becoming more common. Keeping all your money in one country increases exposure to local risks. Holding part of your funds in a stable jurisdiction adds balance and resilience, especially when your income depends on cross-border work.

3. Managing foreign exchange fluctuations

Remote work means more people are paid in foreign currencies. Exchange rates move daily, and automatic conversions can quietly reduce earnings. Offshore accounts often let you hold funds and convert when rates are favourable, giving you more control over how much you actually keep.

4. Holding foreign currencies

Many freelancers now invoice in dollars, euros or pounds. Converting every payment immediately is not always efficient. Offshore structures can help you retain those currencies, making it easier to pay for tools, subscriptions, or travel abroad without incurring repeated conversion costs.

5. Doing business in multiple countries

It’s common to have clients in three or four countries at once. Traditional local accounts are not always built for that. Offshore accounts can simplify receiving and sending payments internationally, helping you operate more smoothly as your business naturally becomes more borderless.

Also read: The easiest way to open an offshore bank account online for free

The realities of offshore banking today

1. Stricter global transparency rules

‍Offshore banking is no longer about secrecy. Thanks to global agreements like the Common Reporting Standard (CRS), banks in many countries automatically share account information with tax authorities. So if you’re hoping to “hide” money abroad, that’s unrealistic in 2026. Offshore accounts are legal, but they’re transparent. The key is compliance, not concealment.

2. Higher compliance and documentation requirements

‍Opening an offshore account today feels a bit like applying for a mortgage. Banks want to know who you are, where your money comes from, your tax residency, and sometimes even your business model. Expect detailed KYC checks, proof of address, source-of-funds documents, and possibly interviews. It’s thorough, but that’s the new normal.

3. Minimum deposit thresholds vary widely

‍Some traditional private banks may require $50,000 or more just to get started. Others, especially digital or fintech-based options, may have little to no minimum balance. The reality in 2026 is that access depends on the institution. It’s less about geography and more about the type of bank you choose.

4. Offshore doesn’t mean tax-free

‍This is the biggest misconception. Where your account is located doesn’t determine whether you pay tax, your country of residence does. If you’re tax-resident somewhere, you usually must declare global income. An offshore account can help with currency diversification or international payments, but it doesn’t cancel your tax obligations. Always think compliance first.

Also read: Top offshore bank accounts US citizens should consider this year

How global workers can prepare for offshore banking

Global workers must adapt to stricter rules, digital banking, and international tax obligations. Preparing early ensures compliance, smoother payments, and career flexibility in 2026’s global landscape.

1. Understand compliance rules

Every country has its own financial and tax regulations. International reporting standards like CRS mean offshore accounts are visible to authorities. Knowing these rules keeps your finances legal, prevents penalties, and avoids costly surprises while working globally.

2. Keep documentation ready

Banks, employers, and regulators now expect thorough records. Identity, proof of income, tax residency, and source-of-funds documents are essential. Staying organised ensures smooth account openings, international transactions, and faster approvals for any global work opportunity.

3. Use digital banking tools

Digital banks and fintech solutions make international payments faster, cheaper, and easier to manage. Learning these tools helps you handle multiple currencies, track transactions securely, and stay efficient while working across borders in 2026’s remote-friendly environment.

4. Plan tax responsibilities

Offshore accounts don’t remove your tax obligations. You must declare worldwide income based on residency rules. Planning avoids fines, audits, and surprises, while allowing you to optimise finances and stay fully compliant with global regulations.

LDMAG1

Managing global payment seamlessly

As work becomes increasingly global, managing payments across borders can be challenging for freelancers, remote workers, and business owners. Offshore accounts offer practical solutions, and Grey stands out as a reliable option. With Grey, you can hold multiple currencies, benefit from competitive conversion rates, and even get a virtual card for online shopping.

Whether you’re receiving payments from clients abroad or making international purchases, Grey simplifies the process. To start, simply sign up on the website or download the app on your mobile device and take control of your global finances.

‍

Arrow (up)

Back to top
