


What is virtual banking?

Ngozi Enelamah

TABLE OF CONTENT

SHARE THIS POST

The world has gone digital and there are newer alternatives to all that we’ve done in the past, banking inclusive. Gone are the days when users had to queue for long hours to carry out the simplest of transactions like sending or receiving cash, especially foreign currencies. 

People no longer have to spend the bulk of their time in the banking halls trying to confirm their identities or filling out lots of paperwork before they can send or receive currencies other than the Naira, all thanks to the emergence of Virtual Banking Services.

However, many are yet to understand this newest way of sending and receiving money without stress. Hence, the need for this guide.

Some of the questions that we have heard about Virtual Banking include, what it is, how it is different from the traditional banking system and the advantages of using virtual bank accounts. So, let’s delve into it…

What is virtual banking?

Try to picture these scenarios:

You need to send some money to a friend, confirm that a customer has sent you payment for the services you rendered through your bank statement or that you need to change some Naira into USD to make an international payment for the new Oculus headset you purchased.

What if, for each of these, you had to go into the banking hall to get it done and there wasn’t any other way? Basically, that’s traditional banking.

And virtual banking is the alternative way you’ve probably been doing all of these things from the comfort of your mobile phone or computer, without the need to visit any physical bank.

A simple definition of virtual banking is access to all banking, business and financial related services without visiting any physical location before carrying these services out. A virtual bank allows you to bank online. 

How is a virtual bank different from a traditional bank?

The major difference between both forms of banking is in the location. While a traditional bank requires a physical location to operate and carry out most of its operations, a virtual bank operates fully online. Instead of making over-the-counter transfers, you can send them online.

It is, however, worth noting that traditional banks now offer virtual services via their mobile apps or internet banking, yet they are not referred to as virtual banks because of this. A virtual bank has certain advantages over traditional banks (even with virtual services).

Read more: Different Types of Banking: Pros and Cons

What are the advantages of virtual banking?

A major advantage that Virtual Banks have over their traditional counterpart is that virtual banks save time, energy and money; they eliminate the stress that frequently accompanies traditional banking. Here are some of the main reasons why virtual banking is trending in 2022:

1. Cheaper services

Virtual banking is considerably cheaper than traditional bank services and one of the reasons for this is because of the mode of banking. Traditional banks require brick and mortar locations that further need manpower to maintain business.

This means the traditional bank will offer lower rates and higher fees in order to make profits. The absence of these overhead costs in a virtual bank means they can offer better interest rates and significantly reduce their fees to favour the customer.

2. Convenience

As mentioned above, a virtual bank makes it possible to complete all your banking activities on the internet. That means you can complete local and international transactions with ease. You can also order your physical bank card and have it delivered to your home or request a virtual card to make online payments. All with a few taps on your phone or clicks on your computer.

You can also have issues resolved swiftly online without having to queue for hours after filling out forms to talk to a customer support representative for less than 5 minutes at a physical location.

3. Full control over your accounts

With Virtual Banking Systems, you can control what happens to your money at every point in time. You can easily make a budget based on your cash inflow and outflow and there is no need to visit the bank every month end to access your bank statement. Virtual banks give you 24/7 access to your accounts so you can plan your finances and complete transactions on time.

Create Grey virtual accounts

Are virtual banks safe?

One of the major concerns of people regarding virtual banking is security? People ask: are virtual banks safe? What happens to my money when a virtual bank closes?

You should, however, keep in mind that virtual banks are licensed to operate just like every other bank. The lack of a physical location has helped to adapt banking to the changing world and make banking services more accessible to people.

And while banking on the internet can be scary to many because of scammers and hackers, these virtual banks take extra precautions to ensure that their platforms are very secure and fit for financial operations.

What this means for the bank is that they invest in sensitizing people about online security while using state-of-the-art security protocols to ensure that their customers’ data and money are always safe.

Read also: How to Receive Money from the UK in Nigeria

Here are some security tips for anyone banking on the internet to keep in mind:

  1. Use a strong password: Your password is the gate pass into your virtual bank account so it is important that you use a strong password that is not easy for anyone else to guess. A good way to ensure your password is secure is to use a password manager.
    This software helps you generate strong passwords for your account. It also saves you the hassle of trying to remember multiple passwords by saving them in a secure vault that only you can access.
  2. Verify emails and web addresses: Before entering your bank details on any website, you should ensure you are on the official page of your bank. Even when you get emails that are from your bank, you should confirm that they are not phishing emails.
  3. Use 2FA: Two-Factor Authentication (2FA) is an extra layer of security added to internet accounts to ensure that your account can only be accessed by you. 2FA requires that you enter an OTP (One Time Password) sent to your mobile number or from an authenticator app (such as Google authenticator or Authy) after entering your password to ensure it is really you.
  4. Avoid public WiFis: Public wifis can be accessed by anyone. When you are connected to one, it is best to avoid accessing your banking apps. Only access your financial accounts while on your private network.

How to get started with a global virtual bank account

Seeing that you can use a virtual bank for local and international transactions such as sending money to foreign bank accounts or receiving money from abroad and also converting your local currency to foreign currencies, the adoption of virtual bank accounts is on the rise.

Grey offers one of the easiest virtual banking services in Nigeria and to get started is very simple:

1. Create an account

The first step is to create an account. Simply visit Grey and provide your basic details.

2. Complete KYC

KYC (Know Your Customer) allows businesses to protect you from fraud and ensure that fraudulent activities are not carried out on their platform. With Grey, the process is straightforward and hitch-free.

3. Get a virtual account

After successfully creating an account and completing KYC, you will be able to request your virtual accounts. Grey offers virtual USD, EUR and GBP accounts which you can use to complete international transactions. Once your account is approved you will be able to send and receive money from anywhere in the world. You will also be able to convert to naira which you can withdraw to any Nigerian bank.

Final thoughts

You can now begin your virtual banking journey with Grey, especially on the global scene.

Get Started with Grey Virtual Bank Account

Last updated:

June 15, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

International freelance platforms Indians trust for steady payments

•

•

2 min read

Finding freelance work as an Indian professional has never been easier. Many platforms connect you to clients worldwide, often paying in foreign currencies. However, the reality of how difficult it is to get paid eventually comes up.

If you’ve ever watched your earnings shrink because of hidden FX markups, or waited for weeks for a payout that was supposed to take five days, you’ll know what I’m talking about. For Indian freelancers, creating a payment system that doesn’t leak money at every step is a significant challenge.

This article breaks down the international freelance platforms Indian professionals actually trust for steady, reliable payments. I’m not ranking them by popularity or features. I’m focusing on what matters most: payout reliability, transparency, and how well they actually work for freelancers based in India.

What does "steady payments” actually mean for Indian freelancers?

Before diving into platforms, let’s clarify what steady payments look like in practice.

  1. Payout speed and frequency: Some platforms pay weekly, others monthly, and a few offer instant withdrawals. The key is predictability. For example, a platform that pays every Friday is more reliable than one that pays “within 7-10 business days”, which sometimes stretches to 15.
  2. FX transparency and hidden fees: This is where most freelancers lose money. A platform might advertise "no fees,” but then apply a 3 - 4% markup on currency conversion. Steady payments mean transparent foreign exchange rates with minimal hidden costs that eat into your earnings.
  3. Escrow and dispute protection: Platforms with escrow systems hold client payments until work is delivered and approved. This protects you from clients who ghost after you’ve completed the job. Dispute resolution processes are also important, especially when dealing with international clients across different time zones.
  4. Regulatory and compliance considerations: Indian freelancers earning foreign income must comply with FEMA regulations and file taxes properly. Platforms that provide clear invoices, payment records, and integrate well with Indian tax systems make compliance easier, not harder.

Also read: Best freelance platforms to earn US dollars in Indonesia

Trusted international freelance platforms

Let’s examine platforms grouped by what they excel at for Indian freelancers.

Platforms with escrow-based payment protection

  1. Upwork: Upwork remains one of the most trusted platforms for Indian freelancers, primarily due to its escrow system. The escrow system protects you from non-payment. Once a client funds a project, you know the money exists. Weekly billing cycles mean regular income if you’re on an hourly contract.
  2. Fiverr: Fiverr’s escrow model is simple: clients pay upfront, and funds are released to you after order completion. For Indian freelancers offering fixed-price services, this creates predictable cash flow. Once the order is marked complete and the buyer doesn’t request revisions within three days, payment is guaranteed. A small downside, however, is that the payment cycle is 14 days.
  3. Toptal: Toptal is an exclusive network for top freelancers in software development, design, and finance. It operates on an escrow basis, with clients funding work upfront and payments released on a predictable schedule. Toptal handles invoicing, contracts, and payment collection. Payments are reliable, and disputes are rare because clients are vetted as thoroughly as freelancers.

Also read: Freelance platforms with high payout rates in Egypt

LDMAG1

Platforms known for fast, predictable payouts

  1. Freelancer.com: Freelancer.com offers milestone-based escrow and weekly payouts for hourly projects. It’s not as polished as Upwork, but Indian freelancers appreciate the speed of payouts and flexibility. You can request withdrawals as frequently as you like (though fees apply per transaction).
  2. Guru: Guru operates with SafePay, an escrow system that releases funds after work approval. Payouts are processed quickly, and the platform supports multiple withdrawal methods for Indian freelancers. Guru’s relatively lower service fees (5 - 9%) make it attractive for many freelancers. Generally, payments are processed within 24 to 48 hours of receiving withdrawal requests.

Also read: Top platforms to receive freelance payments worldwide

What to consider when choosing the right freelance platform

Your ideal platform depends on where you are in your freelance journey.

Beginners

Start with Upwork or Fiverr. Both offer escrow protection, steady workflows, and built-in client pipelines. Yes, the fees are high, but the security and volume of available work justify the cost while you’re building your portfolio and reputation.

Full-time freelancers

Consider diversifying your work across Upwork, Toptal and direct clients found through LinkedIn. Use Grey to receive payments from direct clients.

Also read: Safe ways to receive international payments in India

Made a decision yet?

Steady payments don’t necessarily come from platform loyalty or luck. They come from understanding how money moves, choosing platforms that align with your work style, and setting up a payment stack that doesn’t leak income at every step.

For you, that could mean using escrow-based platforms for security, understanding FX markups, and pairing marketplace work with tools that give you better control over your earnings. The platforms you choose and how you get paid matter as much as the work itself.

Create your free Grey account today or download the app and start receiving international payments with better FX rates, faster payouts, and full transparency.
‍

FIRC, taxes and compliance for Indians earning foreign currency

•

•

2 min read

Indians earning foreign currency from remote work, international businesses, content creation, and so on often face additional regulations than those earning locally. These regulations can be tricky to navigate, especially for newbies. Many risk regulatory infringements, withheld payments, or paying the wrong tax. This article explores FIRC, taxes, and compliance for Indians earning in foreign currencies.

Also read: Safe ways to receive international payments in India

What is FIRC, and why does it matter?

A Foreign Inward Remittance Certificate (FIRC) is an official document issued by Authorised Dealers (ADs), which may be banks or authorised payment providers, confirming that funds received in India originated abroad. It serves as a verifiable record of the transaction, including details like

  • The Unique Transaction Reference (UTR) number
  • The remitted amount in foreign currency
  • The INR equivalent
  • The exchange rate
  • A purpose code
  • Other details, including the date, sender, and recipient information

Since 2016, most ADs issue electronic versions (e-FIRC) and not a physical document. The e-FIRC is digitally signed and sent to the RBI's Export Data Processing and Monitoring System (EDPMS).

Indians earning foreign currency require an FIRC because it proves their income is legitimate. It is also essential for audit, regulatory, and tax purposes. However, you might not need an FIRC for every single foreign payment you get. FIRCs are often requested during GST audits or by banks when clarifying the nature of inflows. Businesses claiming GST export benefits or LUT exemptions almost always need them.

If you are a remote worker receiving large or irregular foreign payments, banks may request an FIRC to correctly classify the payment under RBI guidelines. You might also need it when applying for loans, visas, or financial products as credible income proof.

Also read: A guide for Indians getting paid by clients abroad

How do you get your FIRC?

Obtaining an FIRC is straightforward. It is usually issued by the payment platform you are using.

  • Get your foreign currency payment in your Indian bank account.
  • Retrieve the transaction information, including the sender’s name and address, your account number, UTR (Unique Transaction Reference) number, amount, date, and the specific Purpose Code.
  • Apply to your bank (through their portal, branch, or app) for the FIRC/FIRA.
  • Your bank will review the details and upload the payment info to the government's EDPMS.
  • The bank then issues the FIRC/FIRA, often digitally, usually within a few days to a few weeks.

Taxation for Indians earning foreign currencies

Paying taxes on foreign income in India mostly depends on your residency status. If you are earning globally in foreign currencies as an Indian resident, you are required to pay taxes. If you are a non-resident Indian (NRI), only the income you make in India is taxable. Entirely foreign-sourced income is usually exempt from taxation.

Foreign earnings must be converted into INR for tax filing. The conversion is done using the RBI reference rate or notified rates, and not the rate you converted at. It is important to make this distinction because your tax obligation may be slightly different from the INR you actually got. Don’t get confused, this is completely normal and legally accepted.

Double Taxation Avoidance Agreement (DTAA)

India has DTAAs with over 90 countries to prevent the same income from being taxed twice. So, if you are already paying taxes in any of those countries, you can apply to avoid paying taxes on the same income. To claim DTAA benefits, you must:

Also read: How freelancers in India are taxed on foreign payments

Managing your foreign earnings

Earning foreign currency as an Indian professional is increasingly common. The real challenge lies in managing taxes and remaining compliant. Understanding FIRCs and handling taxes correctly ensures you can focus on your work rather than paperwork. With Grey’s multi-currency accounts, you can receive payments in USD, EUR, and GBP without being forced to convert to INR at unfair bank rates. Managing all your foreign earnings on one platform also ensures you can easily access your financial records, file your taxes, and remain compliant.

Sign up on Grey or download the app to get started today!

‍

Nigeria taxes for international payments in 2026: What remote workers must know

•

•

2 min read

A new tax conversation is underway in homes, WhatsApp groups, and Twitter threads across Nigeria, particularly among remote workers, freelancers, creators, and individuals earning money from clients or platforms abroad.

Why? Because Nigeria’s new tax reforms, effective 1 January 2026, change how foreign and remote income is treated, and for many Nigerians earning in USD, GBP, EUR, or other currencies, this actually matters.

In this article, I’ll break down what the new rules say, what counts as taxable income, how tax residency is determined, and what you can (and should) do to stay compliant without sounding boring (I know, I know, tax can be boring).

1. Nigeria’s 2026 tax reforms — the big picture

Nigeria has rewritten key parts of its tax laws through the Nigeria Tax Act and related fiscal reforms. One major shift is clarity around worldwide income for tax residents, which means if you live in Nigeria long enough, your foreign income can be taxable here too. However, the government has also made some crucial clarifications that should put many minds at ease:

  • Personal remittances (money sent home for support or gifts) are not subject to tax.
  • Income earned abroad by non-resident Nigerians (i.e., people living outside Nigeria) is generally exempt from Nigerian tax.
  • Dual taxation (being taxed abroad and in Nigeria on the same income) is addressed through Double Taxation Agreements (DTAs) and unilateral reliefs.

The major takeaway is that tax applies, but not to every situation, and you won’t be taxed just for sending love or support home.

Also read: How to manage freelance income and taxes in South Africa

2. Who is considered taxable under the new system?

A. Tax residents

Under the reforms, someone is typically a tax resident if they spend at least 183 days in Nigeria in a 12-month period, or have strong economic and family ties to the country.

If you meet the resident criteria, Nigeria may tax your worldwide income, meaning income earned abroad could be taxable here.

B. Non-residents

If you live and work outside Nigeria and don’t meet the 183-day presence test, your foreign income usually isn’t taxable in Nigeria.

That’s important for diaspora Nigerians who are sending money home or earning abroad without being resident in the country.

3. What counts as “international income”?

Under the new framework, income earned from work done outside Nigeria, even for a foreign company, can be taxable if you’re a Nigerian tax resident.

That includes:

  • Remote salaries from foreign companies
  • Freelance income from overseas clients
  • Platform earnings from YouTube, Upwork, Fiverr, etc.
  • Influencer revenue or ad revenue from social platforms
  • Consultancy fees from clients abroad

Importantly, gifts or genuine remittances, like money a relative sends for support, are not considered taxable income.

Also read: Tax basics every digital nomad needs to know about earning abroad

4. Self-declaration: you’re on your own with foreign pay

This is a key practical point.

If a local company hires you, they usually deduct tax at source (PAYE). But with a foreign company, they typically don’t, so that means you have to self-declare your income.

The Committee on Fiscal Policy and Tax Reforms has made it clear: if you earn from overseas and don’t tell the tax authorities, they can track those inflows (via banks or international data sharing) and treat them as undeclared taxable income, which can attract penalties, interest, and back taxes.

The responsibility to report and pay tax if you’re a resident is yours.

LDMAG1

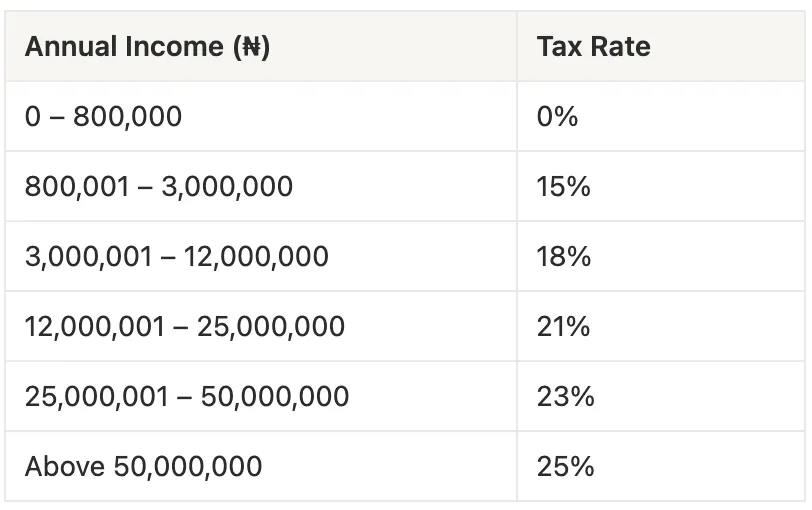
5. The new income tax schedule for Nigerian workers

Here are the applicable tax rates by annual income level:

__wf_reserved_inherit

6. Registering and filing: How to stay compliant

If you are taxable in Nigeria, there are a few practical steps to follow:

A. Get a Tax Identification Number (TIN)

Most people get this when they open a bank account or register with a tax portal.

B. Register with the state tax authority

If you’re self-employed or a freelancer, you’ll file returns yourself.

C. File returns annually

Declare your worldwide income in naira. Digital platforms, such as TaxProMax are designed to make this process easier.

D. Keep records

Documents such as invoices, client contracts, bank receipts, and proof of foreign withholding tax are all crucial.

7. Enforcement and penalties

If you fail to register with Nigeria’s tax authority, you’ll incur a fine of ₦50,000 in the first month, followed by ₦25,000 for every subsequent month. Failing to file returns will incur a fine of ₦100,000 ($67.19) in the first month, followed by ₦50,000 for every subsequent month.

Tax authorities will investigate the information provided, and false declarations can result in fines of up to ₦1 million or a prison term of up to three years, or both.

Also read: How to declare taxes as a Brazilian freelancer earning from abroad

8. Common remote worker tax questions answered

Here are a few real-world questions you may be thinking about:

Q: I earn abroad but live outside Nigeria, do I pay tax here?

Generally, no, as long as you’re a non-resident and your income isn’t Nigerian-sourced.

Q: I’m back in Nigeria for part of the year. Do I need to pay tax on my overseas income here?

It depends on whether you pass the 183-day test and become a tax resident.

Q: What if I never report my foreign income?

The government is establishing data-sharing arrangements with over 100 countries to monitor these flows and enforce compliance.

Make informed decisions

Nigeria’s 2026 tax reforms are a big deal, especially if you’re part of the growing global workforce. But they’re also clearer than many expected. Earnings from abroad can be taxable, but there are reliefs; they’re not applied to gifts or personal remittances, and your tax residency and situation matter a lot.

The most important thing you can do is stay informed, keep records, and report what you earn if you fall into the taxable category. By understanding the rules ahead of time, you’ll be prepared for 2026 and beyond.

‍

USDC on Solana vs Ethereum: Which should you use?

•

•

2 min read

Solana or Ethereum? Both can move the same dollar-backed stablecoin, but the difference becomes clear when speed and transaction fees matter.

Solana can settle a USDC transfer in a few seconds, usually for a fraction of a cent. Ethereum, on the other hand, can take several minutes, with fees that increase when the network is busy. For a straightforward payment, Solana can be the more practical option when keeping costs low matters.

Both versions of USDC are issued by Circle and designed to maintain a 1:1 value with the US dollar. The real choice is therefore not between two different stablecoins, but between two networks. The better option depends on where the money is going, which network the recipient supports, and whether speed, low fees or access to Ethereum’s wider ecosystem matters most.

What is the difference between USDC on Solana and Ethereum?

The main difference between USDC on Solana and Ethereum is the blockchain network used to settle your transaction, even though both versions are issued by Circle, designed to maintain a 1:1 value with the US dollar and redeemable through the same issuer. When you choose between them, you are therefore choosing a different settlement layer, with Solana generally offering faster and cheaper transfers while Ethereum can become more expensive when the network is busy.

The distinction becomes more important when you come across native and bridged USDC. Native USDC is issued directly by Circle on the blockchain where you hold it, so USDC issued natively on Solana is Circle-issued USDC on Solana, while native USDC on Ethereum is issued directly on Ethereum. This means you should not assume that every token labelled “USDC” has the same issuance structure.

Bridged USDC represents USDC that has been moved between blockchains using a bridge, rather than being directly issued by Circle on the destination network. Before sending your USDC, check the network supported by the recipient and whether you are dealing with native or bridged USDC, because sending through an unsupported network can make it difficult or impossible to recover your funds.

How fees and settlement times compare

When you compare Ethereum and Solana for USDC transfers, the biggest differences you'll notice are the network fee and how quickly your transaction settles. Ethereum fees change with supply and demand, so when more people compete for limited block space, the base fee rises and you may pay an additional tip to have your transaction prioritised. Solana generally offers lower and more predictable fees, which can make it more practical for frequent transfers.

On Ethereum Layer 1, you may pay around 0.01–0.20, with settlement taking roughly 12 seconds to several minutes depending on network conditions and the level of finality you require. Solana typically settles transactions within seconds at a fraction of a cent.

Ethereum Layer 2 networks can reduce the cost further by processing transactions away from the main chain and later posting transaction data to Ethereum. This gives you faster execution and lower fees, although the final settlement process works differently from a direct Layer 1 transaction. Network conditions change, so check current fees before sending.

Also read: USDC to USD: How to convert your stablecoin to cash

What happens if you send USDC to the wrong network?

Sending USDC to the wrong network can put your funds at risk, and whether you can recover them depends on where the money was sent and who controls the receiving wallet. If the destination supports the network you used, recovery may be possible, but if it does not, you may need help from the exchange or wallet provider, with no guarantee that the funds can be recovered.

Before sending, check that the network selected on your platform matches the network supported by the recipient. Do not rely on the wallet address alone, because the same address format can sometimes work across different networks. If you use a USD bridge to move USDC between blockchains, confirm the destination network and the type of USDC being received before approving the transaction.

For a large transfer, send a small test amount first, then check the network name, token and destination address before sending the remaining balance. Once a blockchain transaction is confirmed, it generally cannot be reversed.

Also read: How to convert and use USDC in Nigeria

How to choose a network for your transfer

Choosing a network for your USDC transfer comes down to three things: how much you are sending, where the money is going and how quickly you need it to arrive. Start with the destination, because the cheapest or fastest network is not useful if the recipient’s wallet or exchange does not support it. Check the supported networks before you enter the amount or confirm the transaction.

Next, consider the amount you are sending. For a small transfer, a network with very low transaction fees can help you avoid losing a noticeable percentage of your money to fees. For a larger transfer, the fee may matter less, but you should still confirm that the network supports the exact USDC you are sending.

Finally, consider urgency. If you need the money to arrive within seconds or minutes, a faster network may make more sense. If timing is flexible, you can compare fees and choose the cheaper option. Whatever you choose, confirm the network on both sides before sending.

Open a multi-currency account to send and receive USDC

Turning USDC into local currency usually involves one more step after receiving your payment: moving the funds from your crypto wallet or exchange into a bank account where you can spend them. A multi-currency account can fit between these steps, giving you a place to receive and hold funds before converting them into the currency you need.

With Grey, you can open a multi-currency account and use it to manage your international payments in one place. Once you receive USDC, you can move the funds through the available conversion and withdrawal options rather than immediately sending everything to a local bank account. This can give you more control over when you convert and where your money goes.

The process is straightforward: receive your USDC, convert or off-ramp it through a supported route, then withdraw the resulting currency to your local bank account. The exact steps depend on the currencies and payment routes available to you, so check the supported options before starting your transfer.

Frequently asked questions

Is USDC on Solana the same as USDC on Ethereum?

USDC on Solana and USDC on Ethereum are both issued by Circle and designed to maintain a 1:1 value with the US dollar, but they operate on different blockchains. The main differences are transaction speed, network fees and where you can send or receive each version of USDC.

Which network has lower USDC fees?

Solana generally has lower USDC transaction fees than Ethereum, with transfers typically costing a fraction of a cent. Ethereum fees can increase when the network is busy because users compete for limited block space. Before sending, check the current network fee and make sure the recipient supports your chosen network.

Can I send USDC from Solana to an Ethereum wallet?

You cannot send native USDC on Solana directly to an Ethereum-only address and expect it to arrive correctly. To move USDC between networks, you need a supported bridge or exchange that handles the transfer. Always confirm both the sending and receiving networks before approving the transaction.

What happens if I pick the wrong network?

Choosing the wrong network can make your USDC difficult or impossible to recover, depending on the receiving wallet or exchange. Before sending, check the network supported by the recipient and make sure it matches the network selected in your wallet. For larger amounts, consider sending a small test transaction first.

Is USDC on Solana safe?

USDC on Solana can be safe when you use the official, native version of USDC and send it through a supported wallet or exchange. Your biggest risks usually come from choosing the wrong network, using an unsupported token or sending funds to an incorrect address. Always verify the token and destination.

How do I convert USDC to my local currency?

To convert USDC into your local currency, you typically send it to a supported exchange or financial platform, sell or convert the USDC, then withdraw the resulting funds to your bank account. A multi-currency account can also give you a place to receive and manage funds before converting them.

Where Filipinos working remotely should store savings: USD or PHP?

•

•

2 min read

There is usually a dilemma among Filipino remote workers: whether to save in USD or PHP and where to save. This concern is understandable, as many of them earn in USD but spend every day in PHP. Converting every now and then can erode your earnings, and it just makes sense to convert all your earnings into PHP. Before you jump into a decision, let’s explore the pros and cons of saving in either USD or PHP, and how you can make an informed choice about where to store your savings.

Also read: Remote jobs abroad for Filipinos: a simple starter guide

Should you store your savings in USD?

The US dollar is a stable currency widely used in global transactions. For Filipinos earning in dollars, saving in USD reduces the risk of losing money to PHP’s volatility and avoids repeated conversion costs. You are at peace during periods of local economic uncertainty because the USD's purchasing power tends to hold up better over time during financial crises.

Saving in USD is also a great idea if you travel abroad frequently, pay for international education, make international payments, or invest in global assets. Keeping your earnings in USD gives you control over when to convert, instead of being forced to convert at potentially unfavourable rates. You can wait until rates are favourable before converting to PHP.

However, saving in USD isn’t all about the positives either.  If most of your expenses are in PHP and you hold all savings in USD, you may be exposed to short-term exchange rate swings when you need PHP. If the peso improves, converting USD could result in a loss.

There is also a gap it creates in your local cash flow. You think you have enough pesos to last a period, only to find yourself needing urgent access to more money. You can only hope to convert your USD savings just in time to meet that need.

Saving in USD also yields very little interest. USD accounts in Philippine banks offer much lower rates: 0.1-1.1% for savings, and 1-3% for time deposits on longer terms.

In summary, the USD is best used as a store of value rather than for daily spending.

Also read: Why freelancers in the Philippines struggle with foreign currency access

Should you store your savings in PHP?

Saving in PHP is well-suited to everyday life for most Filipinos because they pay for local expenses such as groceries, rent, and utilities in pesos. This removes the need for frequent conversions and reduces conversion fees that can gradually add up and eat into your earnings. With the PHP's current stability and low inflation (1.5% in November 2025), your savings maintain purchasing power for domestic needs without the hassle of monitoring exchange rates.

A major advantage of saving PHP is the higher interest rates, especially through digital banks. Some offer 3-6% on savings or time deposits, which is more than what you’ll get with USD. Saving in PHP provides better real returns, even after adjusting for the Philippines' current inflation rate.

On the downside, the PHP is more volatile than the USD. Its value is influenced by domestic economic factors such as trade deficits, natural disasters, or policy changes. If the peso weakens as projected, your savings could lose international purchasing power, impacting overseas travel or imports.

In essence, PHP is ideal for short-term liquidity and local focus but exposes you to currency risks in a globalised economy.

LDMAG1

Where should Filipinos working remotely store their savings: USD or PHP?

If we are to piece all of these together, here is a direct comparison of the pros and cons of saving in either USD or PHP

  • Stability: Storing funds in USD offers high stability and shields savings from local currency depreciation, whereas the PHP is more vulnerable to exchange rate fluctuations and local economic factors.
  • Accessibility: Savings in USD are easily accessible for international travel or online purchases in foreign currencies. Conversely, using a PHP account for international expenses requires currency conversion, which may involve additional fees and less favourable rates.
  • Transaction fees: Using multi-currency accounts or virtual wallets to receive foreign payments often results in lower conversion fees when holding funds in USD. On the other hand, receiving foreign currency into a traditional PHP account results in higher conversion fees and unfair exchange rates.
  • Interest rates: While PHP savings accounts may offer higher interest rates, these potential gains could be offset by inflation or depreciation. Interest rates on USD accounts at local banks are typically lower.
  • Inflation hedge: The USD generally provides a better hedge against local inflation compared to the PHP. Inflation in the Philippines can erode the purchasing power of the pesos you saved faster than the dollars.

Also read: Safe ways Filipinos keep their money when the Peso feels uncertain

So, USD or PHP, which should you save in?

For most Filipino remote workers, the real answer is not choosing one over the other, but using both intentionally. Using a balanced approach, you can hold part of your savings in USD and part in PHP to minimise risk, regardless of how the exchange rate moves.

Even with the right currency mix, where you store your money can determine whether you truly protect your income or slowly lose money to fees, forced conversions and poor exchange rates.

This is where modern payment solutions like Grey come in. Grey allows you to open a multi-currency account to receive USD, hold it, and convert to PHP whenever you need to. This gives you total control over timing your conversion and the transparency to monitor the exchange rates in real time. Instead of choosing between USD and PHP, you can manage both in one place, on your own terms.

Sign up on Grey today or download the app to manage your finances efficiently.

‍

Year-end budgeting tips for remote workers earning globally

•

•

2 min read

As the year draws to a close, remote workers and digital nomads earning income from global sources start reflecting on their finances and plan for the year-end. Earning globally comes with challenges such as managing multiple currencies, filing taxes, and dealing with fluctuating exchange rates. The year-end is a critical time to review your finances, reduce liabilities, and plan for the new year.

Effective budgeting is essential for remote workers, as it improves tax compliance while protecting against unstable income and currency fluctuations. This article provides year-end budgeting tips for remote workers earning globally.

Also read: A complete guide to budgeting as a remote worker

Review your expenses

A thorough year-end financial review is a good starting point for budgeting. Sort your expenses over the past 12 months into the essentials (accommodation, food, transport, healthcare), discretionary (entertainment, travel perks), and unexpected costs. This helps expose unnecessary expenses draining your purse that you might need to cut down on, like the gym you have refused to go to but still pay for monthly.

Use apps such as YNAB (You Need A Budget) or even a spreadsheet to track your expenses and earnings. Compare your actual spending to the amount you initially allocated. Review the amount you earned in USD, EUR, or GBP after conversion, along with the exchange rates applied. You may discover you are losing a lot to currency exchange.

Manage risks and minimise fees

Earning in multiple currencies exposes remote workers to currency fluctuations, which are usually worse at year-end. You should protect your income by using multi-currency accounts. Platforms like Grey offer low-fee conversions and let you manage USD, EUR, and GBP while supporting withdrawals in multiple currencies.

Also read: Mistakes you are making as a remote worker

File your taxes

Managing taxes can be tricky for remote workers earning globally, as they may have tax obligations in multiple countries. Following the tax guidelines applicable to you is essential to avoid double taxation and comply with tax regulations. Consult with tax professionals if required. Keep records accurately and apply for available deductions.

LDMAG1

Build your savings and emergency funds

Towards the end of the year, many remote workers tend to make more money and work less. This makes it a great time to add to your savings and emergency funds. You can automate your savings with a certain percentage of your income automatically moving to your savings account once you get paid. Aim for an emergency fund covering 3-6 months of expenses, preferably in a stable currency. Diversify your portfolio by looking into low-risk investments.

Plan for the year ahead

Having reviewed your finances for the year, you can now forecast next year’s budget. Identify areas for improvement and set SMART goals.

Also read: How to plan your 2026 financial goals before January starts

Budgeting tips for remote workers earning globally

By reviewing expenses, managing taxes proactively, and using smart tools, you can end the year on a high note and enter the new year with confidence. Here is a summary of what you need to do:

  • Create a baseline budget.
  • Track your expenses and income.
  • Save and build an emergency fund.
  • Diversify your portfolio.
  • Pay attention to your taxes.
  • Streamline your finances with Grey’s multicurrency account.

Grey offers you a unique platform to manage your global earnings seamlessly. You can receive payments in USD, EUR, and GBP and withdraw to local accounts whenever you like. Users enjoy swift transactions, low transaction fees, and competitive conversion rates.

Get started by signing up on Grey today or download the app to manage your global earnings efficiently.

‍

Arrow (up)

Back to top

