


<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/taxes-in-nigeria#article","headline":"Taxation: should Nigerian freelancers pay taxes?","description":"In this article, we’ll be clarifying whether or not freelancers should pay taxes. If yes, what taxes are they liable to pay, and how much","inLanguage":"en","url":"https://grey.co/blog/taxes-in-nigeria","mainEntityOfPage":{"@id":"https://grey.co/blog/taxes-in-nigeria#webpage"},"datePublished":"2022-11-30T17:30:00.151Z","dateModified":"2026-06-15T19:37:08.067Z","author":{"@type":"Person","@id":"https://grey.co/authors/winner#person","name":"Winner Ajibola","url":"https://grey.co/authors/winner"},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/taxes-in-nigeria#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a301c601d9ad575b4cb5b94_6a301c5f67d82cf053c4bee2_taxes-in-nigeria__header-image.webp","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a301c601d9ad575b4cb5b94_6a301c5f67d82cf053c4bee2_taxes-in-nigeria__header-image.webp","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/taxes-in-nigeria#webpage","url":"https://grey.co/blog/taxes-in-nigeria","name":"Taxation: should Nigerian freelancers pay taxes?","description":"In this article, we’ll be clarifying whether or not freelancers should pay taxes. If yes, what taxes are they liable to pay, and how much","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/taxes-in-nigeria#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/taxes-in-nigeria#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/taxes-in-nigeria#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"Taxation: should Nigerian freelancers pay taxes?","item":"https://grey.co/blog/taxes-in-nigeria"}]},{"@context":"https://schema.org","@type":"DefinedTermSet","@id":"https://grey.co/blog/taxes-in-nigeria#terms","name":"Taxation: should Nigerian freelancers pay taxes? glossary","hasDefinedTerm":[{"@type":"DefinedTerm","name":"Personal Income Tax","description":"When you earn an income as an individual freelancer, you're liable to pay a personal income tax in Nigeria. This annual tax payment is payable as long as you reside in Nigeria. The personal income tax is ideal when you're a contractor for a specific client or when you get random projects.","inDefinedTermSet":{"@id":"https://grey.co/blog/taxes-in-nigeria#terms"}},{"@type":"DefinedTerm","name":"Company Income Tax","description":"If you've registered a company under which you operate your freelancing business, you're subject to paying a company income tax. The CIT is any tax you must pay on profits you've generated.","inDefinedTermSet":{"@id":"https://grey.co/blog/taxes-in-nigeria#terms"}},{"@type":"DefinedTerm","name":"Value Added Tax","description":"VAT is a mandatory tax on the supply of goods and services. Since you have to pay for services rendered, this includes developing an app, offering writing services, and more.","inDefinedTermSet":{"@id":"https://grey.co/blog/taxes-in-nigeria#terms"}}]}] </script>

Taxation: should Nigerian freelancers pay taxes?

Winner Ajibola

TABLE OF CONTENT

SHARE THIS POST

With the high unemployment rate in Nigeria, many people have begun freelancing to generate income for their families and personal expenses. It’s also a chance to choose their working hours and be much more independent. 

While full-time employees automatically pay taxes from their annual incomes, there’s been the looming question of whether freelancers should pay taxes or not. Since freelancers don’t have a fixed income, it’s not easy to predict their annual income hence the confusion.

That’s why in this article, we’ll be clarifying whether or not freelancers should pay taxes. If yes, what taxes are they liable to pay, and how much? 

Do You Get Taxed as a Freelancer in Nigeria?

The short answer is Yes. 

Before, relying solely on gigs in Nigeria meant that you could avoid paying taxes. However, since the Personal Income Tax Act amendment in 2011, “any gain or profit from any trade, business, profession or vocation” is subject to tax payments.

This, however, doesn’t include freelancers who earn within the minimum wage tax bracket. So as long as you make less than N30,000 monthly, you’re exempted from paying taxes as a freelancer. 

Why Should You Pay Taxes?

We understand the dilemma that comes with deducting taxes. However, every citizen and resident of Nigeria has to pay taxes for the following reasons; 

  • It’s a source of government revenue - they use these taxes to help maintain infrastructure, offer free education, and so much more
  • Tax evasion is a criminal offense, and you can even be imprisoned for a year or more
  • Failing to pay your taxes can lead to extra fines. This means you might pay 10% extra on the amount you failed to pay.

Types of Taxes You Might be Subject to as a Freelancer

Being a freelancer means deciding who your clients are and the kinds of projects you take on. This could mean you simply take on a few unofficial gigs. However, it could also mean that you’re a small business owner. 

Depending on how you run your freelancing business, you can be subject to any of the following tax brackets;

1. Personal Income Tax: When you earn an income as an individual freelancer, you’re liable to pay a personal income tax in Nigeria. This annual tax payment is payable as long as you reside in Nigeria. The personal income tax is ideal when you’re a contractor for a specific client or when you get random projects.

2. Company Income Tax: If you’ve registered a company under which you operate your freelancing business, you’re subject to paying a company income tax. The CIT is any tax you must pay on profits you’ve generated.

3. Value Added Tax: VAT is a mandatory tax on the supply of goods and services. Since you have to pay for services rendered, this includes developing an app, offering writing services, and more.

How Much Tax Should I Pay on a Freelancing Income?

If you’re ready to start paying your taxes as a resident of Nigeria, here’s how you can do it seamlessly;

Value Added Tax

VAT in Nigeria is at a fixed rate of 7.5%. So let’s say you charge a client N300,000 for designing a website. Your payable VAT will be N22,500.

And while you can choose to pay this tax yourself, you can simply adopt the strategies restaurants, and other FMCGs are using to maximize profit. Markup your rates to include the VAT.

So instead of charging your client N300,000, you charge them N325,500. That way, you still get complete payment for your work. If you’re adopting this popular approach, ensure that you clearly state that your client is paying VAT in the invoice you send. You don’t want to appear fraudulent and send your clients away. 

Recommended Reading: Smart Investment Tips for Freelancers

Personal Income Tax

Before doing your personal income tax calculation, you must first identify your taxable income. A taxable income is how much you earn after you’ve deducted all allowable expenses and deductions. This then determines how much tax you can pay in a year. 

Allowable expenses in this context mean any existing loans, legal expenses, and operational costs like rent. It doesn’t include your capital, penalties, traffic offenses, private expenses, and more. 

Once you deduct these expenses, whatever is left will be taxable income. So let’s say you earn N1, 500,000 in the last year, and after subtracting allowable expenses, your taxable income is N750,000; you’ll pay an annual personal income tax on the latter amount. 

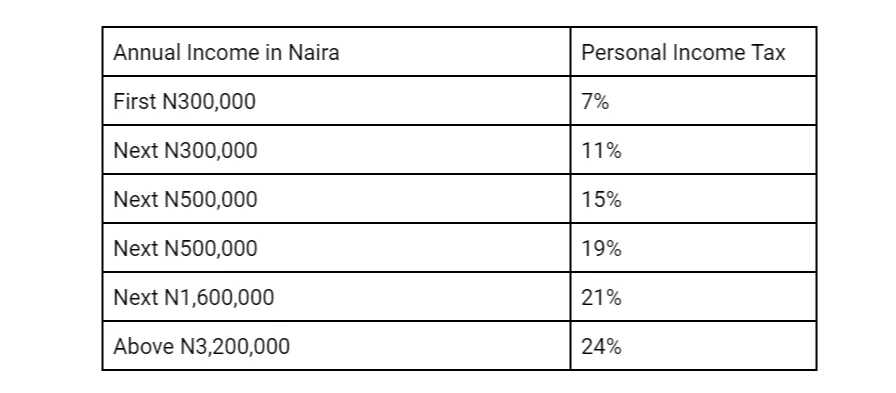
Unfortunately, since personal income taxes aren’t fixed, your tax rates depend on what band you fall on. This table is an example of  personal income tax calculation you should pay based on your annual income;

personal-income-tax

For Company Income Tax

Fortunately, if you have a gross turnover of less than N25,000,000 annually, your company income tax will be 0%. However, if it’s more than this, you’re required to pay 20% on your capital gain as CIT. 

Calculate Your Taxes Using the FIRS Tax Calculator

The federal inland revenue service created a calculator to help taxpayers calculate how much tax they should pay. With this calculator, you can simply select what type of tax you’re trying to pay off and enter other details, like your gross income. You can see how it works here.

Conclusion

As a freelancer, you must pay value-added and personal income taxes. Paying your taxes ensures that the government can adequately provide basic amenities to its citizens. However, this means knowing how much you make as your gross annual income since your taxes will be calculated based on that. 

So start receiving payments with a Grey foreign bank account to receive and track your annual income easily.

Last updated:

October 2, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

What is a domiciliary account? How it works in Nigeria and better alternatives

•

•

2 min read

For a long time, a domiciliary account was the go-to answer for Nigerians who needed to hold or receive foreign currency. If you had reasons to manage USD, GBP, or EUR, you would need to visit a Nigerian bank and complete the rigorous paperwork to open a domiciliary account at a local bank. Despite the transaction delays and restricted access to foreign currency, it seemed like the best thing since sliced bread. Dom accounts were all we had, and we had to make do with them.

Things have now changed. We have better options for managing foreign currency and many Nigerians are looking away from dom accounts. This article explores the alternatives, what each offers, and helps you pick the right one for how you earn and spend.

What is a domiciliary account?

A domiciliary account is a foreign currency account offered by Nigerian commercial banks. It lets you hold USD, GBP, or EUR without immediate conversion to naira, and receive international transfers directly into a local account.

On paper, that sounds like a reasonable way to manage international payments. In practice, the experience rarely matches the description.

Opening a dom account typically requires a visit to a physical branch, a referee who already holds an account at the bank, a utility bill, a passport photograph, and, depending on the bank, an opening deposit of $100 to $200. The process can take days or longer. If you need to start receiving international payments urgently, going the dom account route means you are standing on a long thing.

Then there are the costs. SWIFT transfers to a domiciliary account incur charges on both the sending and receiving ends. The sender's bank charges a fee, intermediary banks take their cut ($15 to $50 is common), and your own bank charges a receiving fee on top. By the time the money settles, you could be looking at $30 to $70 less than what was sent, with no clear line-item breakdown of why. Some banks also impose monthly maintenance fees, withdrawal limits (both cash and transfers), and minimum balance requirements, which add friction to every interaction.

Despite the downsides, dom accounts still make sense for certain situations. If you are receiving large, infrequent wire transfers, or you want to hold a significant USD balance long-term under the regulation and deposit protection of a licensed Nigerian bank, a dom account serves that purpose. But for freelancers, remote workers, and entrepreneurs managing regular international income, the costs and friction add up quickly. That is where the alternatives come in.

Also read: Managing foreign currency earnings as a remote worker in Nigeria

What are the alternatives to dom accounts in Nigeria?

Here are the real options, with enough detail on each to make a decision.

Virtual foreign currency accounts

This is where most Nigerians who have moved away from dom accounts have landed, and the reasons are straightforward.

Platforms like Grey give you real USD, EUR, and GBP account details, including routing numbers, account numbers, and IBANs. These work the same way as foreign bank accounts from the sender's perspective. When your client in New York pays you via ACH using your Grey USD account details, it looks like a standard domestic transfer on their end. There is no SWIFT involved, which means no intermediary bank fees eat into your payment. The funds arrive in your Grey wallet, typically the same day for ACH transfers, and you can see the balance in the app immediately.

From there, you have options. You can hold the dollars in your wallet and convert to naira when the rate works for you, rather than being forced to convert at your bank's rate on the day the transfer arrives. You can spend the dollars directly using a Grey virtual card on subscriptions, software, advertising, or anything else that charges in USD. The card works everywhere Visa is accepted and supports Apple Pay and Google Pay, so you can tap to pay at physical stores in supported regions. Or you can withdraw to your Nigerian bank account when you need naira.

Virtual foreign currency accounts open in minutes, completely online. There is no branch visit, no referee, and no minimum deposit. You see the exchange rate before you confirm a conversion, so you know exactly what you are paying. This is the biggest contrast with dom accounts, where SWIFT fees and conversion costs are often opaque until after the transaction has settled.

Grey is the platform on which this article is published, so take that into account. Other platforms in this category include Geegpay (popular with freelancers, offers USD/GBP/EUR wallets and a virtual dollar card), Eversend (multi-currency wallets across several African countries), and Cleva (US-based USD account with FinCEN registration). Each has a slightly different fee structure, supported currencies, and feature set. Compare them based on the currencies you need, the exchange rate spread, and how quickly you can access your funds.

Best for: Freelancers, remote workers, consultants, and anyone receiving regular international payments from clients or employers. This is the most direct replacement for a dom account for day-to-day use.

Also read: How Nigerian freelancers scale income beyond one platform

Wise

Wise (formerly TransferWise) is one of the most well-known names in international money movement, and many Nigerians use it. You can open a Wise account from Nigeria and get USD, GBP, and EUR account details for receiving payments. Wise's biggest selling point is that it uses the mid-market exchange rate with a transparent fee on top, rather than hiding the cost in the rate spread. For outbound transfers, this is genuinely cheaper than most alternatives.

However, Wise has significant limitations for Nigerian residents that are worth understanding before you rely on it as your primary account.

No physical card in Nigeria. The Wise multi-currency card is not available for Nigerian residents, which limits your spending options to transfers and online payments.

Service disruptions. Wise has periodically adjusted its operations in Nigeria. In 2022, it suspended USD transfers to Nigeria due to infrastructure constraints. These disruptions can be disruptive if Wise is your only receiving option.

Strict anti-crypto policy. Wise prohibits transactions related to cryptocurrency. If the platform detects a transfer to or from a crypto exchange, it may permanently close your account. For Nigerian professionals who also deal in stablecoins, this is a real risk.

Not a bank. Wise is an Electronic Money Institution, not a bank. Your funds are held in safeguarding accounts, not in a bank account in your name. This is a technical distinction, but it matters if you are considering where to hold a large balance in the long term.

Best for: One-off or occasional international transfers where you want the best exchange rate. Less suitable as a primary account for Nigerian residents who need a card, regular access, or crypto flexibility.

Payoneer

Payoneer is an option many Nigerian freelancers encounter first, largely because of its strong integration with major international platforms. Upwork, Fiverr, Amazon, and dozens of other marketplaces offer Payoneer as a payout option. If your income comes primarily through those platforms, Payoneer remains a viable option.

However, Payoneer's conversion rates are not as transparent as those of newer platforms. There are also annual fees for accounts that do not meet certain activity thresholds, relatively high transaction charges compared to fintech alternatives, and an occasionally frustrating customer support experience. The NGN withdrawal rate is not always the best either; you may find better naira conversion rates on platforms like Grey or Geegpay.

Payoneer works best when your income flows through freelancing platforms that have native Payoneer integration. For direct client payments where you control the payment method, a virtual foreign currency account is typically a better option.

Best for: Freelancers receiving payouts from Upwork, Fiverr, Amazon, and other marketplaces that integrate Payoneer natively.

Also read: Top PayPal and Payoneer alternatives for African freelancers

Stablecoins and crypto

Despite the evolving regulatory landscape around crypto in Nigeria, stablecoins remain a practical option for professionals who know how to use them. Some Nigerian freelancers and entrepreneurs receive payments in USDT or USDC because they retain their dollar value, transactions settle in minutes, and fees are low.

The challenge is not in holding stablecoins. It is in the off-ramp: converting USDC or USDT back to naira. Peer-to-peer conversions are popular but carry counterparty risk if the buyer is not trustworthy. Exchange platforms offer more structure but may have their own fees and verification requirements. Some fintech platforms, including Grey, support USDC alongside their multi-currency offering, which bridges the gap between the crypto and traditional banking worlds.

One important note for 2026: under the new Nigeria Tax Act, stablecoin payments are treated as foreign income. If you receive $1,000 in USDC on a given date, that income must be converted to naira at the CBN exchange rate on the date of receipt for tax purposes. The same self-declaration and filing obligations that apply to USD bank transfers apply to crypto income. This does not make stablecoins impractical, but it means you need to track your receipts the same way you would track any other foreign income.

Best for: Crypto-native professionals, developers in the Web3 space, and anyone whose clients or platforms pay in stablecoins. Not a replacement for a bank account or virtual foreign account for most people, but a useful complement.

How the alternatives compare

Here is a side-by-side comparison of the key factors that matter when choosing how to manage foreign currency in Nigeria.
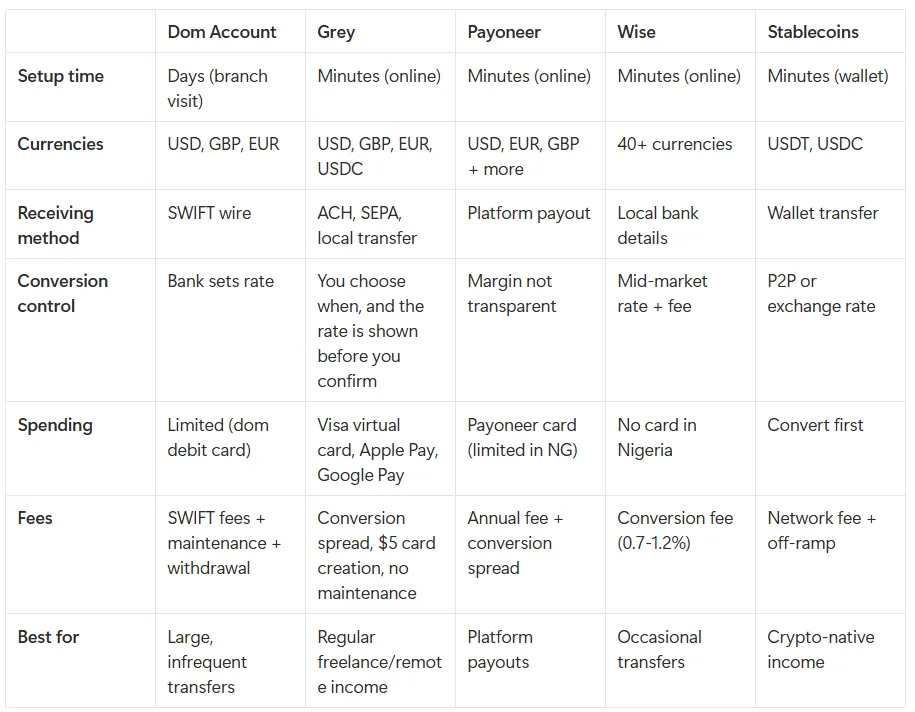
Table comparing domiciliary accounts, Grey, Payoneer, Wise and stablecoins

Which is right for you?

You earn regularly from international clients or an employer. A virtual foreign currency account is your best option. You get foreign bank details to share with clients, control over when you convert, and a card to spend directly in USD. This replaces a dom account for most day-to-day use cases.

Your income comes through Upwork, Fiverr, or Amazon. Start with Payoneer since these platforms integrate it natively. If you find the conversion rates eating into your earnings, consider adding a Grey or similar account and routing future direct client payments there instead.

You need to send a one-off international transfer and want the best rate. Wise is hard to beat on exchange rates for single transactions. Just be aware of its limitations as a full-time financial tool for Nigerian residents.

You receive large, infrequent transfers and want to hold USD for the long term. A dom account at a reputable Nigerian bank still works for this. The setup friction is a one-time cost, and the banking regulation provides a level of institutional protection that fintech platforms do not.

You are paid in crypto or stablecoins. Hold your stablecoins and use a platform that supports USDC conversion to naira when you need to spend locally. Track your receipts for tax purposes under the 2026 NRS rules.

Most Nigerians managing regular international income end up using a combination of methods. A virtual foreign account for the majority of their income, Payoneer for platform payouts, and occasionally a dom account or Wise for specific transactions. The key is to stop defaulting to the dom account for everything, because for regular use, the alternatives are faster, cheaper, and more flexible.

Manage your international income with Grey

Grey gives you USD, EUR, GBP, and USDC account details to receive international payments, a virtual Visa card with Apple Pay and Google Pay support for spending, a built-in invoicing tool for billing clients, and naira withdrawals to your Nigerian bank account. Sign up at grey.co or download the app to get started.

Note: Exchange rates on Grey are variable and include a margin over the mid-market rate. Always review the rate before confirming a conversion.

Frequently asked questions

Is a domiciliary account still worth it in 2026?

For specific use cases, yes. If you receive large wire transfers infrequently, want to hold a significant USD balance under banking regulation, or need the institutional credibility of a commercial bank account, a dom account still serves those purposes. For regular freelance income and everyday USD spending, virtual foreign accounts are more practical.

Can I receive USD in Nigeria without a domiciliary account?

Yes. Virtual foreign currency accounts from platforms like Grey, Geegpay, and Cleva give you USD account details that work as US bank accounts from the sender's perspective. Your client pays via ACH or wire, and the funds are deposited into your wallet without ever touching a Nigerian bank.

What is the cheapest way to receive dollars in Nigeria?

Virtual foreign currency accounts that support ACH transfers are typically the cheapest because they avoid SWIFT intermediary fees entirely. The main cost is the exchange rate spread when you convert to naira, which varies by provider (typically 1% to 3%).

Is Wise or Grey better for Nigerian freelancers?

They serve different needs. Wise offers the mid-market exchange rate, which is excellent for occasional transfers, but it has no card in Nigeria and has periodically disrupted its services in Nigeria. Grey offers a virtual card, Apple Pay/Google Pay, USDC support, and an invoicing tool, making it more practical for Nigerian residents managing regular international income. Many freelancers use both.

Are stablecoins legal in Nigeria?

The regulatory landscape around crypto in Nigeria is evolving. Holding stablecoins is not illegal, and many professionals use them for international payments. Under the 2026 Nigeria Tax Act, stablecoin income is treated as foreign income and must be declared. The main risk is in the off-ramp: converting to naira through unregulated channels can expose you to fraud or compliance issues.

Do I need a Dom account to receive a wire transfer?

Not necessarily. A virtual foreign currency account with SWIFT or wire receiving capability can also receive wire transfers. However, some senders (particularly corporate treasury departments) may prefer to send to a traditional bank account. Check with your payment source whether they accept fintech account details.

Ready to move beyond the dom account? Sign up at grey.co and get your USD, EUR, and GBP account details in minutes.
Grey Business vs Grey personal banking

•

•

2 min read

“Should I be using Grey Business, or is my personal Grey account enough?”

It’s a common question, especially once your income starts growing.

At the beginning, everything feels simple. You get paid and you withdraw your money easily. But as your work evolves, whether that’s taking on more clients, earning from multiple platforms, or starting a company, the way you manage money needs to evolve too.

Grey offers two account types for this exact reason: Grey Personal and Grey Business. They are not better or worse than each other. They are built for different stages of your earning process.

This guide breaks down the differences, including fees, features, and when to switch, so you can choose the right setup without second-guessing.

‍Also read: Receiving foreign income as a solo founder

What is a Grey personal account?

A Grey personal account is designed for individuals who receive and manage international payments.

If you are a freelancer, remote worker, or creator earning from global clients or platforms, this is the account you are expected to use.

With a personal account, you can open USD, GBP, and EUR balances with real banking details. This allows clients to pay you as if they were making a local transfer in their own country. Instead of receiving an expensive international wire, you receive money through local rails like ACH, SEPA, and FPS.

Once the money arrives, you can hold it in foreign currency, convert it when the rate works for you, or withdraw it to your local bank account. You can also spend directly using your Grey virtual card without needing to manually move funds around.

The focus here is simplicity. You are managing your own income, and the account is designed to make that as flexible as possible.

What fees does Grey Personal charge?

Understanding fees is where most people get confused, so here’s how it actually works.

When you receive money through ACH, SEPA, or FPS, Grey charges a 0.8% fee, with a minimum of $2, €2, or £2 and a maximum of $10, €10, or £10. This means larger payments become proportionally cheaper because of the cap.

Currency conversion depends on the currency pair. Some routes are free, while others range from 0.5% to 1%. For certain major pairs, the fee is capped at $6. The important detail is that Grey shows the rate before you confirm, so there are no hidden charges after the fact.

Withdrawals vary depending on the country, but for major currencies like EUR and GBP, the fee is typically 0.5%, with a minimum and maximum cap. Other corridors may use fixed fees instead.

For less common deposit methods like Fedwire, BACS, or CHAPS, fixed fees apply. These are generally used less often, since local rails like ACH or FPS are cheaper.

Read more: Grey charges explained: what every transaction costs

What is Grey Business?

Grey Business is designed for companies rather than individuals.

If you are running a registered business, working under a company name, or managing revenue that belongs to a business entity, this is the account structure you need.

Unlike a personal account, a Grey Business account is built for your company. This means you can receive payments on behalf of the business, manage funds at a company level, and keep financial records properly organised for accounting and compliance.

The functionality goes beyond receiving payments. Grey Business allows you to manage team access, assign roles, and give multiple people control over finances without sharing a single login.

You can also pay contractors globally, send payments in local currencies, and handle bulk payouts by uploading recipient details. This becomes important as soon as you are working with a team or scaling operations.

The goal of Grey Business is not just to receive money, but to structure how your business handles it.

What fees does Grey Business charge?

Grey Business follows the same core pricing model as personal accounts.

Receiving payments still comes with the 0.8% fee capped at $10. Conversion fees follow the same tiered structure, and withdrawals depend on the payout country.

The difference is not in lower fees, but in what the account enables.

With Grey Business, you are paying for structure, team management, and the ability to operate at scale without mixing personal and company finances.

Grey Personal vs Grey Business: what is the difference?

The main difference comes down to ownership.

A personal account is for money that belongs to you as an individual. A business account is for money that belongs to a company.

Everything else builds from that.

Grey Personal is simpler, quicker to set up, and designed for individuals managing their own income. Grey Business requires verification of a registered company but provides tools to manage payments, teams, and operations effectively.

If you are working alone and getting paid for your own work, a personal account is enough. If you are invoicing as a company, hiring people, or managing shared finances, you need a business account.

‍Also read: Can non-residents open a US bank account online in 2026?

When should you use Grey for personal use?

You should use a personal account if you are earning in your own name.

This includes freelancers, remote employees, and creators earning from platforms like YouTube, TikTok, or Upwork. At this stage, your income is still personal, even if it comes from multiple sources.

A personal account keeps things simple.

When should you use Grey Business?

You should use Grey Business when your income is no longer just yours.

If you have registered a company, invoice under a business name, or manage revenue that belongs to a business entity, a personal account is no longer the right structure.

This is especially important if you are paying contractors, working with a team, or preparing financial records for accounting and tax purposes.

Can you have both Grey for personal use and Grey Business?

Yes, and in many cases, this is the best setup.

If you run a company but also earn income personally, keeping both accounts separate helps avoid confusion. Your business transactions stay within the business account, while your personal income remains separate.

This makes accounting cleaner and reduces the risk of mixing funds.

Grey for personal use vs Grey Business: key differences

Feature Grey Personal Grey Business
Who it’s for Individuals (freelancers, creators, remote workers) Registered companies, startups, agencies
Account ownership Personal use Business entity
Currencies supported USD, GBP, EUR, USDC USD, USDC (business-focused)
Receiving payments Yes (ACH, SEPA, FPS) Yes (for business transactions)
Team access No Yes (multi-user access with roles)
Bulk payouts No Yes (CSV uploads supported)
Virtual cards Yes (for personal use) Yes (multiple cards for teams, tools, ads)
Best use case Getting paid individually Managing company finances and scaling operations
Setup process Fast (ID verification) More detailed (business verification required)

So, which Grey account should you choose?

Most people overthink this decision, but it comes down to one simple question:

Who does the money belong to?

If you’re earning as an individual, whether that’s freelancing, remote work, or content creation, a Grey Personal account is the right fit. It keeps things simple and flexible while giving you full access to international payments.

If you’re operating as a registered business, invoicing clients under a company name, or managing team payments, Grey Business is the structure you need. It helps you separate finances properly and handle growth without creating confusion later.

If you’re in between, which is common, you can start with a personal account and move to business when your setup requires it. Many users also keep both, using one for personal income and the other for company operations.

The goal isn’t to pick the most advanced option. It’s to choose the one that fits how you earn today and won’t slow you down as you grow.

Getting started with Grey

Opening a Grey Personal account takes just a few minutes. You can sign up in under 5 minutes, and once your identity is verified, you can usually start receiving payments the same day.

Opening Grey Business takes a bit longer because it involves business verification. You’ll need to submit your company registration and ownership details, and approval typically takes 1 to 3 business days, depending on the documents provided. This ensures your account is set up correctly from the start.

Frequently asked questions

What is the difference between Grey for persona use and Grey Business?

Grey Personal is for individuals receiving and managing their own income, such as freelancers, creators, and remote workers. Grey Business is for registered companies that need to manage business revenue, pay contractors, and give team members access to finances.

The main difference is ownership. Personal accounts are for your money. Business accounts are for company funds.

Can I use a Grey Personal account for business payments?

You can use a personal account while you are freelancing under your own name. However, once you register a company or start invoicing under a business name, it is better to switch to Grey Business.

Using a personal account for business transactions can create confusion with accounting, taxes, and financial tracking.

Does Grey Business have different fees from Grey Personal?

Grey Business follows the same core pricing structure as personal accounts. Receiving fees are typically 0.8% with a cap, and conversion fees depend on the currency pair.

The main difference is not pricing, but functionality. Grey Business adds tools for team access, bulk payments, and structured financial management.

Can I have both a Grey Personal and Grey Business account?

Yes. Many users have both accounts.

This is useful if you have personal income, such as freelance work or creator earnings, and also run a registered business. Keeping them separate makes accounting cleaner and easier to manage.

When should I switch from Grey Personal to Grey Business?

You should consider switching when your income becomes business revenue instead of personal income.

This usually happens when you register a company, start invoicing clients as a business, hire contractors, or need proper financial records for tax and reporting purposes.

What documents are required to open a Grey Business account?

To open a Grey Business account, you will need to provide company registration documents, ownership details, and verification information about the business.

The process is more detailed than a personal account because it involves verifying a legal entity.

Is Grey Personal enough for freelancers and creators?

Yes. For most freelancers, remote workers, and creators, Grey Personal is more than enough.

It allows you to receive international payments, hold foreign currency, convert when needed, and withdraw locally without needing business-level setup.

Can I receive USD, GBP, and EUR with both accounts?

Yes. Both Grey Personal and Grey Business support multi-currency functionality.

Personal accounts focus on individual income, while business accounts structure those same capabilities for company use.

Which Grey account is better?

Neither is better. They are designed for different use cases.

Grey Personal is better for individuals managing their own income. Grey Business is better for companies managing business finances and scaling operations.

Ready to get started?

Open your Grey Personal account to start receiving international payments as an individual, or set up Grey Business if you’re managing company finances and need a more structured setup.

How to send USD to a Nigerian domiciliary account

•

•

2 min read

Most of the information you’ll find online on sending money to Nigeria will most likely focus on naira delivery. But that’s not what you need if the recipient has a domiciliary account and wants to receive USD without converting to naira.

A Nigerian domiciliary account holds foreign currency, typically US dollars, without forcing an immediate conversion. Sending USD to one keeps that option in the recipient’s hands. It’s a decent choice for freelancers holding dollar savings, importers managing USD expenses, or anyone who wants to preserve dollar value rather than convert at a potentially unfavourable rate.

The mechanics of getting USD from a US bank account into a Nigerian domiciliary account are specific. You need to understand the required details, the fees you’ll encounter, and the mistakes that cause transfers to fail or arrive short before you send. For a broader overview of receiving dollar income in Nigeria, see our guide on how to receive US dollars in Nigeria and the options available for opening a Nigerian dollar account.

What is a domiciliary account?

A domiciliary account, also commonly called a dom account, is a bank account held at a Nigerian commercial bank that stores foreign currency without converting it to naira. The Central Bank of Nigeria (CBN) permits individuals and businesses to hold certain foreign currencies in domiciliary accounts at licensed Nigerian banks.

The key distinction from a standard naira savings account is that funds credited to a domiciliary account remain in the foreign currency in which they were credited. The account holder decides when and whether to convert, and at what rate. This matters because the naira has historically depreciated against major currencies, and holding USD can protect against the value erosion of naira conversions.

Domiciliary accounts are the primary mechanism by which Nigerians receive international SWIFT wire transfers in USD. CBN’s foreign exchange regulations require that inbound USD transfers be credited to a domiciliary account or converted to naira at the official rate. If a sender directs a USD wire to a standard naira account, the bank will convert it on arrival. If the recipient wants the money to remain in USD, the wire must be sent to the domiciliary account number, not the naira account number.

Both the naira and domiciliary accounts exist at the same bank for the same person and may look similar. They are different accounts with different account numbers. Confirm the domiciliary account number explicitly with the recipient before initiating the wire.

How to send USD via SWIFT wire: step by step

A SWIFT wire from a US bank to a Nigerian domiciliary account requires specific information, and if you miss any, it can cause delays, returns, or the transfer landing in the wrong account.

Step one: Collect the recipient’s domiciliary account details.

You need all of the following:

  • Recipient’s full legal name, exactly as registered with the Nigerian bank
  • The domiciliary account number (not the naira account number)
  • The bank name and branch address
  • The bank’s SWIFT code

The SWIFT codes for some major Nigerian banks are as follows: Access Bank: ABNGNGLA, GTBank (Guaranty Trust Bank): GTBINGLA, Zenith Bank: ZEIBNGLA, First Bank of Nigeria: FBNINGLA, United Bank for Africa (UBA): UNAFNGLA, Stanbic IBTC Bank: SBICNGLX, Ecobank Nigeria: ECOCNGLA, Fidelity Bank: FBNKNGLA, FCMB (First City Monument Bank): FCMBNGLA.

Always verify the SWIFT code directly with the recipient’s bank before initiating a high-value transfer, as branch-specific codes sometimes differ from the head office code.

Step two: Initiate the wire transfer at your US bank.

Log in to your online banking or visit a branch. Navigate to international wire transfers. Enter the recipient’s details: full name, domiciliary account number, bank name, branch address, and SWIFT code. Specify USD as the transfer currency. Nigeria is a USD-only wire destination at Bank of America; Bank of America requires international wires to Nigeria to be sent in US dollars due to local regulations, and foreign currency transfers are not available to this destination.

Step three: Select your charge instruction.

Depending on your bank, you may be asked whether to use SHA (shared charges) or OUR (sender pays all). Under SHA, correspondent bank fees are deducted from the transfer amount in transit, meaning the recipient receives less than what you send. Under OUR, you pay all correspondent fees upfront, and the recipient receives the full amount. For transfers where the recipient needs a specific USD amount, OUR is the right choice. For transfers where the fee deductions are acceptable, SHA is the standard default.

Step four: The wire routes through the SWIFT network.

Not all US banks have direct correspondent relationships with Nigerian banks. A US-to-Nigeria wire might involve two or three correspondent bank hops due to limited direct banking relationships. Each correspondent bank in the chain processes and forwards the payment, and under SHA, each one can deduct a fee from the transfer amount before forwarding the remainder.

Step five: The money arrives in the domiciliary account.

SWIFT transfers to Nigeria typically take one to three business days. Large transfers may be held for CBN compliance review, which can extend the timeline. Once that is cleared, the USD is credited to the domiciliary account and remains in dollars until the account holder decides to convert or withdraw.

What a SWIFT wire really costs

The posted fee at your US bank is not the full cost of a SWIFT wire to Nigeria. Three fee layers stack on every transfer.

Layer one: Your US bank’s outgoing wire fee
A 2026 NerdWallet survey reported a median outgoing international wire transfer fee of $45, with major US banks charging $35 to $50 per send. Chase charges $40 online for USD wires. Bank of America charges $35 for online transfers. Wells Fargo charges $25 to $45, depending on account type.

Layer two: Correspondent bank deductions in transit
Correspondent banks that relay the payment along the SWIFT chain can each deduct $10 to $30 in fees from the transferred amount before it reaches its destination. On a US-to-Nigeria wire routed through two correspondent banks, that’s $20 to $60 deducted from the transfer amount. Neither you nor the recipient is notified of these deductions in advance.

Layer three: The Nigerian receiving bank’s incoming wire fee
Nigerian banks charge an inbound wire fee on SWIFT receipts. This is typically deducted from the funds upon arrival before they are credited to the domiciliary account.

Here’s what this looks like on real transfers:

$500 transfer $5,000 transfer
US bank outgoing wire fee $40 $40
Correspondent bank deductions (estimated) $30–$50 $30–$50
Nigerian receiving bank fee $10–$15 $10–$15
Total fees $80–$105 $80–$105
As a percentage of transfer 16–21% 1.6–2.1%
USD received in domiciliary account $395–$420 $4,895–$4,920

‍

Also read: Sending USD from Nigeria to the USA: Step-by-step guide

Cheaper alternatives to a SWIFT wire transfer

For smaller or regular payments, the SWIFT route is difficult to justify. Here are the practical alternatives and when each one makes sense.

Multi-currency accounts (the recommended alternative for most senders)

Platforms like Grey provide USD accounts with US routing numbers and account numbers that senders can use to pay as a standard domestic US transfer, with no SWIFT correspondent chain involved.

The sender pays via ACH from their US bank account to a US account number. The money arrives in the recipient’s Grey USD balance without correspondent bank deductions. The recipient then controls when to convert or hold the USD. Multi-currency fintech accounts route payments through their own infrastructure rather than the SWIFT correspondent chain.

Grey’s deposit fee via ACH is 0.8%, capped at $10. On a $500 transfer, the fee is $4. On a $5,000 transfer, the fee is $10. Currency conversion is charged at 1% capped at $6 when the recipient converts to naira.

Stablecoin route

Some senders use USDC to move dollar value to Nigeria. The sender buys USDC on a US-licensed exchange, transfers to the recipient’s wallet address, and the recipient converts to USD or naira via a licensed Nigerian platform. This route avoids SWIFT entirely and can be faster, but requires both parties to be comfortable with crypto infrastructure and introduces volatility risk if either party converts at an unfavourable moment.

When SWIFT is still the right choice

If the recipient holds a domiciliary account and wants to receive funds in dollars without naira conversion, a bank wire is one of the most practical routes. SWIFT confirmations from US banks carry institutional credibility that other receipts may not in certain legal contexts. Nigerian property lawyers, courts, and some financial institutions require a bank-generated wire confirmation to authenticate a large transfer.

For transfers above $5,000 where the fixed fees are a small percentage, for institutional or legal documentation requirements, and for recipients who specifically need a SWIFT credit advice from a Nigerian bank, the traditional wire remains appropriate.

Sending USD to Nigeria with Grey

Grey provides a USD account with real US banking details, including a routing number and an account number issued by Grey's partner bank. Senders in the US use these details to pay as if they were paying any domestic US account. The payment goes out as a standard ACH transfer, bypasses the SWIFT correspondent chain entirely, and arrives in the recipient’s Grey USD balance within one to two business days.

For the recipient, the USD sits in their Grey account and can be held, converted to naira at a rate shown before confirmation, or used directly for USD-denominated expenses via the Grey virtual card.

The practical comparison on a $500 transfer: SWIFT costs $80 to $105 in stacked fees, leaving the recipient with $395 to $420. Grey costs $4 on the deposit, leaving the recipient with $496. On a monthly transfer of $500, that’s a difference of approximately $900 per year.

For senders who regularly send money to Nigeria with Grey, providing the Grey USD account details to the sender once removes all SWIFT complexity.

For those evaluating their full range of options, see our guide on sending money from the US for a broader comparison of methods and costs on the US-to-Nigeria corridor.

Send USD to Nigeria with Grey

Frequently asked questions on how to send USD from the USA to a Nigerian domiciliary account

Can I send USD to a Nigerian domiciliary account from the US?

Yes. A USD SWIFT wire from any US bank to a Nigerian domiciliary account is the standard method for sending dollars that land in Nigeria and remain there as dollars. You need the recipient’s domiciliary account number (not their naira account number), their bank’s SWIFT code, and the bank’s branch address. Alternatively, if the recipient holds a Grey USD account, you can send via ACH as a domestic US transfer, which avoids the SWIFT fee chain entirely.

How much does a SWIFT wire to a Nigerian domiciliary account cost?

Sending USD to a Nigerian domiciliary account via SWIFT can cost up to $60 to $100 in stacked fees across the three layers: the US bank’s outgoing wire fee ($35 to $50), correspondent bank deductions in transit ($10 to $30 per bank), and the Nigerian receiving bank’s incoming wire fee. These fees apply regardless of the transfer amount, which is why SWIFT wires only make financial sense on larger transfers where the fixed cost is a small percentage of the total.

How long does a SWIFT wire to Nigeria take?

SWIFT transfers to Nigeria typically take one to three business days after the US bank initiates the transfer. Large transfers may be held for CBN compliance review, which can extend the timeline. Transfers initiated late in the US banking day or on Fridays may not begin processing until the following business day. Grey ACH transfers to a US account number typically arrive in one to two business days.

Is there a cheaper way to get USD into Nigeria without using SWIFT?

Yes. A USD account through a multi-currency platform like Grey receives ACH transfers from US senders at a fraction of the cost of SWIFT transfers. Grey’s deposit fee is 0.8%, capped at $10, compared to $60-$100 in SWIFT fees for the same transfer. The tradeoff is that the USD lands in a Grey account rather than a Nigerian bank domiciliary account. For recipients who need SWIFT credit advice from a Nigerian bank for legal or institutional purposes, traditional wire transfers remain necessary. For everyday dollar receipts, the ACH route through Grey is significantly cheaper.

Grey charges fees on deposits, conversions, and withdrawals. Deposits via ACH incur a 0.8% fee (minimum $2, maximum $10). Currency conversions are charged at 1%, capped at $6. Withdrawal fees vary by currency: ₦35 for NGN. Exchange rates are variable and include a margin over the mid-market rate. Always review fees and the rate before confirming a transaction.

How to convert and send USD to Ugandan Shillings (UGX) online

•

•

2 min read

Managing cross-border payments doesn’t have to be complicated. Whether you’re a freelancer, remote worker, or supporting family in Uganda, converting USD to Ugandan Shilling (UGX) can be quick, secure, and hassle-free with Grey.

This guide shows you how to easily convert and send USD to UGX online, highlighting key benefits, costs, and tips for seamless transactions.

Why use Grey to convert and send USD to UGX?

Grey is a digital banking platform designed for global citizens who want to manage multiple currencies easily. Here’s why Grey is an excellent choice for converting and sending USD to UGX:

  • Competitive exchange rates: Grey offers real-time rates to ensure you get the most value when converting USD to UGX.
  • Low fees: Avoid the high conversion and transfer fees associated with traditional banks.
  • Quick transfers: Funds are processed quickly, ensuring your recipients get the money without delays.
  • User-friendly platform: Grey’s app and website are designed to make international transactions simple and accessible for everyone.

Exchange rates fluctuate for various reasons, so we’ve designed a handy, real time currency converter for you.

Also read: How to convert and send USD with Grey

How to convert and send USD to UGX with Grey

1. Create your Grey account

First, sign up for a free Grey account via the website or app, available on iOS and Android. Registration is straightforward and requires you to:

  • Provide basic personal information.
  • Verify your identity by uploading the required documents.
  • Set up your virtual wallet for multiple currencies, including USD.

2. Add USD to your Grey account

Once your account is active, deposit USD into your Grey wallet. You can do this in several ways:

  • Bank transfer: Link your USD bank account and transfer funds directly.
  • Freelance platforms: Receive payments from platforms like Upwork or Fiverr directly into your Grey USD wallet.
  • Wire transfers: Accept payments from international clients or businesses.

With USD in your account, you can convert it into UGX.

3. Convert USD to Ugandan Shilling with Grey

Follow these steps to convert your USD to UGX:

  1. Log into your account: Open the Grey app or website and sign in.
  2. Navigate to currency exchange: Select the “Convert” option from the dashboard.
  3. Choose currencies: Select USD as the source currency and UGX as the destination currency.
  4. Enter the amount: Specify the amount of USD you want to convert.
  5. Confirm the transaction: Review the exchange rate, fees, and total amount in UGX, then click “Convert.” The converted funds will appear in your UGX wallet instantly.

4. Send UGX to your recipient

Once your USD is converted to UGX, it’s time to transfer the funds to your recipient in Uganda. Here’s how:

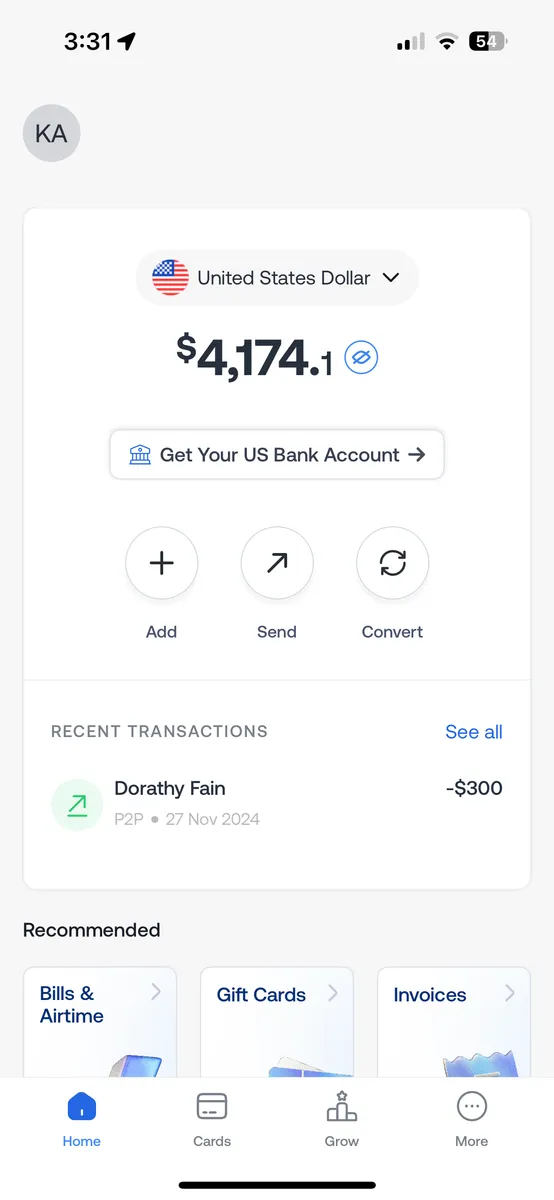
1. Navigate to the Send Money section: Choose the “Send” option in the Grey app.

676ec441190ed0b08ba00d26 676ebd9e62b40f1197672db7 send us dollars grey 6

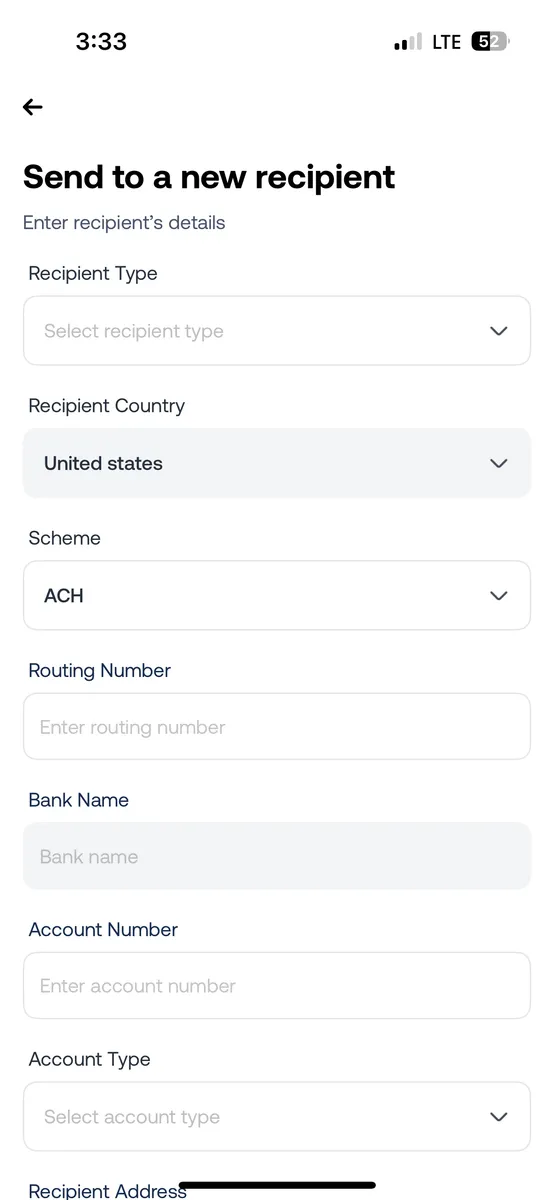
2. Enter the recipient’s details: Add the recipient’s bank account or wallet information. You can also send funds to another Grey user.

676ec442190ed0b08ba00d42 676ebd4d245072006253a99c send us dollars grey 4

3. Choose the amount to send: Enter the amount in USD or your currency (e.g., EUR).

676ec442190ed0b08ba00d3f 676ec3b94c9821344d4d5d63 IMG 0368

4. Review fees and exchange rates: Grey will estimate the fees and exchange rates so you know exactly how much the recipient will receive.

676ec442190ed0b08ba00d79 676ec3c426d44aa2a43d7fc8 IMG 0370

5. Complete the transaction: Confirm the details and authorise the payment. The recipient typically receives the funds in minutes to a few hours, depending on the payment method.

676ec442190ed0b08ba00d45 676ec3d1138ab1eb14571c89 IMG 0371

‍

‍You may also like: How to convert and send USD to TZS online

Key tips for converting and sending USD to UGX

  1. Monitor exchange rates: Keep an eye on the exchange rate to convert your funds at the best possible time.
  2. Double-check recipient details: Ensure the accuracy of bank account or mobile wallet information to avoid delays.
  3. Use Grey’s multi-currency wallets: Store USD and UGX in your Grey account to avoid frequent conversions and save on fees.
  4. Track your transactions: Grey offers a transaction history feature to easily track conversions and transfers.

Why Grey is the best option for USD to UGX transfers

Grey stands out as a reliable and cost-effective platform for handling international payments. Here’s why it’s a top choice:

  • Speed: Transfers are processed faster than most traditional banks, so your recipients get their money quickly.
  • Savings: With low fees and competitive exchange rates, you keep more of your hard-earned money.
  • Flexibility: Manage multiple currencies from one account and send funds anytime, anywhere.
  • Security: Grey prioritises secure transactions, giving you peace of mind.

Take control of your cross-border payments with Grey

Converting and sending USD to Ugandan Shilling has never been easier. Whether supporting family, paying vendors, or managing personal finances, Grey’s seamless platform saves you time, money, and effort.

Ready to simplify your financial transactions? Sign up with Grey today and enjoy a hassle-free way to convert and send USD to UGX online.

‍

How to start a dropshipping business in Nigeria

•

•

2 min read

Dropshipping has come a long way in the African market, and that’s because it is a business model that allows entrepreneurs to sell products without holding inventory. The way it works is, whenever a customer orders a product, as the business owner, you’ll buy that item from a third-party supplier, who will ship the product directly to the customer. 

This business model has become increasingly popular because it eliminates the need for upfront inventory costs, storage space, and shipping logistics. 

As a result, it has gained traction in the Nigerian market in recent years as it is a cost-effective way for entrepreneurs to start an online business without needing physical inventory. 

Benefits of dropshipping in Nigeria

There are several benefits of dropshipping in Nigeria; some of them include:

  1. Low Overhead Costs: Dropshipping requires minimal inventory investment so that you can start your business with little or no budget.
  2. Flexibility: Dropshipping allows you to work from anywhere and at any time, as long as you have an internet connection.
  3. Wide Range of Products: With drop shipping, you can offer a wide range of products without worrying about inventory management. Sell whatever you want from multiple suppliers.
  4. Minimal Risk: Dropshipping is less risky than traditional retail because you don’t have to hold inventory.

Seven steps on how to start a dropshipping business in Nigeria

Now that we know what dropshipping is and understand its benefits, how do you start it in Nigeria? 

Step 1: Choose your niche and products

The first step in starting a dropshipping business is to choose a niche and the products you want to sell. A niche is a specific area of focus within a larger market. Choosing a niche you are interested in and knowledgeable about is essential. It will make it easier to identify the best products to sell, and you can create marketing plans that’ll resonate with your target audience.

Once you’ve chosen your niche, research the best products to sell. Look for products that are in demand, have a high-profit margin, and are accessible to source from reliable suppliers. You can use tools like Google Trends, Amazon Bestsellers, and Oberlo to help you find popular products.

Step 2: Research suppliers

There are various online suppliers, depending on what you want to sell. However, your dropshipping business’s success depends on finding reliable suppliers who can provide quality products at competitive prices. 

When researching suppliers, look for those who have a good reputation, offer fast shipping, and have a wide range of products.

There are many dropshipping suppliers that you can use, including AliExpress, SaleHoo, and many more. You can also consider using local suppliers in Nigeria to reduce shipping costs and improve delivery times.

Step 3: Create your online store

Now that you have chosen your niche, products and a reliable supplier, it’s time to create your online store or decide on the platform you’d use for sales. 

You can use e-commerce platforms like Shopify, WooCommerce, or WordPress to set up your store or decide to sell on platforms like Instagram, Snapchat, and WhatsApp. 

However, while creating your online store, choose names or domain names that are easy to remember. Then design your website and add your products. Ensure your website is easy to navigate, visually appealing, and mobile-friendly.

Step 4: Research delivery options

Your dropshipping success or failure depends mainly on delivery, especially in the Nigerian market. So therefore, to run a successful dropshipping business, you must either deal with reputable delivery agents or partner with your hosting platforms, such as Shopify, to set up delivery. 

Step 5: Set up a payment platform

This should be pretty straightforward. However, Shopify provides payment apps and getaways to set up your payment processor. Also, since many of your transactions with supplies will involve foreign currency, you can set up your payments with  Grey.

With Grey, you can send money to any foreign account, including your supplier’s account, without any stress or hidden fees. 

You can also use it to receive payments from your earnings if you’re dropshipping with partners like Amazon FBA.

Step 6: Market your business

Now that your online store is running, it’s time to start marketing your business. There are many ways to promote your dropshipping business, including;

  • Social media marketing: Use platforms like Facebook, Instagram, and Twitter to reach your target audience and promote your products.
  • Content marketing: Create blog posts, videos, and other content that educates your audience about your products and industry.
  • Influencer marketing: Partner with influencers in your niche to promote your products to their followers.
  • Search engine optimization: Optimize your website for search engines to improve your rankings and drive more traffic.

Step 7: Manage your business

As your dropshipping business grows, it’s essential to manage it effectively. This includes tracking inventory, promptly fulfilling orders, and providing excellent customer service.

You’ll also need to continually analyze your business metrics, such as your conversion rate, customer acquisition cost, and lifetime value. This information will help you identify areas where you can improve your business and make data-driven decisions.

In conclusion, dropshipping is a viable business model for entrepreneurs looking to start an online business in Nigeria. 

However, starting a dropshipping business requires research, planning, and execution. When it comes to sending and receiving funds, as that is one the major challenge faced by Nigerians, it is important to sign up for reliable platforms makes it easier to transact globally and that where Grey comes in.

Grey allows you to open a foreign currency account to receive payments from anywhere. Get a free account today to make international payments or convert foreign currencies to Nigeria Naira.

‍

How to convert and send US dollars (USD) with Grey

•

•

2 min read

As a digital nomad your finances should work as flexibly as you do. With Grey, converting and sending USD becomes effortless, no matter where you are. From managing payments with US clients to handling multiple income streams, Grey makes accessing and transferring your funds quick, affordable, and hassle-free.

In this guide, we’ll walk you through effortlessly converting and sending US dollars with Grey, revealing how to maximise savings, cut through complexity, and make global financial management a breeze.

Why Grey is perfect for sending and converting US dollars

Managing your finances can be challenging, especially when working with clients or employers in different currencies. Whether you’re based in Asia, Europe, or anywhere else, having a platform that supports multi-currency accounts and provides transparent exchange rates is essential.

Grey offers several advantages for digital nomads and remote workers:

  • Multi-currency accounts: Grey lets you hold and manage funds in multiple currencies, including USD, EUR, GBP, and more, making it easy to convert and send money.
  • Low fees and competitive rates: Grey provides low conversion fees and competitive exchange rates, ensuring that more of your earnings stay with you.
  • Global accessibility: Whether in Bali, Mexico, or Spain, Grey’s mobile app allows you to manage your finances anywhere with an internet connection.
  • Seamless transfers: Sending USD or any other currency is fast and simple. Grey allows instant transfers to various bank accounts and wallets globally.
  • Easy account integration: You can link your Grey account to platforms like Amazon, freelance job sites, and other payment systems, simplifying the process of receiving and sending payments.

Exchange rates often fluctuate for several reasons, so we’ve created a special currency converter for you.

The benefits of converting and sending USD with Grey

Before diving into the conversion and sending process, let’s take a moment to explore why Grey is a great option for converting USD into local currencies or sending it to other accounts.

  1. Competitive exchange rates

Grey offers competitive exchange rates compared to traditional banks and other payment platforms. While rates vary based on market conditions, Grey provides real-time rates with a transparent view of conversion fees.

  1. Low conversion fees

Grey’s conversion fees are designed to be transparent and affordable.

  1. Efficient cross-border transfers

Fast and secure transfers are key when working internationally. Grey enables you to send USD to international accounts almost instantly. This feature is particularly useful for remote workers who must pay international invoices or send money to family members in other countries.

Grey also allows for quick transfers between different currency accounts, so if you need to convert USD into GBP, EUR, or any other supported currency, you can do so easily.

  1. Global accessibility

Since Grey is a fully digital platform, you can access it from anywhere in the world. This is particularly advantageous for digital nomads who frequently travel or live abroad, as it provides a consistent and reliable way to manage your finances regardless of location.

Step-by-step guide: How to convert and send USD with Grey

Now that you understand the benefits of using Grey, let’s walk through the detailed process of converting USD to another currency and sending it to a recipient, whether for personal or business reasons.

Step 1: Sign up for a Grey account

If you haven’t already, the first step is to create an account with Grey. Visit Grey’s website or download the app from the App Store or Google Play. The sign-up process is straightforward and typically takes just a few minutes.

To start, you’ll need to provide personal details, verify your identity, and set up your account.

Step 2: Deposit USD into your Grey account

Once you’ve created your account, you can deposit USD into your Grey account. You can do this through several methods:

  • Bank transfer: Link your bank account to Grey and deposit funds directly into your USD account.
  • Payment platforms: If you receive payments from platforms like PayPal, Stripe, or other freelance networks, you can transfer your earnings directly to your Grey account.
  • Wire transfer: If you’re working with clients or employers who prefer wire transfers, you can provide them with your Grey account details so they can receive USD payments.

You can begin the conversion process after depositing USD into your Grey account.

Step 3: Convert USD to another currency

To convert USD into another currency, follow these steps:

  1. Open the Grey app: Log into your Grey account and navigate to the currency conversion section.
  2. Select the currencies: Choose USD as the source currency and select the destination currency (e.g., EUR, GBP, ZAR).
  3. Check the exchange rate: Grey will display the current exchange rate for the conversion, along with the conversion fees.
  4. Confirm the conversion: Once you’re satisfied with the rate and fees, confirm the transaction. Your funds will be converted and reflected in your Grey account in the new currency.

Step 4: Send USD or converted funds to a recipient

To send funds to another individual or account, you’ll need to:

1. Navigate to the Send Money section: Choose the “Send” option in the Grey app.

__wf_reserved_inherit

2. Enter the recipient’s details: Add the recipient’s bank account or wallet information. You can also send funds to another Grey user.

__wf_reserved_inherit

3. Choose the amount to send: Enter the amount in USD or your currency (e.g., EUR).

__wf_reserved_inherit

4. Review fees and exchange rates: Grey will estimate the fees and exchange rates so you know exactly how much the recipient will receive.

__wf_reserved_inherit

5. Complete the transaction: Confirm the details and authorise the payment. The recipient typically receives the funds in minutes to a few hours, depending on the payment method.

__wf_reserved_inherit

Convert and send USD: Key tips for remote workers

  1. Minimise fees: Always review Grey’s exchange rates and conversion fees before confirming any transaction. While Grey offers competitive rates, you may still want to plan your conversions to avoid unnecessary fees, especially if you’re sending large sums.
  2. Use local currency accounts: If you’re working in a country with a stable currency, consider holding a local currency account to avoid frequent conversions and fees.
  3. Monitor exchange rates: Grey updates its exchange rates in real time. If you’re converting large sums, it may be worth monitoring rates for a few days to ensure you get the best deal.
  4. Use Grey’s app for convenience: Grey’s mobile app allows you to convert and send USD or other currencies from anywhere in the world, which is a huge advantage for digital nomads who need to manage their finances on the go. Download Grey now and get started.

Simplify converting and sending USD with Grey

Converting and sending USD with Grey is an efficient and cost-effective way for remote workers and digital nomads to manage their finances. With competitive exchange rates, low fees, and the convenience of a fully digital platform, Grey provides a seamless solution for handling cross-border transactions.

Ready to start using Grey? Sign up today and take control of your global finances.

‍

Arrow (up)

Back to top