<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/joey-akan-journey-in-nigerian-music-afrobeats-intelligence#article","headline":"Joey Akan: Journey in Nigerian music & Afrobeats Intelligence.","description":"Find out the insights, challenges and opportunities shared by the Nigerian music journalist, Joey Akan, on the world of Afrobeats in this episode of our LGB Podcast","inLanguage":"en","url":"https://grey.co/blog/joey-akan-journey-in-nigerian-music-afrobeats-intelligence","mainEntityOfPage":{"@id":"https://grey.co/blog/joey-akan-journey-in-nigerian-music-afrobeats-intelligence#webpage"},"datePublished":"2024-01-12T12:21:55.456Z","dateModified":"2026-06-15T15:32:48.023Z","author":{"@type":"Person","@id":"https://grey.co/authors/toluwani-omotesho#person","name":"Toluwani Omotesho","url":"https://grey.co/authors/toluwani-omotesho"},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/joey-akan-journey-in-nigerian-music-afrobeats-intelligence#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a301b1f51e9fcfea6cac131_6a301b1e4555d9e22be68ede_joey-akan-journey-in-nigerian-music-afrobeats-intelligence__header-image.webp","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a301b1f51e9fcfea6cac131_6a301b1e4555d9e22be68ede_joey-akan-journey-in-nigerian-music-afrobeats-intelligence__header-image.webp","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/joey-akan-journey-in-nigerian-music-afrobeats-intelligence#webpage","url":"https://grey.co/blog/joey-akan-journey-in-nigerian-music-afrobeats-intelligence","name":"Joey Akan: Journey in Nigerian music & Afrobeats Intelligence.","description":"Find out the insights, challenges and opportunities shared by the Nigerian music journalist, Joey Akan, on the world of Afrobeats in this episode of our LGB Podcast","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/joey-akan-journey-in-nigerian-music-afrobeats-intelligence#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/joey-akan-journey-in-nigerian-music-afrobeats-intelligence#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/joey-akan-journey-in-nigerian-music-afrobeats-intelligence#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"Joey Akan: Journey in Nigerian music & Afrobeats Intelligence.","item":"https://grey.co/blog/joey-akan-journey-in-nigerian-music-afrobeats-intelligence"}]}] </script>

Joey Akan: Journey in Nigerian music & Afrobeats Intelligence.

Toluwani Omotesho

TABLE OF CONTENT

SHARE THIS POST

With the current wave of “Afrobeats to the world,” we’re seeing Nigerian music take the world by storm.

In our recent Limitless podcast, we spoke with Joey Akan, an award-winning journalist, writer, member of the GRAMMY Recording Academy, and A&R and media consultant. He talks about how his passion for music shaped his career as a music journalist and shares fresh insights into the complexities of business in the Nigerian music industry.

Journey Before Journalism

You’re well known as a music person, but let’s talk about your journey before journalism and getting into music. What was it like?

It wasn’t a very great journey. It involved sleeping in markets, begging for food from restaurants, and foraging through refuse dumps to get books to read. But this flipped in 2013 when I moved to Lagos to build a life after graduating. Ten years down the road, and I’m way different from that person.

Before journalism, I was just a kid with a prayer, and journalism helped me understand the world a lot more. I was drawn to music because it was this beauty that sprayed my brain with the right chemicals. I’ve always been attracted to the mastery of sound and with journalism, I was able to   combine writing, which I enjoyed, and music.

What exactly is it about music that does it for you?

There’s something special about sound and what it does to you. I think of it in two ways. First, the intrinsic value in itself. The mastery of creativity and manipulating sound waves to create beauty. But, I also think about the utility of it, i.e., what it does for me.

There’s also the other part where I use music as a marker for time. So, different periods of my life have been soundtracked by different records and albums. The first time I backpacked out of the city for a West African tour, I listened to The Life of Pablo by Kanye West. During the #EndSars protests, Wizkid’s Made in Lagos soundtracked that period of my existence, and currently, it’s OdumoduBlvck. So, apart from storing time, it also holds memories for you; you hear a song, and you’re hit with a wave of nostalgia. When you combine all these things, the marvel creating music itself and the benefits that it gives, what’s there not to love? So, for me, it’s not a hustle. Falling into the deep end of sound has never been a hustle for me, and even writing is just beautiful, so I feel privileged.

How did you go from studying biochemistry to this?

Biochemistry? I needed a degree, and people were paying for it. But looking back, I also needed the structure, the learning, community, and friendships. In school, you can test yourself and follow the rules. Your brain learns many things, and along the way, you pick up things you fall in love with. You’re able to get so much knowledge that it makes you a richer person. I worked at a hospital for a while after graduating but didn’t like it; there was too much sadness there, so I followed my joy.

Have you considered doing more than you currently do in music?

I do more; I just don’t flaunt it. I’ve worked at Universal and consulted for multiple record labels, which I’m still doing. I’ll probably go in-house officially at some point; I also scout and work with artists. I do a lot of this currently. It’s my job and what I do for a living.

Do you have other interests?

Yes, I have multiple interests. My job is to intellectualize music or add literature to sound, but I also do other things like making visuals and hosting a podcast. This year, I’ll be doing events, and I’m also building an agency.

That’s great. What would you say are your top 5 Afrobeats songs from 2023?

Number one should be Omah Lay’s “Reason,” OdumoduBlvck’s “Commend,” Rema’s “DND,” and then BNXN’s “Pidgin & English.” You could also throw in Davido’s “Feel” because I think it’s the most complete song of 2023. Everything was perfect. Then lastly, Ayra Starr’s “Rhythm & Blues”.

Afrobeats Intelligence

Coming back to journalism, tell me about Afrobeats Intelligence.

So, Afrobeats Intelligence was something I created as a reaction to walls closing in on me in 2020. Editorial budgets were drying up around America, Europe, and the UK. I wasn’t getting as many commissions locally because I wasn’t the most loved person in the industry. I used to be a troublemaker, and those things come at a cost; they take their toll. People started retreating from me. At that point, I decided to create my own thing, and that’s how Afrobeats Intelligence started.

It started as a newsletter that has grown into tens of thousands of subscribers. We’ve expanded to multimedia, producing podcasts and videos; we also executed our first live event last year in partnership with Spotify. We did a live recording this year; we’ll do four, one every quarter. What makes me happy about this is that it’s a work of passion, and I’m grateful it’s working.

Did you envision how far you’d go, especially with Afrobeats Intelligence?

I just wanted to create my thing. I’ve never been one to make long-term plans. So, when I started, it was just a newsletter. But, I kept my eyes and ears open, observed everything, and was open to change despite fear. So I didn’t envisage anything. I just want to do the best work with all my resources, and I’m grateful that God continues to bless and support it.

That’s inspiring. Coming to the Grammys. How did you become a member of the recording academy, and how does it feel?

It started with me being in many meetings when the GRAMMY category for Africa was created. Then, earlier last year, they called and asked if I wanted to be a member and wrote a recommendation letter — you need two strong recommendations from people in the music industry. I applied and was accepted. These things are mostly nice to have; it’s an excellent opportunity to shape the narrative of global music, especially now that our music has such a significant impact on the world. It’s good to have someone in the room speaking for our artists and I’m happy I have the rare privilege of participating in this.

Love it. So, as an A&R, you’ve seen and worked with many artists. What do you think of the saying, “If you never reach Lagos, you never blow”?

I think it holds a lot of truth. I’m grateful now that we’re trying to be more decentralized, with a few artists trying to be exceptions. But at the crux of it, Nigeria doesn’t have a music infrastructure. And the tiny infrastructure that does exist is in Lagos; the machinery, companies, and execs are all here. The pipeline is here. Lagos has the most vibrant fans; you can see how they relate with the music. So why would you not want to give yourself a shot at greatness by moving to that spot? If you’re striving for excellence, you want to be at the top of your game at the highest levels of it, and Lagos affords you that opportunity.

What can you tell me about streaming farms?

So, for artists, music is about invention. You invent a new sound or a new style of sound. You create the visuals and aesthetics that come with this sound. You contrive events to promote it and call it marketing. However, the only thing you can’t event or could not previously event is feedback. But now, with technology, it’s getting easier to invent feedback, and that’s what stream farming does. It makes everyone think your music is good. It gives you great numbers and you use those numbers for marketing. But at the end of it all, it doesn’t help. It’s a crime against yourself; it ruins your metrics and numbers and is deceptive to the public.

Legacy in the Music Ecosystem.

Wow. Let’s talk about your legacy for a bit. What kind of impact do you think your work has on the music ecosystem in Africa?

On the journalistic side, people interested in being music journalists can see that creating value from something as inconsequential as writing or talking about music is possible. They can see that it’s possible to make a career out of it if you do it right. I don’t know how long this will last, but I’ve had a very good run and am grateful for it.

From the music aspect, it’s primarily teaching. I’m allowing a generation of artists and would-be artists to learn about the industry from the right sources. So, a kid in Uyo who dreams of being an artist can learn about the creative aspect and the business side of the music industry.

What would you like to be remembered for?

I’d like to be remembered for doing my own thing, and somehow, the world found value in it and got impacted positively. And if that impact is my legacy, I’m happy for it.

Last updated:

October 2, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

Send Canadian dollars with Grey

•

•

2 min read

Everything we do at Grey is aimed at making it easier for you to make global payments.

We’re excited to announce that Grey now supports Canadian dollars (CAD) payments, which means you can send money to Canada directly from your Grey account via Interac e-Transfer.

You can pay freelancers, send money to family, or make cross-border payments to Canadian businesses right from your phone.

What exactly does this mean for you?

Send money to Canada easily‍

Because we’ve integrated with Interac e-Transfer, you can send money directly to any Canadian bank account. You’ll only pay a flat $3 fee, regardless of how much you’re sending.

Expand your global operations with less friction

‍CAD joins our growing list of supported currencies, giving you more flexibility when operating across borders.

No additional setup required

‍It’s the same Grey account you already have. Sending CAD works exactly like sending any other currency through Grey. There’s no confusion about exchange rates and no need for the recipients to sign up for anything.

How does sending CAD work with Grey?

We’ve kept things simple. Here’s how to send Canadian Dollars using Grey:

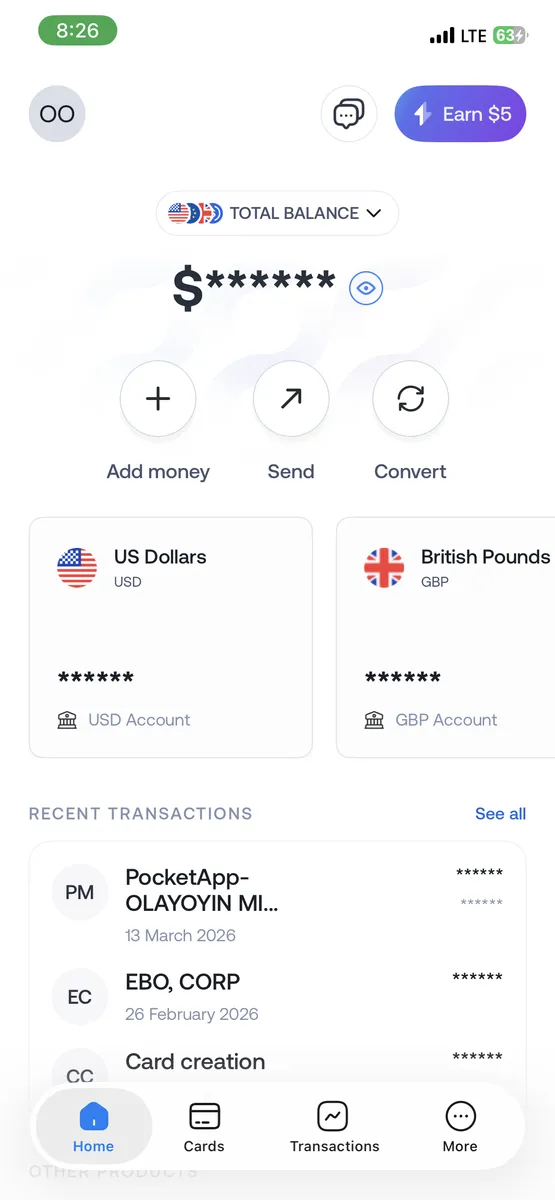
  1. Log in to your Grey account.
    ‍
  2. Click “Send”.
Send Canadian dollars with Grey

‍

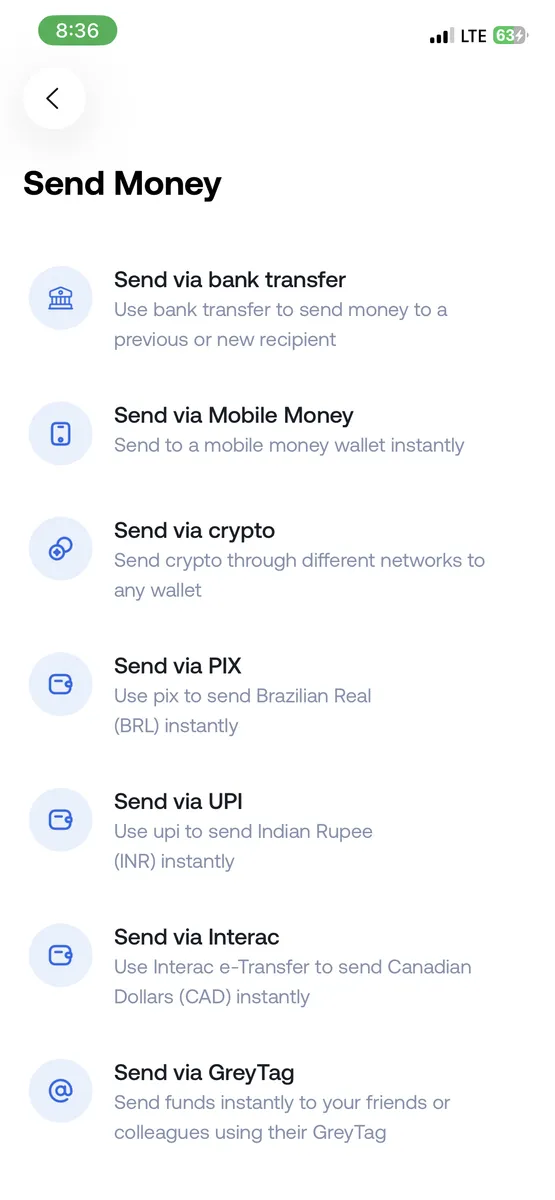
2. On the “Send Money” tab, select “Send via Interac”.

Send Canadian dollars with Grey

‍

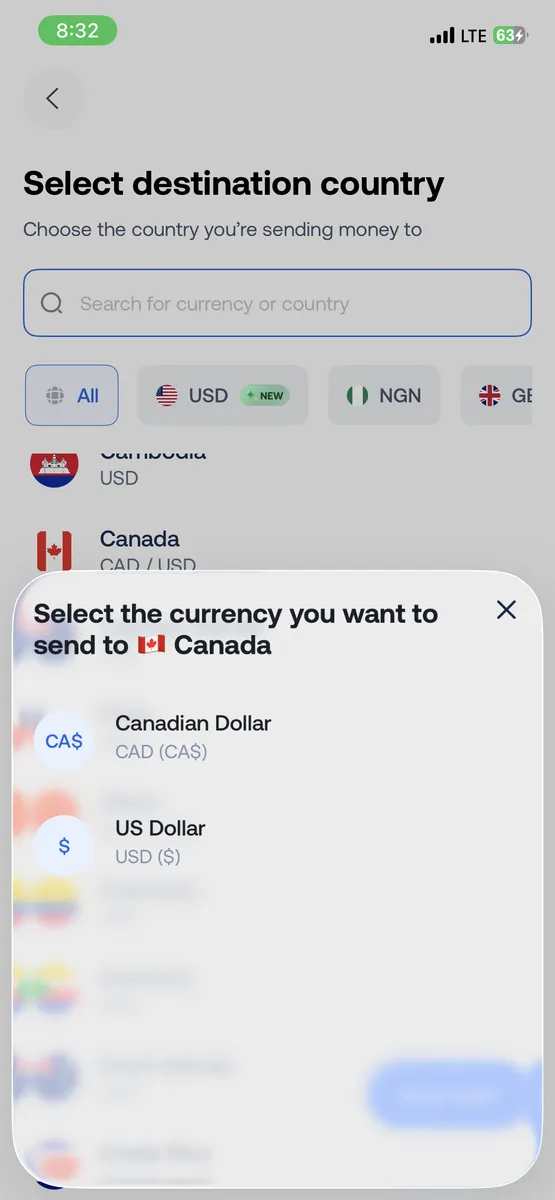
3. Select Canada as the destination and choose CAD as the currency.

Send Canadian dollars with Grey

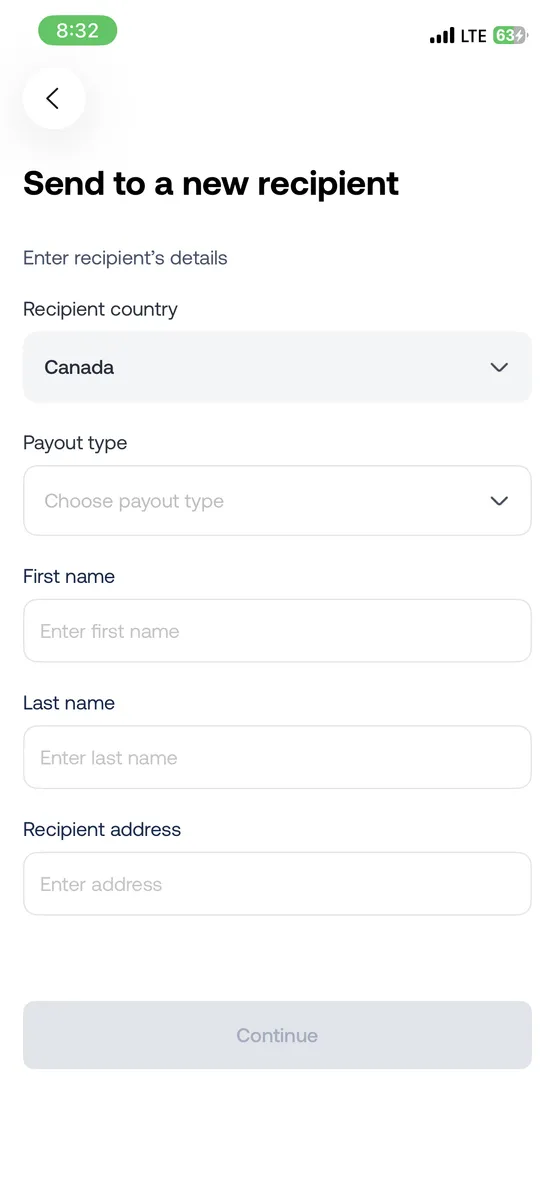
4. Enter the recipient’s details and confirm the transfer.

Send Canadian dollars with Grey

Enjoy global payments with Grey

At Grey, our mission is to make globalisation work for everyone. Supporting payments in Canadian Dollars takes us closer towards achieving that goal.

We want more freelancers, businesses, and remote workers to operate internationally without friction.

More currencies, more countries, and more ways to manage money across borders, that’s where we’re headed.

Open a free Grey account today, or download the app to get started.

‍

Open a USD business account without a US address

•

•

2 min read

The dream of any business with international ambitions is landing its first major client. It’s fulfilling and justifies all the hard work you’ve put in. That email that reads “We’ll need your US bank account details for ACH transfer” just leaves you smiling.

If you don’t have US bank account details because you’re not operating from the US, the easy solution is for the client to send an international wire transfer. Unfortunately, this can be expensive and delay payments.

Ideally, you start researching. Many articles say you need a US business entity, a physical US address, and an in-person visit to a US bank branch. The cheapest path involves spending $2,000 to form a Delaware LLC, hiring a registered agent, obtaining an EIN, and then somehow convincing a US bank to open an account for a foreign-operated business. The entire process could take months.

There’s a gap between “I need US banking details to get paid” and “I need to incorporate in Delaware and maintain a US legal entity.” Many businesses fall directly into that gap. In this article, I explain how USD business accounts actually work, why the traditional path doesn’t make sense for most non-US businesses, and how modern financial infrastructure lets you access US banking capabilities without US incorporation, US addresses, or US travel.

What is a USD business account?

Confusion around terminology causes many businesses to pursue the wrong solutions.

Domiciliary accounts are USD-denominated accounts offered by banks in your local country. These accounts let you hold US dollars, receive international wire transfers, and store foreign currency.

They, however, don’t provide you with US routing numbers, US account numbers, or integration with the US payment system. You cannot receive ACH payments into a domiciliary account. US clients cannot pay you the way they pay domestic vendors. The account holds USD, but it functions outside the US banking infrastructure.

Foreign currency accounts are essentially the same as domiciliary accounts, just named differently in different countries. They have the same capabilities and the same limitations.

US bank accounts have actual US routing numbers and account numbers, integrated into the US banking system. They can receive ACH transfers and domestic US wire transfers, and they can integrate with US payment platforms. When someone asks for your “US bank account details,” this is what they mean: a routing number (9 digits identifying the bank), an account number (unique to your account), the bank’s name and address, and your account holder’s name.

Also read: Alternatives to domiciliary accounts in Nigeria

Why businesses outside the US need USD accounts

The need for USD banking infrastructure is driven by specific, practical requirements that emerge when serving US clients or operating in USD-denominated markets.

Client payment systems are built for domestic transfersThe accounting and procurement systems of many US companies are configured for ACH payments within the US banking network. International wire transfers trigger different workflows, require additional approvals, and often involve manual processing that slows everything down. Providing US bank account details removes friction from what would otherwise be a straightforward transaction.

International payments can be expensiveIf a US client sends you $10,000 via international wire transfer, the money will pass through multiple banks before reaching you. Your client’s bank will charge a wire fee, typically $30-50. Intermediary banks (correspondent banks that facilitate cross-border transfers) may charge about $20-40. Your local bank could also charge a receiving fee, often $15-25.

Then comes currency conversion. If your account is in local currency, your bank converts USD to your local currency at a rate that includes a 3-5% markup over the mid-market rate. A $10,000 payment can be reduced to $9,400 by the time it reaches your account. Over a year, across multiple clients, this adds up to thousands of dollars.

With a USD business account, the client pays via ACH (with minimal fees), the funds clear through the US banking system in 1–3 business days, and you receive the amount in USD. You decide when and how to convert it to local currency, giving you control over conversion timing and rates.

Many platforms require US accountsIf you’re selling through Amazon US, using Stripe for payment processing, or receiving payouts from US-based platforms, you’ll need US bank account details to receive your payments. International alternatives exist but are often slower, more expensive, or restricted. Having US banking details unlocks full platform functionality and faster access to your money.

Business credibility matters in contract negotiations.When negotiating with US clients, particularly larger companies or enterprises, having a US bank account signals operational maturity. It shows you’re set up to work professionally with US businesses. Some RFPs (requests for proposals) explicitly request US banking information. Being able to provide it removes a potential barrier to winning contracts.

How USD business accounts work without US entities

Modern financial infrastructure has created solutions specifically for this gap. Understanding the mechanics helps you evaluate whether these solutions are legitimate, safe, and suitable for your business.

The infrastructure supporting modern USD accounts relies on banking-as-a-service partnerships. Fintech platforms hold financial services licenses in regulated jurisdictions, such as FinCEN in the US. These platforms partner with FDIC-insured US banks. The partnerships allow them to issue US bank account details (routing numbers and account numbers) to their customers without those customers needing to open accounts directly with the US bank.

What to look for in a USD business account provider

Before committing to any provider, evaluate them across several critical dimensions, as choosing the wrong one creates problems that offset the benefits of having USD access.

Regulatory legitimacy is the foundation

  • Verify the provider holds actual financial services licenses. Check whether they’re regulated by FinCEN.
  • Find out who the partner bank is. The bank should be publicly named and verifiable through banking directories.
  • Check how long the provider has been in operation. Although newer isn’t necessarily bad, track record matters when you’re trusting someone with business funds.
  • Review their compliance history. Have there been regulatory actions, fines, or public complaints about frozen accounts, fund access issues, or regulatory violations?

Confirm the account features

  • Make sure you receive real US routing and account numbers. Not all “USD accounts” provide these, as some only offer USD balance storage without access to the US payment system.
  • Confirm ACH receiving capability, which is essential for receiving payments from most US businesses.
  • Check domestic and international wire support for clients who can’t or won’t use ACH.
  • Evaluate multi-currency support if you need EUR, GBP, or other currencies beyond USD, as having everything in one platform is more efficient than juggling multiple providers.
  • Understand account limits: receiving limits (maximum per transaction or per month), balance limits (maximum you can hold), and transaction limits (number of transactions allowed).

Cost structure requires careful analysis

  • Look at account-opening fees, which are typically one-time charges ranging from $0–100, depending on the provider.
  • Check monthly maintenance fees. Some providers charge $0, others charge $10–50 monthly.
  • Understand FX conversion margins, which are the real cost for most users. This is the spread between the mid-market exchange rate and the rate the provider offers you.
  • Check withdrawal fees for moving money from your USD account to your local bank account.

Speed and reliability

  • Understand how long ACH payments take to settle and become available. It’s typically 1–3 business days, but confirm.
  • Know whether you can access funds immediately upon arrival or if there’s a holding period.
  • Research the platform’s uptime history. Platform downtime means you can’t access money, which can be critical during time-sensitive situations.

Integration and operational efficiency

  • Check whether the platform integrates with accounting software such as Xero or QuickBooks.
  • Evaluate the quality of transaction records and statements. Are they detailed enough for accounting and tax purposes?
  • If you need programmatic access, verify the API availability and documentation quality.

Customer support

  • Check how quickly their support team typically respond to queries and review the support channels: chat, email or phone.
  • Verify business hours and whether they align with your timezone.
  • Read reviews specifically about support quality, not just platform features.

Security features

  • Ensure two-factor authentication is required and robust.
  • Check what transaction monitoring and fraud detection systems are in place.
  • Review their security incident history.
  • Have there been breaches, and how were they handled?

Also read: Receiving foreign income as a solo founder

Grey Business: USD accounts for non-US businesses

Grey Business provides USD business accounts for companies operating outside the US who need US banking infrastructure to receive payments and manage USD income efficiently.

What Grey Business provides:

When you open a Grey Business account, you receive a USD business account that includes a US routing number and account number, enabling you to receive ACH payments exactly as US businesses do.

You can also deposit or withdraw USDC via the BEP20 network, send funds to any compatible wallet in seconds, and create multiple virtual USD cards. And if you want to make bulk payments, you can do that easily by uploading a CSV file with their details.

How account setup works:

  • Visit www.business.grey.co to create an account
  • Provide your business registration documents. The requirements vary by country, such as CAC documents in Nigeria, business registration certificates in Kenya, incorporation documents in South Africa, or equivalent from wherever your business is registered.
  • Then you provide information about directors and beneficial owners, business address, and business activities.
  • Once approved, you get access to your USD accounts with full banking details.

LDMAG1

Regulatory framework and fund protection

Grey is regulated by FINTRAC (Financial Transactions and Reports Analysis Centre of Canada) and FinCEN (Financial Crimes Enforcement Network in the US). These regulatory bodies oversee anti-money laundering compliance, know-your-customer requirements, and financial services operations.

Your funds are held in segregated accounts at our partner banks, keeping them separate from operational funds and providing protection.

Also read: Meet Grey Business: the growth engine for global finances

Access, not relocation

Years ago, serving US clients from Nigeria, Kenya, South Africa, or India meant either navigating expensive, slow international payment infrastructure or forming costly US entities you didn’t actually need.

Today, that market gap is filled by modern financial infrastructure specifically designed for businesses operating globally without relocating their legal or physical presence.

Open your Grey Business account today and get a USD business account with local banking details as your business takes the next step in its globalisation.

‍

Is Grey legit and safe to use? Honest review for 2026

•

•

2 min read

We built Grey to make it easier for people and businesses to receive, manage, and spend money across borders.

With Grey, you can hold foreign currencies, convert between them, spend with a linked card, and send money internationally, all from one platform.

But when it comes to financial services, the important question of trust always comes up.

If you’re considering using Grey to receive payments, hold foreign currency, or manage international transactions, it’s completely normal to ask questions.

Here’s a clear breakdown of how Grey works and the systems we put in place to keep your money and data secure.

Is Grey safe?

Grey is a fintech platform that provides multi-currency accounts and payment infrastructure. We’re not a bank, and it’s important to be clear about that upfront. You can hold USD, EUR, and GBP, convert between currencies, spend using cards, and withdraw funds to your local bank account.

As a financial service provider, we operate within compliance frameworks designed to protect users and ensure accountability. These include:

  • KYC (Know Your Customer) requirements
  • AML (Anti-Money Laundering) regulations
  • Ongoing transaction monitoring and compliance checks

These frameworks are standard across the financial industry and are essential for preventing fraud and illegal activity.

We also work with regulated partner institutions to provide our services.

Website and app security

We designed Grey primarily for online and in-app use, so we built security into every layer of the experience.

To open an account, you must complete a verification process and set secure login credentials. Once active, your account is protected with:

Behind the scenes, we run security checks and monitoring systems to detect and prevent suspicious activity.

On your end, you can:

  • Monitor transactions in real time
  • Freeze or unfreeze cards instantly
  • Manage multiple cards for different use cases
  • Track balances across currencies

These features give you transparency and control over your finances.

Is it safe to send money with Grey?

Yes, Grey is safe for sending money internationally.

To make a transfer, you need to verify your account first. This ensures that all transactions are tied to verified identities, reducing the risk of fraud.

Your payments are processed through secure financial networks, and you can track the transactions within the app.

If you need help with anything, you can reach out to support@grey.co for assistance with transactions or account-related issues.

Is it safe to leave money in your Grey account?

When you hold funds in your Grey account, they aren’t mixed with our operational finances. Instead, we hold them with regulated partner institutions in segregated accounts.

This means:

  • Your money always remains separate from company funds
  • Your funds are available when you need them
  • You can convert, spend, or withdraw at any time

Unlike traditional banks, Grey does not use customer funds for lending. Our focus is on enabling access, movement, and control of money, not leveraging deposits.

Also read: Why creators move away from Payoneer and PayPal

Why does verification matter?

Why do you need to submit identity documents, proof of address, and sometimes additional information about income sources or business activities?

The answer is regulation. Financial services are legally required to verify the identity of their customers. This is KYC (Know Your Customer) compliance, designed to prevent money laundering, fraud, and other financial crimes. Every legitimate bank, fintech platform, or payment processor must do this.

When we ask for your ID, proof of address, or business documentation for Grey Business, we’re complying with the law and keeping you safe.

Also read: How to budget in foreign currencies using the Grey card

Where does Grey Business fit in?

We designed Grey Business for SMEs, agencies, startups, and growing teams that need proper business-level financial infrastructure for international operations.

This way, there’s a clearer separation between personal and business finances, which is important for accounting, tax compliance, and professional credibility.

For businesses, compliance and structure matter even more than for individuals. You’re managing company funds, potentially with partners, investors, or regulatory obligations. With this reality in mind, Grey Business offers USD and USDC accounts, bulk pay outs in multiple currencies and access to multiple virtual USD cards.

Also read: Meet Grey Business: the growth engine for global finances

LDMAG1

When Grey might not be the right fit for you

If you need traditional banking services like loans, mortgages, or overdrafts, we don’t provide those. Our focus is on multi-currency accounts and payments, not full-service banking.

If you operate entirely in one currency and never deal with international payments, Grey probably isn’t necessary.

If you’re uncomfortable with digital-only financial services and prefer in-person banking, Grey won’t suit you. You can mange everything through the app and our 24/7 online support.

So, is Grey legit and safe?

Is it legit? Yes. Is it safe? Yes

The question shouldn’t be whether Grey is safe in some absolute sense, it’s whether it’s the right tool for your needs. If you’re managing foreign currency, receiving international payments, or running a business with cross-border operations, Grey is perfect.

Trust takes time to build, and that’s fair. Start small if you’re cautious. Use Grey for one payment, see how it works, and decide from there.

Open your free Grey account or explore Grey Business if you’re ready to manage international payments with proper infrastructure behind them.

‍

Here’s how to pay your UK school fees from Nigeria

•

•

2 min read

If you are a Nigerian student about to study in the United Kingdom, you may find it challenging to pay your school fees due to the currency differences and unfavorable exchange rates. It can also be confusing to determine what exact payment method to opt for. 

Fortunately, there are several ways to pay for your UK school fees from Nigeria that won’t leave a dent in your funds. We’ll explore those options in this article.

Paying for your school fees deposit

Perhaps the most crucial part of your fees is the deposit, and this is because it determines how soon you get your CAS. 

Most Nigerian students prefer to pay using FORM A because you can get pounds via bank rates. However, due to the recent delays associated with this payment method, we only recommend using it when paying your other installments.

Since the payment window for paying your deposit is particularly short, you should consider the fastest and easiest way to transfer the money to your school. 

Your school will share some of the acceptable payment methods, which often include paying via bank transfer, a debit card, or in person. Since paying in person is not an option for you as a Nigerian living in Nigeria, here’s how you can pay your UK school fees deposit;

Pay via bank transfer

One of the most popular ways to pay your UK school fees is by bank transfer. To do this, you’ll either need a GBP domiciliary account or a UK bank account. The issue with a domiciliary account is that processing it takes more time, which can be counterproductive. 

This is why getting a Grey UK bank account is the perfect option. Since it’s already domiciled in the UK, transfers are faster and much easier. You will also need the banking details of your UK school, including their SWIFT code and account number. You can find this on their payment page. 

Once this is sorted, here’s how to pay your school fees deposit via a bank transfer;

  • Log in to your Grey account.
  • Top up your Naira balance via a bank transfer to your NGN virtual account.

ngn account on grey
  • Once the funds reflect in your Naira balance, swap to GBP
  • You can track our real-time exchange rates on the rates page
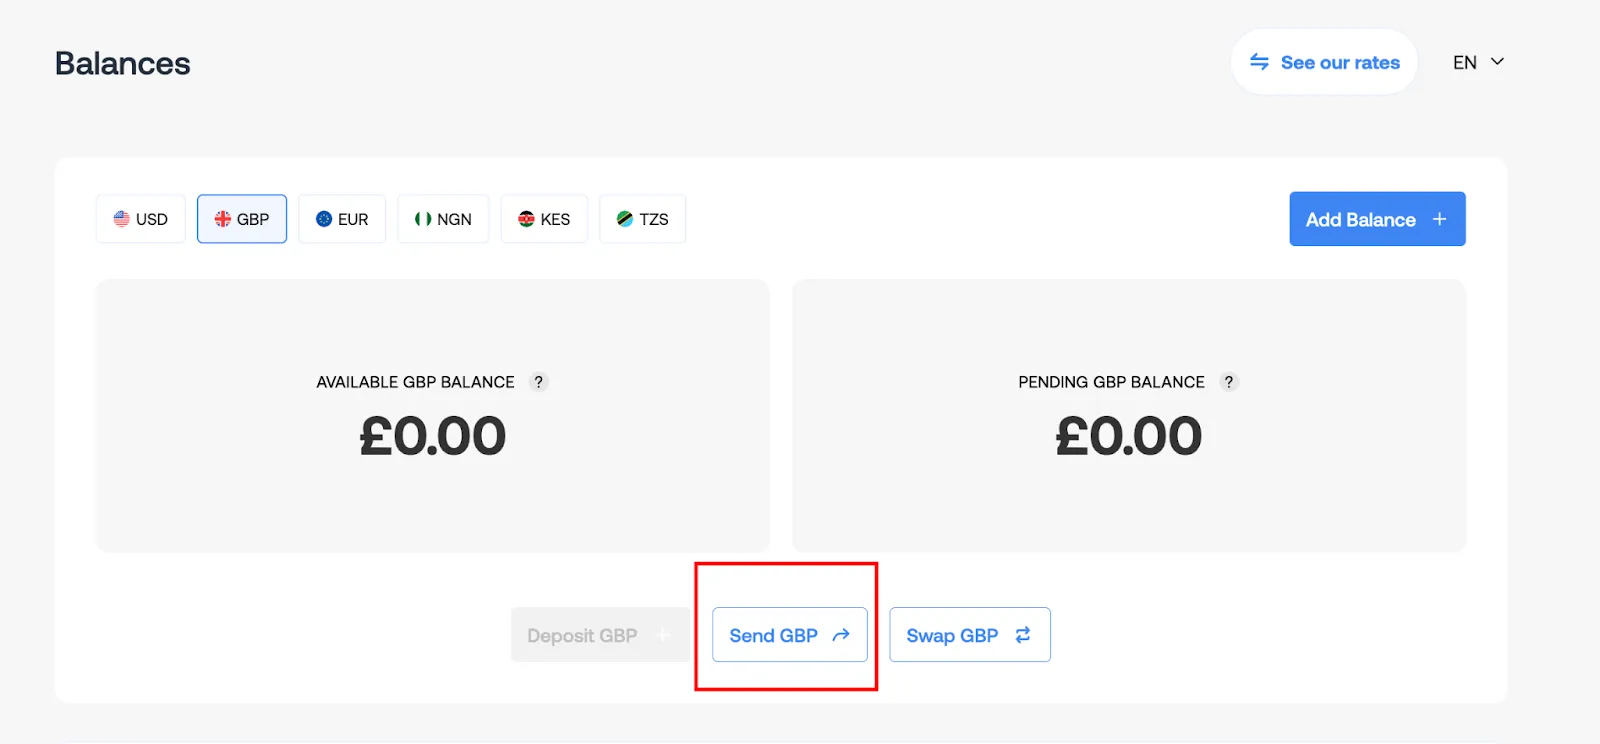
  • Now in your GBP balance, tap on ‘Send GBP’
send-gbp-with-grey
  • From the dropdown menu, tap on ‘Send to New Recipient’
  • In the recipient’s currency, select ‘GBP’ and proceed to enter the remaining details
entergbp-details
  • Double-check to be sure that your school banking details are correct before completing the transaction.
  • Once it sends, share the transaction receipt with your school and wait for payment confirmation from them.

Please note that bank transfers to the UK typically take 1-3 working days, excluding weekends and holidays.

Pay via debit card

Another way to pay your UK school fees is via a debit card. Usually, your school will also have a portal where you can directly make payments via a card. However, since all Naira cards don’t work for international payments, you can only pay using your domiciliary account card or via a virtual card.

Since the Grey USD card works for every international payment, we strongly recommend this option, especially if you don’t have a domiciliary bank card. This is because the Grey virtual card is efficient, reliable, and there are no hidden fees associated with your payments, unlike most cards.

To pay your school fees via debit card, here are the steps you can follow

  • Log in to your Grey app.
  • Top up your Naira balance via a bank transfer to your NGN virtual account
  • Visit the cards section and top up your Grey USD virtual card from your Naira balance
  • If you don’t have one yet, here’s how to create a virtual card on Grey
  • Once your funds reflect on your card, visit your school portal and pay with it
  • Complete the transaction and wait for payment confirmation from your school

For subsequent payment installments

Once you’ve completed the visa application process and started your studies in the UK, paying for the rest of your fees will be pretty easy. You can choose to pay using any of the following options above or even in person now.

However, we recommend using Form A, especially if your school fees balance is in Naira. Form A is an international payment method offered by the Central Bank of Nigeria and commercial banks. 

The CBN gives these banks a specific amount of foreign currency and instructs them to sell it at bank rates. As an international student, you qualify for this bank exchange rate. In this case, your bank makes the payment on your behalf to your school and notifies you when the transaction is complete.

What you need to qualify for Form A as an international student

Since you’d have to fill out a form online, here are a few documents you’ll need to verify your status as an international student from Nigeria;

  • Your school admission letter or unconditional offer
  • A valid Nigerian international passport
  • School invoice that contains the school’s banking details
  • WAEC certificate for undergraduates
  • First-degree certificate for postgraduate students
  • Sponsors ID if you’re paying through a sponsor
  • The equivalent amount of your school fees in your Naira bank account

How to pay for your school fees abroad using Form A

Once you have all the documents listed above, here’s how to pay for your school fees via Form A.

  • Visit the Trade Monitoring System Applicant Portal
  • Sign up using your BVN as an individual
  • You’ll get an OTP in the email address linked to your BVN. 
  • Verify your email and login to your portal
  • Select ‘Educational fees’ from the options under Form A
  • Fill out the forms displayed and upload all your required documents
  • Review your entry and submit

Once you submit, the prompt is sent to your bank so they can review and process your transaction.

Please keep in mind that, unlike payment options with Grey, using Form A requires a longer processing time. Since the transaction is highly dependent on the country’s FX availability, it can take up to months. If you’re in a hurry, we recommend paying in person, using a bank transfer or a debit card, to be on the safer side.

So whether you’re paying your first deposit or subsequent installments, carefully consider the fees and exchange rates to ensure you are getting the best deal. Grey has transparent rates and prices, so you’re guaranteed affordable currency exchange and faster payments. Sign up to get started.

The digital nomad's guide to managing money across borders in 2024

•

•

2 min read

The laptop lifestyle is a dream many aspire to live: working from beautiful places, sipping coffee with a view from a quaint cafe, and taking your work with you anywhere you go. It’s a vision of freedom and flexibility.

But behind the Instagram-worthy sunsets and the allure of location independence lies a not-so-glamorous reality for digital nomads: managing your finances across borders.

The financial challenges of the wandering worker.

Ah, the joys of currency fluctuations. You meticulously budget for your dream co-working space in Lisbon, only to have the Euro suddenly surge and the naira crash even further, leaving your workspace feeling more like a closet. And then there’s the niggling pain of budgeting.

Keeping track of expenses in different currencies can feel like juggling flaming chainsaws while blindfolded. Throw in those pesky international bank fees that swallow a significant chunk of your hard-earned income, and you’ve got a recipe for financial frustration.

Essential tips for managing your finances while you travel the world.

Fear not, fellow wanderers! Financial freedom on the road is achievable. Here are some battle-tested tips I've gathered on my own adventures to help you conquer the financial side of the digital nomad life:

Ditch the static budget:

A rigid, one-size-fits-all budget just doesn’t work for a constantly inconstant life. Consider a zero-based budgeting approach, allocating every dollar you earn to specific categories. You can also explore a more flexible system that adapts to your location. For instance, you might assign a larger portion of your budget for transportation in cities with limited public options and adjust accordingly when you settle into a more walkable location.

Also read: Smart budgeting tips for digital nomads in 2024

Embrace the freedom of a borderless bank account:

Opening a borderless bank account can be a game-changer. Look for an option with low international transaction fees and the ability to hold multiple currencies. Imagine the freedom of not having to worry about exchange rates every time you buy a cup of coffee in a new city! This eliminates the need for multiple bank accounts in different countries, simplifying your financial life significantly.

Budgeting apps:

Budgeting apps are your secret weapons for tracking income and expenses, categorising your spending habits, and setting realistic financial goals when moving. Popular options like YNAB or Mint can help you wrangle those multiple currencies and keep your financial house in order, even when your actual home is constantly changing.

__wf_reserved_inherit

Build an emergency fund for life's curveballs:

Life throws curveballs, which sometimes involve accidents, hefty medical bills, or travel disruptions. Don’t let an unexpected expense derail your digital nomad journey. Consider investing in travel insurance to cover medical and non-medical risks while travelling. You can also set aside an emergency fund to cushion the blow of unforeseen costs.

Diversify your income streams:

If you can help it, don’t limit yourself to a single source of income. The more diverse your income, the wider your safety net and financial cushion. Every little bit counts! Especially if you’re a freelancer, building multiple income sources can protect you from fluctuations in any one income stream.

Introducing Grey: Your cross-border financial partner

Remember how I mentioned feeling overwhelmed by managing finances on the road? Well, that's where Grey comes in. Grey is a revolutionary cross-border payment app designed specifically for remote workers like us. Here's how Grey can be your financial bestie on the road:

Fast, secure, and affordable:

Say sayonara to those bank charges that make you wince, and hello to cheap exchange rates! Grey helps you receive payments from international clients quickly and securely, with minimal fees.

Grey makes it easy to manage your money globally, whether you're getting paid or sending money. With Grey, you can also send money across the world, including cryptocurrencies.

Manage multiple currencies easily:

Hold and manage different currencies in a single, secure wallet. Swapping between currencies is a breeze with Grey so you can ditch the hassle of multiple bank accounts and spreadsheets.

Manage finances from anywhere:

Grey's user-friendly mobile app lets you manage your money from anywhere in the world with truly inclusive global banking. No need to be chained to your laptop – you can literally be conquering that mountain peak in the Philippines while checking your balance or receiving payment from your client in Switzerland!

__wf_reserved_inherit

How to manage multiple currencies as an expatriate with Grey

•

•

2 min read

Living as an expatriate and remote worker often means juggling multiple currencies, which can be tricky when it comes to managing finances. How do you stay on top of exchange rates, international transfers, and fees without letting it become overwhelming? This article offers practical tips to help you simplify your finances and manage your money effectively across different currencies with Grey.

Why expatriates need to manage multiple currencies

For most expatriates, handling multiple currencies is part of daily life. Whether you’re receiving salary payments in one currency, paying rent or bills in another, or saving for a rainy day, managing financial obligations requires careful organisation. Here’s why it’s crucial to take control of your multi-currency needs:

  • Currency fluctuations: The value of currencies fluctuates frequently, and even minor changes in exchange rates can impact how far your money stretches. For instance, if you earn in US dollars but live in Europe, the EUR/USD exchange rate can significantly affect the value of your income.
  • Conversion fees: Hidden or high conversion fees imposed by traditional banks and financial institutions can quickly eat into your savings. Over time, these charges can add up, making it harder to maintain a balanced budget.
  • Managing multiple accounts: When dealing with various currencies, it is easy to lose track of your funds across different accounts. This can lead to disorganisation and difficulties in budgeting, especially if you need to keep track of multiple accounts in various currencies.

The good news is that with the right financial tools, managing multiple currencies doesn’t need to be a hassle. Grey offers a comprehensive solution to help expatriates stay organised, reduce conversion fees, and streamline financial management.

Also read: Why is international payment so complex for migrant workers?

Choosing the ideal bank account for expatriates

A multi-currency account is one of the best solutions for managing multiple currencies. Traditional banking systems often impose high fees and lengthy processing times for international transactions. Grey offers a modern, efficient alternative that makes international financial management simple and affordable.

  • Low conversion fees: Look for a platform that offers competitive exchange rates and low conversion fees. Grey stands out for its affordable rates and transparent pricing, ensuring you get the most value from your currency exchanges.
  • Multi-currency support: Make sure the platform supports all the currencies you regularly use. Grey offers seamless multi-currency support, allowing expatriates to hold and transact in various currencies, from USD to EUR and beyond.
  • User-friendly interface: Choose a platform that is easy to navigate, helping you manage and track your finances without complexity. Grey provides an intuitive and streamlined platform to make managing your finances as straightforward as possible.

Benefits of using Grey for currency exchange

Expatriates need access to reliable and cost-effective currency exchange platforms, and Grey provides just that. Here’s why Grey is an excellent choice:

  • Competitive exchange rates: Unlike traditional banks that often have high margins, Grey offers real-time market exchange rates, ensuring you get the best value for your money.
  • Fast international transfers: Sending money across borders is quick and hassle-free. Grey processes international transfers swiftly, sometimes within a few hours or instantly, so you can send money without delay.
  • Stay informed: Use Grey’s currency converter to monitor real-time exchange rates. This will give you complete control over your transactions and ensure you make the most of every currency exchange.
  • Transparent pricing: Grey offers clear, upfront information about all fees associated with currency exchanges and transfers, so you won’t be hit with hidden charges.

How does Grey simplify currency management?

Grey is designed to meet the needs of expatriates managing international finances. Here's how Grey works for expatriates and migrants:

1. Open a multi-currency account

Grey allows you to create virtual accounts in USD, EUR, and GBP, making receiving payments in these currencies easy. Follow these steps to get started:

  • Sign up on Grey: Visit Grey’s website or download the app and create your account.
  • Verify your identity: Upload your identification documents for a quick and secure verification process.
  • Access your accounts: Once verified, you can request US dollars, UK Bank Accounts or Euro bank accounts to help receive your foreign currency payments.

With these accounts, you can receive foreign payments or transfer funds without relying on expensive traditional banking.

2. Convert currencies at competitive rates

Grey allows you to convert foreign currencies at competitive exchange rates, saving you money compared to traditional banks. Here’s how:

  • Log in to your Grey account and navigate to the "Convert" section.
  • Select the currency you want to convert and specify the amount.
  • Review the live exchange rate and confirm the transaction.
  • Your converted funds will be credited instantly to your Grey account.
  • You can take a look at how Grey currency conversion works to get started.

Grey's currency conversion is invaluable for expatriates who need to make local payments while holding income in foreign currencies.

3. Using a US virtual card to simplify payments

As an expatriate, a USD virtual card is one of the best tools you can have. Obtaining a USD card can often be complicated, with restrictions, high fees, and problems funding the card in local currencies. Grey offers a simple solution with its US virtual card, providing a seamless way to make payments across a wide range of platforms and services.

  • Global access: A USD debit card gives you access to international stores, brands, and services, allowing you to shop online or in-store without worrying about exchange rates.
  • Save on fees: The Grey USD virtual card allows you to avoid the high conversion fees typically charged by traditional banks when making foreign currency payments.
  • Travel convenience: When you’re travelling, use your Grey USD Mastercard to pay for hotels, flights, transportation, and more without the stress of fluctuating exchange rates.
  • Subscription payments made easy: Many popular services, including Netflix, Spotify, and Adobe, charge in USD. With a Grey USD card, paying for these services is simple and cost-effective.

You may also like: How to get an instant USD debit card online in 2025

Keep your finances organised and safe with Grey

Managing multiple currencies is simpler when you have the right tools. Grey offers an intuitive platform to help expatriates stay organised, track their spending, and manage their budgets effectively.

  • Financial tracking: Use Grey to centralise all your financial information, monitor your spending, and stay within your budget, while tracking multiple currencies in real-time.
  • Create strong passwords: Always use unique and complex passwords for your Grey account to safeguard your funds.
  • Enable two-factor authentication: Grey offers two-factor authentication for added security, ensuring that only you can access your account.

Simplifying multi-currency finances for global expatriates

Managing multiple currencies doesn’t have to be overwhelming. With Grey, expatriates can easily navigate financial complexities, reduce unnecessary fees, and stay organised. Grey is the all-in-one solution for managing your finances while living abroad, allowing you to focus on what matters most: your life abroad.

Open a bank account with Grey today and enjoy the freedom of seamless international transactions, low conversion fees, and a range of features designed for the world's most ambitious expatriates.

‍

Arrow (up)

Back to top