<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/how-to-receive-and-convert-foreign-currencies-to-usdc-in-australia#article","headline":"How to receive and convert foreign currencies to USDC in Australia","description":"Freelancers in Australia can easily receive foreign payments and convert them to USDC with Grey","inLanguage":"en","url":"https://grey.co/blog/how-to-receive-and-convert-foreign-currencies-to-usdc-in-australia","mainEntityOfPage":{"@id":"https://grey.co/blog/how-to-receive-and-convert-foreign-currencies-to-usdc-in-australia#webpage"},"datePublished":"2024-11-19T18:09:08.778Z","dateModified":"2026-06-15T18:10:13.864Z","author":{"@type":"Person","@id":"https://grey.co/authors/olayoyin-olorunmota#person","name":"Olayoyin Olorunmota","url":"https://grey.co/authors/olayoyin-olorunmota","jobTitle":"Content Writer","sameAs":["http://www.linkedin.com/in/olayoyinolorunmota","http://x.com/yoyin_michael"]},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/how-to-receive-and-convert-foreign-currencies-to-usdc-in-australia#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/673cd238eba8a8d5e02a3d50_How_to_receive_USDC_payments_as_a_freelancer_in_Australia.webp","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/673cd238eba8a8d5e02a3d50_How_to_receive_USDC_payments_as_a_freelancer_in_Australia.webp","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/how-to-receive-and-convert-foreign-currencies-to-usdc-in-australia#webpage","url":"https://grey.co/blog/how-to-receive-and-convert-foreign-currencies-to-usdc-in-australia","name":"How to receive and convert foreign currencies to USDC in Australia","description":"Freelancers in Australia can easily receive foreign payments and convert them to USDC with Grey","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/how-to-receive-and-convert-foreign-currencies-to-usdc-in-australia#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/how-to-receive-and-convert-foreign-currencies-to-usdc-in-australia#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/how-to-receive-and-convert-foreign-currencies-to-usdc-in-australia#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"How to receive and convert foreign currencies to USDC in Australia","item":"https://grey.co/blog/how-to-receive-and-convert-foreign-currencies-to-usdc-in-australia"}]}] </script>

How to receive and convert foreign currencies to USDC in Australia

Olayoyin Olorunmota

TABLE OF CONTENT

SHARE THIS POST

Australia may have some of the quirkiest animals around, but when it comes to managing foreign payments, Grey ensures your finances are predictable.

For professionals juggling clients across borders, USD Coin (USDC) offers a straightforward way to receive and convert payments, taking away the drama of exchange rate volatility.

This guide walks you through how freelancers in Australia can use Grey to receive foreign payments, convert them to USDC, and access their funds securely and efficiently.

Why convert foreign payments to USDC as a freelancer in Australia?

For freelancers working with clients abroad, converting foreign currencies to USDC offers several advantages:

Stable value: As a stablecoin tied to the U.S. dollar, USDC provides a predictable value, helping freelancers avoid the volatility of other cryptocurrencies.

Low fees: USDC transactions often come with lower fees than traditional bank transfers, making them cost-effective for international payments.

Quick access to funds: Blockchain technology allows for near-instant transfers, so freelancers can quickly access their funds.

Flexible conversion: You can hold USDC for stability and convert it to Australian dollars (AUD) when rates are favourable, giving you financial flexibility.

‍

Also Read: Send instant USDC payouts to 40+ countries with Grey

Receiving and converting foreign currency to USDC

Grey offers a secure and straightforward method for freelancers to manage USDC payments. Here’s how you can send and convert USDC using Grey:

Open the Grey app

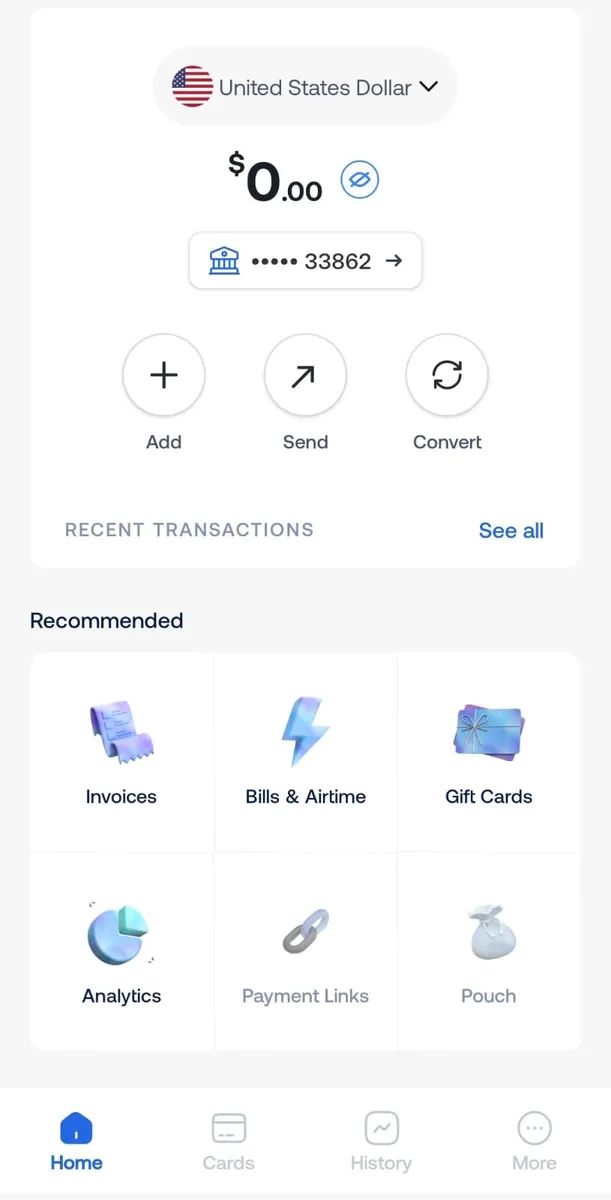
Log in to your Grey account through the app or website for secure access to your USD and other currency balances.

Select your USD balance

Navigate to the “Accounts” section and select your USD balance. This will serve as the starting point for initiating USDC transfers.

__wf_reserved_inherit

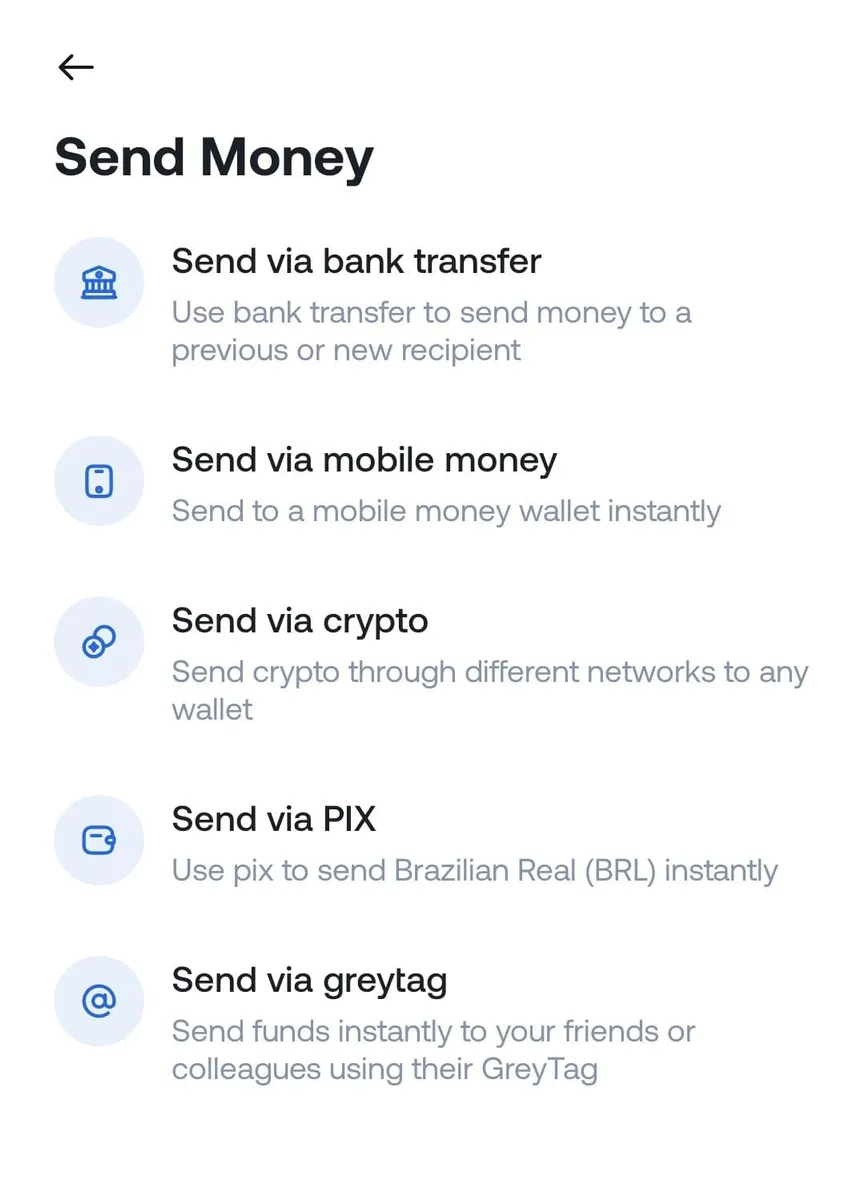
Tap “Send via crypto”

Choose the “Send money” option, then select “Send via crypto” to start the USDC transfer process.

__wf_reserved_inherit

Enter transaction details

Input the recipient’s wallet address carefully. Ensure you select the correct network, as Grey supports Solana (SOL) and Binance Smart Chain (BEP-20).

__wf_reserved_inherit

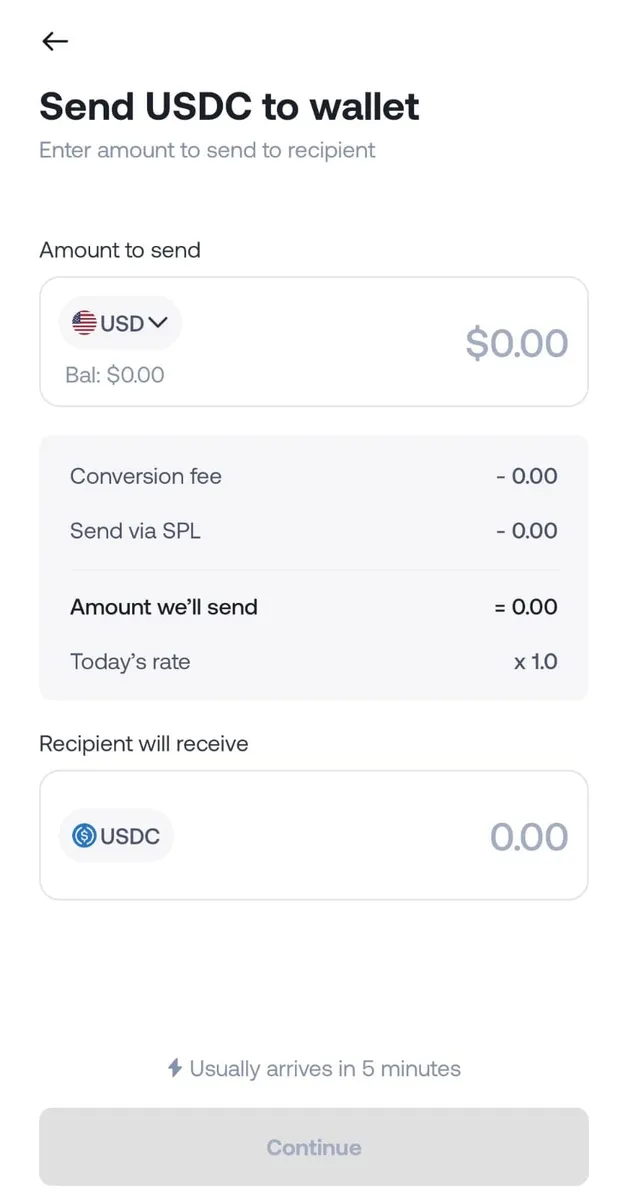
Input the transfer amount and review the details

Specify the amount you want to send and make sure to double-check the wallet address and network to ensure your transaction goes in the right place.

__wf_reserved_inherit

Confirm and complete the transfer

Once satisfied with the details, tap “Send.” Grey will prompt you to enter your two-factor authentication (2FA) code for added security.

Transaction success

The USDC will arrive in the recipient’s wallet after processing. The recipient can keep the USDC, convert it into local currency, or use it as needed.

Also Read: How to receive dollar payments and convert to USDC in Mexico

Converting USDC to Australian dollars

To convert USDC to AUD, you can use a crypto exchange or a local service supporting USDC-to-AUD transactions. Look for platforms with competitive rates and ensure they support the blockchain network you’re using.

Considerations for freelancers holding and converting USDC

While holding USDC is convenient, here are a few factors to consider:

Network compatibility: Ensure the network used for USDC matches your wallet and conversion services to avoid transaction issues.

Fee awareness: Although USDC has low transaction fees, network fees may vary depending on the blockchain.

Tax compliance: In Australia, cryptocurrencies are subject to tax regulations, depending on how you acquire, hold, and dispose of the asset. Consult a tax advisor to understand your obligations when holding or converting USDC.

Using Grey to simplify USDC management

With Grey, you can securely send USDC to supported wallets, manage funds with ease, and take advantage of robust security measures like two-factor authentication (2FA).

Grey makes receiving and managing USDC payouts effortless for freelancers in Australia. Start today by creating your Grey account and unlock the benefits of global financial freedom.

The future of global banking is here, designed for you.

__wf_reserved_inherit

‍

Last updated:

October 2, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

What is the currency of Cambodia? Riel symbol and code

•

•

2 min read

Before a trip to Siem Reap, you look up Cambodia’s currency and find that it’s the riel. Then a friend who has been there tells you to bring US dollars, and the first ATM you use hands out dollars, not riel. Both are true, and how the two currencies fit together decides how you pay, what change you get back and where you lose money to poor rates. This guide covers the riel, its symbol and code, why dollars circulate alongside it, and how to spend and send money in Cambodia.

The currency of Cambodia is the Cambodian riel, symbol ៛ and code KHR. In practice, US dollars are widely used across Cambodia, especially for larger purchases, while riel is often used for small change. Many prices are quoted in dollars in tourist areas.

What is the currency of Cambodia?

The currency of Cambodia is the Cambodian riel, but US dollars are used alongside it every day, so most visitors end up handling both. The riel is the national currency, and the National Bank of Cambodia is its sole issuer. The dollar isn't issued by Cambodia at all, yet it's what most ATMs dispense and what many hotels, restaurants and shops use to set their prices.

In practice, the two currencies split the work:

  • US dollars cover larger payments: hotel rooms, tours, restaurant bills and most prices in cities and tourist areas.
  • Riel cover small purchases such as street food and tuk-tuk rides, and they’re the everyday currency in rural areas.

There are no US coins in circulation in Cambodia, so any change smaller than a dollar comes back in riel. That's why a visitor's wallet is usually a mix: dollar notes for the main payment and a stack of riel for the change. Near the Thai border, shops may also accept Thai baht, though usually at a poor rate.

The rest of this guide covers the riel itself, how the dollar became so common, and what to do with both when you travel or send money.

The Cambodian riel: Symbol and code

The Cambodian riel uses the symbol ៛ and the ISO currency code KHR. You'll see ៛ on price lists and signs in Cambodia, while KHR is the code used by banks, exchange apps and currency converters. The National Bank of Cambodia says it is the sole issuer of the Khmer riel, the national currency.

The riel is nominally divided into 100 sen, but sen aren't used in everyday life. Riel banknotes run from 100 riel up to 100,000 riel, and because a single riel is worth so little, prices in riel are usually written in the thousands.

A US dollar buys roughly 4,000 riel, and shops commonly round to that figure when they work out change. Rates move, so check the day's rate before you exchange money. The National Bank of Cambodia describes its approach as a managed floating exchange rate, where the rate is allowed to move within a band.

That high number of riel per dollar is why the currency appears on lists of the least valuable currencies. Such a ranking only counts how many units buy one dollar. It doesn't measure how strong an economy is, and a low-value currency can reflect history, such as past hyperinflation, rather than current conditions.

Why US dollars are used in Cambodia

US dollars are used in Cambodia because people lost confidence in the riel after years of upheaval, and a large inflow of dollars in the early 1990s made the dollar the easier currency to trust and spend. The National Bank of Cambodia's own research paper on dollarisation says dollarisation did not result from a policy decision. It built up as shocks wore down trust in the riel.

Year What happened
1975 The Khmer Rouge destroyed the financial system and decided not to issue a new currency
1980 The central bank was re-established and the riel became legal tender again
1990 to 1992 Central bank financing of the budget fuelled a sharp riel devaluation and three-digit hyperinflation
1991 to 1992 The UN transitional operation, which cost USD 1.7 billion, brought large dollar inflows
1993 onward The dollar has been widely used since 1993, and it stayed in use after stability returned in 1999

‍

Memory of that hyperinflation is why the habit lasted. The same paper put foreign currency at 97.3% of bank deposits at the end of 2006, which shows how far people had moved their savings into dollars. The central bank has since encouraged wider use of the riel, so the balance may have shifted, but the day-to-day split described above still holds for most visitors.

In practice, prices are often quoted in dollars, and you can pay in either currency. If a drink costs $2.50 and you pay with a $5 note, the change might come back as $2 and 2,000 riel, at the common rounded rate of 4,000 riel to the dollar.
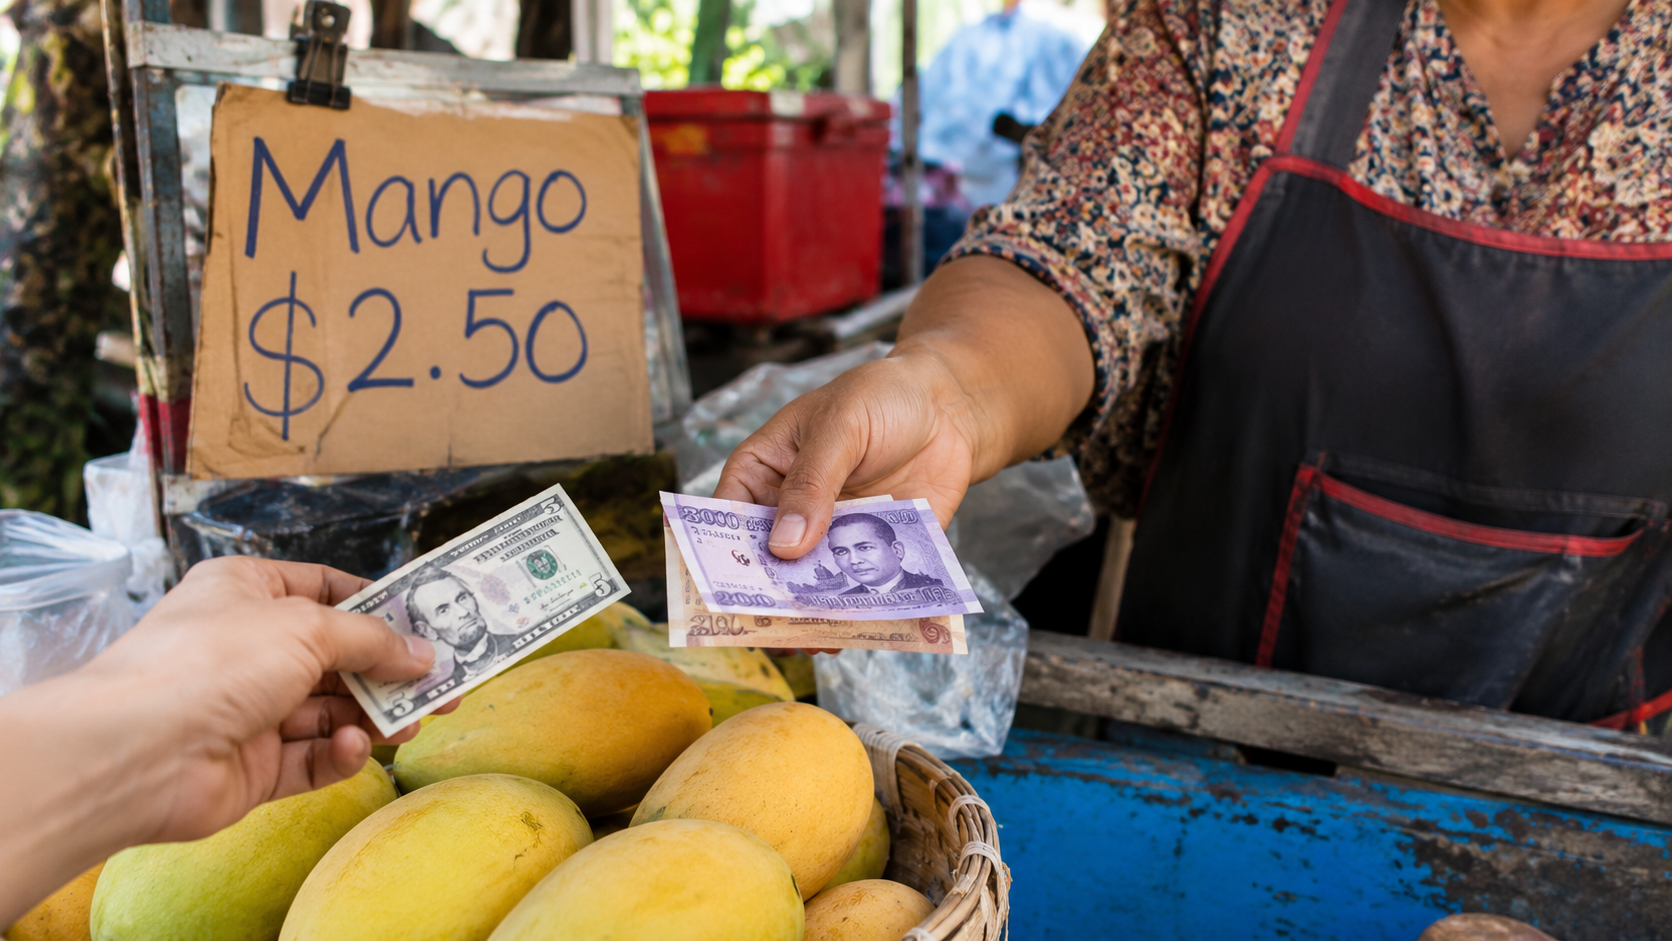
A Cambodian price quoted in US dollars with riel notes given as change.

If you earn or save in dollars, you can hold US dollars and other currencies in a Grey account, which keeps your trip budget in the currency Cambodia already prices in.

Money tips for travellers in Cambodia

For most trips, carry small, undamaged US dollar notes for everyday spending, a little riel for small purchases, and a card for the places that accept one. Cash is the main way to pay in much of the country, so a few habits protect you from the usual losses:

  • Bring clean, untorn dollar notes. Banks, money changers and shops can refuse notes with tears or heavy marks, and larger notes are the hardest to use. Check yours before you fly.
  • Carry small bills. Tuk-tuk drivers and street vendors often can't break a large note, so $1, $5 and $10 notes go further than a $50 or $100.
  • Keep some riel. You'll want it for motorbike taxis, snacks and small shops, and it has little value outside Cambodia, so spend what's left before you go.
  • Expect dollars from ATMs. Most ATMs dispense US dollars, often in large notes, and some charge a fee per withdrawal. Read the screen before you confirm.
  • Count your change. In busy tourist areas, riel change is sometimes short. A quick check takes seconds.
  • Compare money changers. Tourism Cambodia says money changers generally give slightly better rates than banks, so compare a few before you swap.

Cards work in a narrower set of places. The same source says they're accepted at upscale hotels, shops and restaurants in the major tourist towns and generally not elsewhere, and that most businesses that take cards add a fee of 2% to 4%. Ask before you pay, and keep cash as your backup.

Your own bank is the other place money leaks. Many cards add a foreign transaction fee on purchases in another currency, and how to avoid foreign transaction fees explains what to look for. Because many Cambodian prices are in dollars, a dollar card can pay those without a currency conversion, while riel prices are a different currency and may trigger a conversion or cross-border fee depending on the card.

Sending money to Cambodia

Sending US dollars is often a practical way to send money to Cambodia, as USD is widely used for everyday payments, pricing and savings. With Grey, you can send USD directly to a bank account in Cambodia via SWIFT, with a flat $30 transfer fee and limits ranging from $100 to $5,000 per transaction.

You can also send money from the US to other supported destinations, including Thailand, where Thai baht is the local currency.

Before you send, check three costs:

  1. The transfer fee: Grey shows its fees before you confirm a transfer.
  2. The exchange-rate margin: if you convert from another currency first. It's built into the rate rather than shown as a separate line.
  3. The receiving bank's own charges: Banks can add fees to incoming international transfers, so ask the recipient.

If you're travelling rather than sending, a Grey virtual card lets you spend from a USD balance. Grey doesn't charge a foreign transaction fee on purchases made in the card's base currency, which is USD for the virtual USD card. A cross-border card fee of 2% plus $0.50 applies to non-USD purchases, so a purchase priced in riel would carry it. Card acceptance varies by merchant, so keep some cash too.

Grey is a financial technology company, not a bank: banking services are provided by licensed banking partners.

Frequently asked questions

What is the currency of Cambodia?

The currency of Cambodia is the Cambodian riel (KHR). US dollars circulate alongside it and are widely used for larger purchases and in tourist areas, while riel is used mostly for small amounts and change.

What is the riel symbol?

The riel symbol is ៛. You may see it on price lists in Cambodia, while banks and currency converters use the code KHR instead.

What is the currency code for Cambodia?

The currency code is KHR. Use it in currency converters, bank forms and exchange apps when you look up the Cambodian riel.

Can I use US dollars in Cambodia?

Yes. Dollars are widely accepted in cities and tourist areas, and most ATMs dispense them. Change under a dollar comes back in riel, and torn or heavily marked notes may be refused, so carry clean, small bills.

Should I carry riel?

Yes, carry a small amount for tuk-tuks, snacks and small shops, where riel is the usual currency. It has little value outside Cambodia, so spend or exchange what's left before you leave.

How do I send money to Cambodia?

Grey lists Cambodia among the countries that can receive USD transfers by SWIFT, with a flat $30 fee and a limit of $100 to $5,000 per transfer. Check the fee and any exchange-rate margin before you confirm, and ask the recipient whether their bank charges for incoming transfers.
Send money abroad with Grey

How to transfer an eSIM from one iPhone to another

•

•

2 min read

Your new iPhone is on the table, and your phone number lives on the old one as an eSIM. There’s no SIM tray to open and no card to slide across, so it isn’t obvious how to transfer an eSIM from one iPhone to another without losing service. The answer depends on your carrier and on which version of iOS both phones are running. This guide covers the quick route, the route for after setup, the fixes when it fails, and what changes for travel eSIMs.

You can move an eSIM between iPhones with eSIM Quick Transfer, during setup or later in Settings. On the new iPhone, choose Transfer From Nearby iPhone, then tap Transfer on the old one. Both iPhones need iOS 18.4 or later, Bluetooth on and a carrier that supports Quick Transfer. If yours doesn't, your carrier can issue a QR code.

What is eSIM Quick Transfer on iPhone?

eSIM Quick Transfer is an iPhone feature that moves your phone number's eSIM from your previous iPhone to your new one over a nearby connection, so in many cases you don't need to ask your carrier for a new QR code. It's the quickest way to complete an eSIM transfer on iPhone, but it only works when your carrier supports it.

Per Apple's eSIM instructions, you need all of the following:

  • Both iPhones signed in with your Apple Account.
  • Both iPhones on iOS 18.4 or later. Transferring more than one phone number at once requires iOS 26 or later.
  • The previous iPhone unlocked with its passcode.
  • Both iPhones nearby, with Bluetooth on.
  • A Wi-Fi network or hotspot. Some eSIM-only models in certain countries can activate without one.
  • A carrier that supports eSIM Quick Transfer.

Quick Transfer appears during setup if you’re asked to transfer your phone number to the new iPhone. If you skip that prompt or your iPhone is already set up, you can start the transfer later in Settings. If neither option appears, your carrier probably doesn’t support Quick Transfer, so use the QR code route in the troubleshooting section.

If either iPhone is on older software, update it first. Check with your carrier too: support depends on the carrier, not only on the phones.

How to transfer an eSIM during iPhone setup

To transfer an eSIM during setup, turn on the new iPhone, follow the prompts until it asks you to transfer your phone number, and approve the transfer on your previous iPhone. Keep both phones close together and unlocked, with Bluetooth on, until the new plan activates. These steps use Apple’s wording for the buttons:

1. Start setup on the new iPhone. Follow the setup screens and sign in with your Apple Account when asked. Keep the previous iPhone nearby, unlocked and connected to Wi-Fi.‍

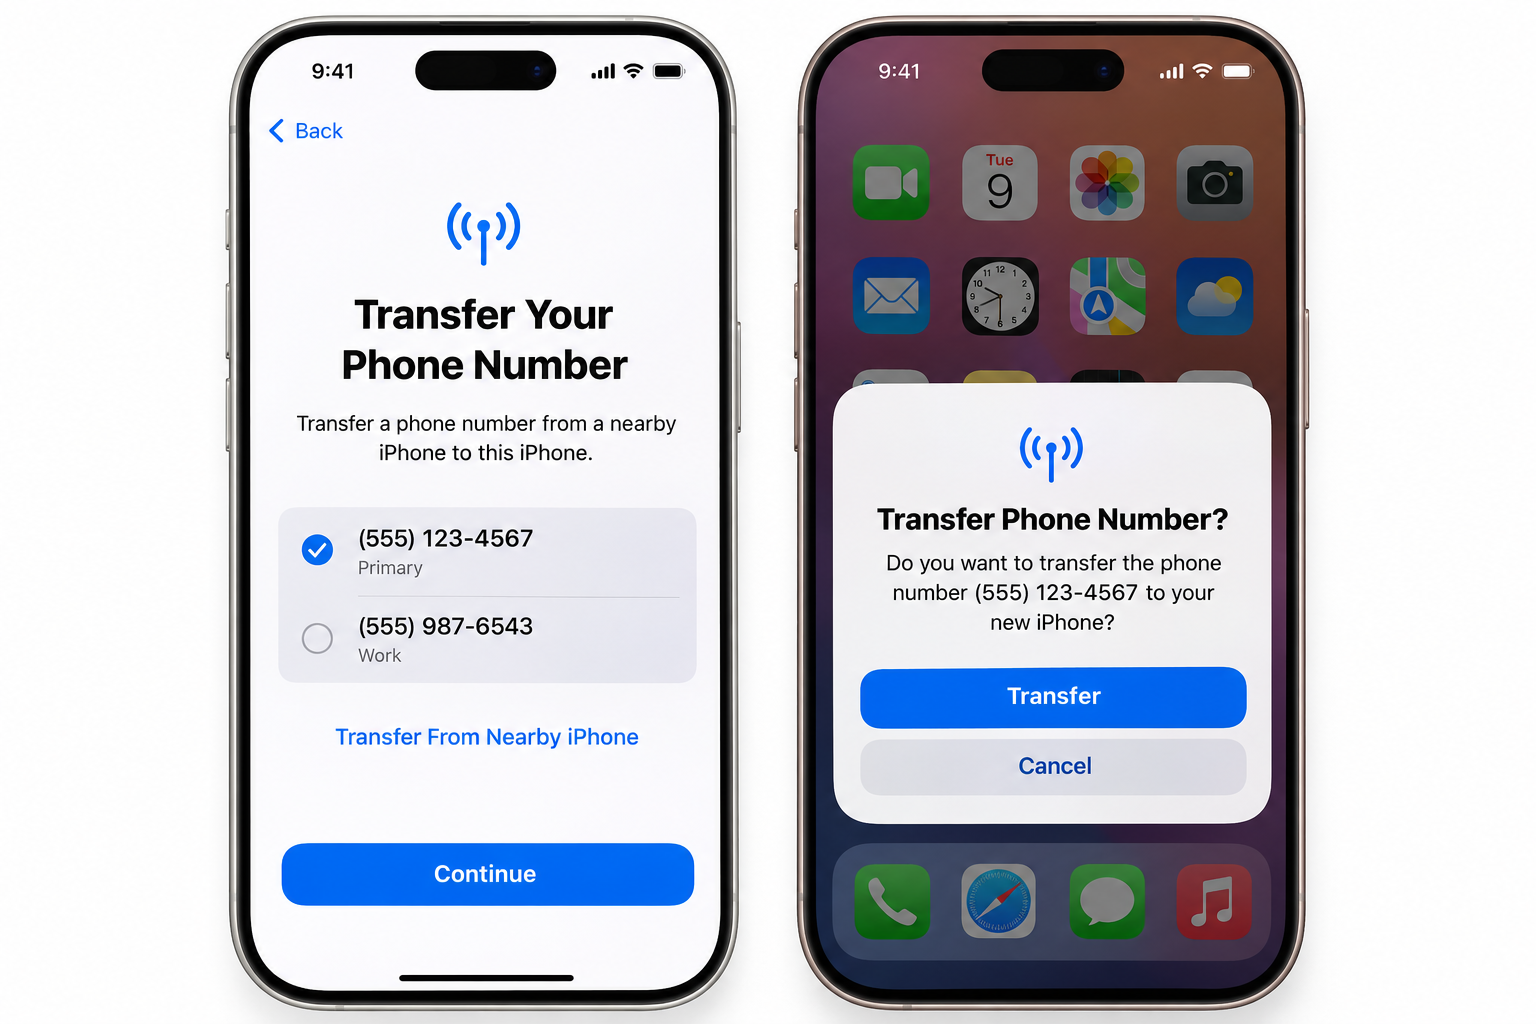
2. Reach the cellular screen. When the new iPhone asks you to set up cellular or to transfer your phone number, choose to transfer from your previous iPhone. If no list of numbers appears, tap Transfer From Nearby iPhone.

3. Choose the plan to move. If you have several numbers, pick the one you want to transfer.

4. Confirm on the previous iPhone. Follow the instructions that appear on it and tap Transfer. If it asks for a verification code, enter the code shown on the new iPhone.

Two iPhones confirming an eSIM Quick Transfer.

5. Wait for the plan to activate. Activating the plan on the new iPhone deactivates the SIM on the previous one, so don’t switch the old phone off in the middle of the transfer.

6. Finish with your carrier if asked. If a banner reads Finish Setting Up Your Carrier’s Cellular Plan, tap it and complete the transfer on your carrier’s website.

7. Test the line. Make a call from the new iPhone to confirm it has service.

Apple’s page doesn’t spell out the setup screens word-for-word, so the labels you see may vary slightly across iOS versions and carriers. The Quick Transfer buttons themselves, Transfer From Nearby iPhone and Transfer, match Apple’s instructions. If you transfer several numbers at once, make sure both iPhones run iOS 26 or later.

How to transfer an eSIM after setup is finished

If your new iPhone is already set up, you can move the eSIM from Settings by going to Cellular, then Add eSIM, and choosing a plan to transfer from your previous iPhone. This is the route to use if you skipped the prompt during setup or recently got a new iPhone. The same requirements apply: both iPhones running iOS 18.4 or later, Bluetooth and Wi-Fi on, and a carrier that supports Quick Transfer. To move an eSIM to a new iPhone this way:

1. Open Settings on the new iPhone and tap Cellular. In some regions, this menu is called “Mobile” or “Mobile Data”.

2. Tap Set Up Cellular or Add eSIM.

3. Choose a plan to transfer from another iPhone. If no list of numbers appears, tap Transfer From Nearby iPhone.

4. On the previous iPhone, follow the prompts and tap Transfer, or enter the verification code shown on the new iPhone if prompted.

5. Wait for the plan to activate on the new iPhone. This deactivates the SIM on the previous one.

6. If a banner reads Finish Setting Up Your Carrier’s Cellular Plan, tap it. You’ll be redirected to your carrier’s website to complete the transfer.

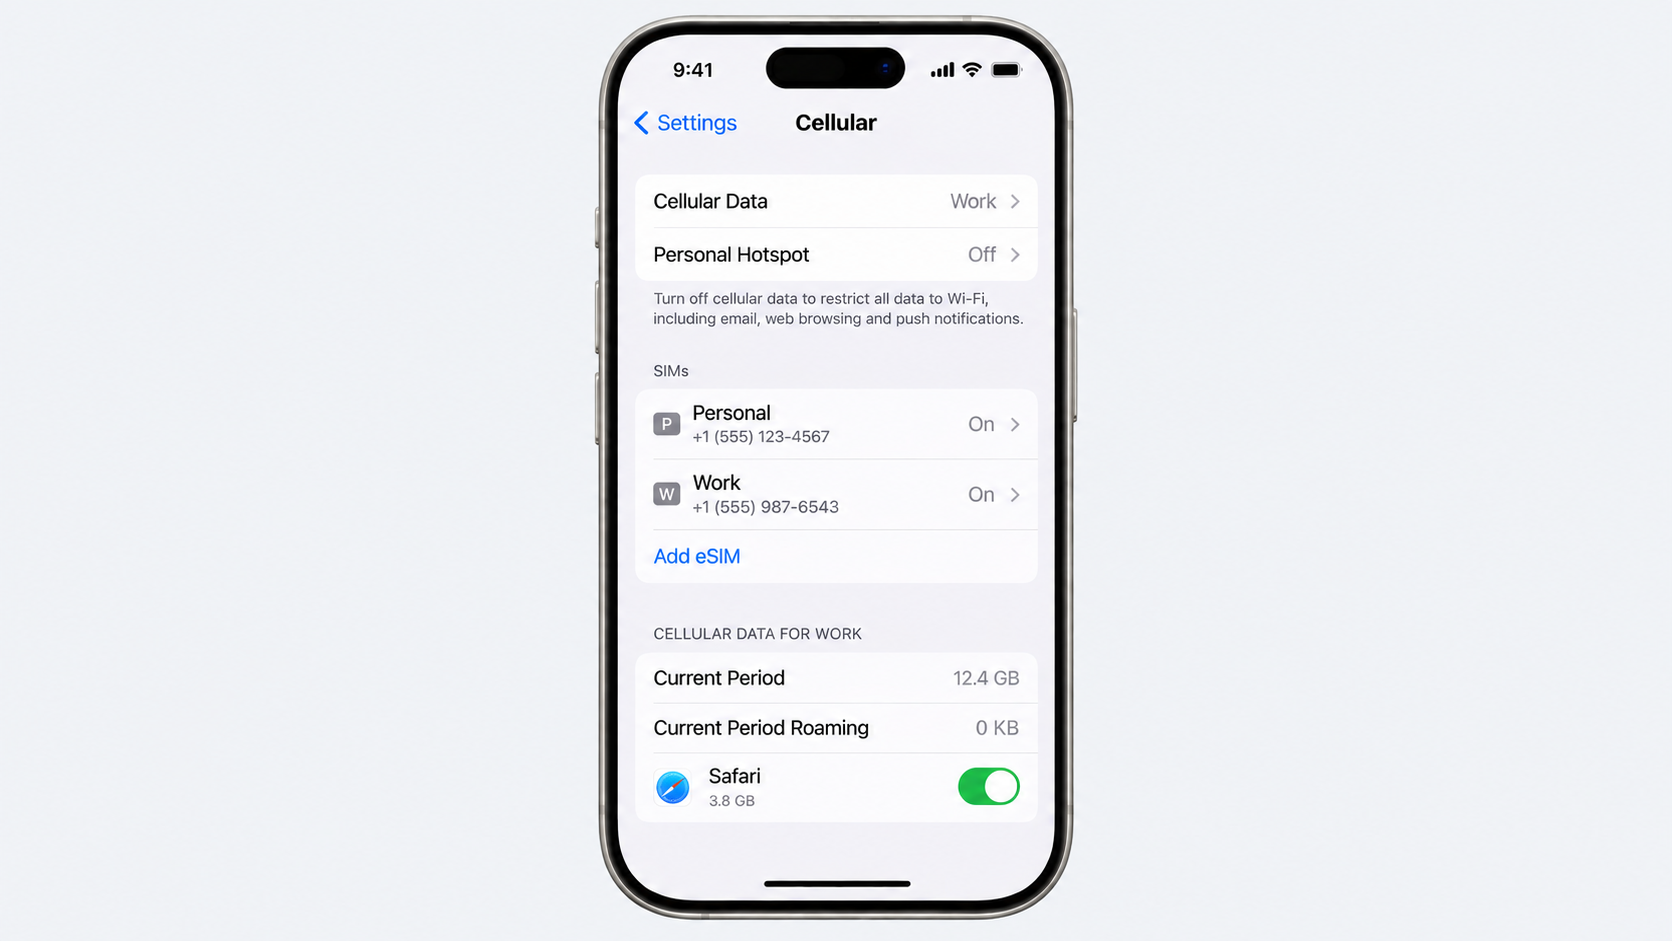
iPhone Cellular settings showing two eSIM plans.

When it’s done, return to Settings and Cellular to check that the plan is listed. If you have two plans on the same iPhone, both will appear there. Then call someone to confirm the line works.

Why is my eSIM transfer not working?

An eSIM transfer usually fails because your carrier doesn’t support Quick Transfer, or because one of the requirements isn’t met: Bluetooth is off, an iPhone is on an older iOS, or the phones aren’t signed in to the same Apple Account. Work through these checks in order, then fall back to your carrier’s QR code if the transfer still won’t start.

  • Carrier support: Quick Transfer only appears if your carrier supports it. Ask your carrier, or check its website, before you spend time troubleshooting.
  • Carrier lock: If the new iPhone is locked to a different carrier, it may not accept your plan. Ask your carrier to confirm the iPhone is unlocked.
  • Bluetooth off: Both iPhones need Bluetooth on and need to be close together.
  • iOS version mismatch: Both iPhones must run iOS 18.4 or later. Update the one that's behind.
  • Apple Account or lock screen: Both iPhones must be signed in with your Apple Account, and the previous iPhone must be unlocked with its passcode.
  • No Wi-Fi: Connect both iPhones to Wi-Fi, or use a hotspot, then try again.
  • Carrier step unfinished: If a banner says “Finish Setting Up Your Carrier’s Cellular Plan,” tap it to complete the transfer on your carrier’s web page.

If none of these fixes it, use the QR code route, which doesn’t depend on Quick Transfer. Ask your carrier for a QR code, then use one of these methods:

  • During setup: Tap Use QR code on the Set Up Cellular screen and follow the prompts.
  • After setup: Scan the code with the Camera app, then tap the Cellular Plan Detected notification. Your carrier may give you a confirmation code to enter.
  • Carrier link: On iOS 17.4 or later, tap the link your carrier sends, then tap Allow in the Activate New eSIM notification.
  • Manual entry: In Settings, tap Add Cellular Plan, then tap Enter Details Manually.

Some carriers also let you transfer your number in their own app. If the transfer still fails, contact your carrier: it can see what’s happening on your account.

Travel eSIMs versus carrier eSIMs when you switch phones

A carrier eSIM is linked to your phone number, so Quick Transfer or your carrier can move it to a new iPhone, whereas a travel eSIM is a data plan installed via a QR code and may not move at all. The difference matters if you’re changing phones before or during a trip. A QR code for a travel plan, which is the eSIM QR code iPhone owners scan to install it, is a profile for one device, not a number that travels with you.

Carrier eSIM Travel eSIM
What it is Your carrier plan, tied to your phone number and account A prepaid data plan from a separate provider
Phone number Keeps your number for calls and texts Usually data only, so it won't receive calls or texts to your number
Moving to a new iPhone Quick Transfer, if your carrier supports it, or a QR code from your carrier Depends on the provider, and many allow installation on one device only
Who to ask for help
Your carrier The travel eSIM provider
Before you delete it from the old iPhone Check the transfer worked and the new iPhone has service Check the provider's rules first, or you may lose the plan

‍

If you’re about to switch phones during a trip, don’t delete a travel eSIM from the old iPhone until you know whether the provider can reissue it. Some providers advise waiting to install a travel plan until you have the new phone. If you’re buying a plan for an upcoming trip, install it on the iPhone you’ll carry. The best eSIMs for international travel compares the options.

You can buy a travel eSIM on Grey in the Lifestyle tab of the Grey app and pay for it from your Grey balance. Availability depends on where you are and where you’re going. If you’re travelling to India, you can also send money from the US to India before you go. A Grey virtual card lets you pay for online purchases, such as eSIM plans, from your USD balance.

Grey is a financial technology company, not a bank: banking services are provided by licensed banking partners.

Frequently asked questions

Can I transfer an eSIM without contacting my carrier?

Yes, if your carrier supports eSIM Quick Transfer and both iPhones meet Apple’s requirements. You then move the plan from the new iPhone and approve it on the old one. If your carrier doesn’t support Quick Transfer, you’ll need a QR code or a transfer through its app.

Does transferring an eSIM delete it from my old iPhone?

It stops working there. Apple says activating the plan on the new iPhone deactivates your previous SIM, but its instructions don’t say whether the eSIM is removed from the old iPhone’s settings. Check that the new iPhone has service before you reset or sell the old one.

Can I transfer an eSIM from an iPhone to an Android phone?

Sometimes. Apple says that with iOS 26 and later, some carriers and select smartphone manufacturers support moving a SIM between Android and iPhone, in either direction. Otherwise, contact your carrier for a new eSIM.

What happens to my travel eSIM data plan when I switch phones?

It depends on the provider. A travel eSIM is activated via a QR code that many providers offer on one device only, so the plan may not transfer with the phone. Contact the provider before deleting it from the old iPhone and ask whether it can issue a new code.

Do I need Wi-Fi to transfer an eSIM?

Usually, yes. Apple lists a Wi-Fi network or hotspot among its requirements, though some eSIM-only iPhone models in certain countries can activate without one. Both iPhones also need Bluetooth on.

Can I have two eSIMs active on one iPhone?

Yes, on iPhone 13 and later, according to Apple’s Dual SIM guidance. Earlier models pair one eSIM with a physical SIM. Your iPhone uses only one cellular data network at a time.

Get a travel eSIM and a virtual card in one Grey account.

How to redeem an Amazon gift card

•

•

2 min read

A friend in the US sends you a $50 Amazon gift card by email. You want it on your account before the next sale ends, but the code looks like a random string of letters and numbers, and you're not sure where to apply it or whether it works outside the US. This guide shows how to redeem an Amazon gift card, how to fix the usual errors, and what changes if you're outside the US.

Go to amazon.com/gc/redeem, sign in, enter the claim code exactly as printed and select Apply to Your Balance. The value is added to your Amazon gift card balance and applies automatically to your next eligible order, so you don't need to enter the code again.

How do you redeem an Amazon gift card?

You redeem an Amazon gift card by entering its claim code at amazon.com/gc/redeem, or in the Amazon app under Gift Card Balance, and selecting Apply to Your Balance. A claim code is 14 or 15 characters, a mix of letters and numbers, and sits under a peel-off sticker or a scratch-off strip on the back of a physical card. Electronic cards have no code to type: you open the email, text or link and select Apply to your Amazon Account. Amazon’s own gift card redemption page is the place to start from either route.

You need an Amazon account first. If you were hoping to redeem an Amazon gift card without an account, that isn’t possible because Amazon stores redeemed funds in an account. Create one before you apply the code.

Redeem on a computer

  1. Sign in at amazon.com with the account that should receive the funds.
  2. Go to amazon.com/gc/redeem, or hover over Account & Lists, select Account, then Gift Cards and Redeem a Gift Card.
  3. Type the claim code exactly as printed.
  4. Select Apply to Your Balance.

Redeem in the Amazon app

  1. Open the Amazon app and tap the user icon in the bottom bar.
  2. Scroll to Gift Card Balance and tap Redeem Gift Card.
  3. Tap Scan Your Claim Code and point your camera at the card, or tap Enter Claim Code and type it.
  4. Tap Apply to Your Balance.

Redeem an electronic gift card

  1. Sign in to the Amazon account that should receive the funds.
  2. Open the email, text or link the card came in.
  3. Select Apply to your Amazon Account, and sign in again if Amazon asks.

If you haven’t redeemed a physical card by the time you check out, you can also select “Use a gift card, voucher, or promo code” on the payment page, enter the claim code, and select Apply.

If you give gift cards as well as receive them, you can buy, send and manage gift cards with Grey.

How to check your Amazon gift card balance

On a computer, go to Account & Lists, then Account, then Gift Cards to see your current balance; in the Amazon app, tap the user icon and look under Gift Card Balance. The balance is stored on your account, not on the card or the email, so it appears here once the code has been redeemed.

To check your Amazon gift card balance and see where it went, open the balance history. It lists the date each code was claimed, the last four digits of the code, and the items the balance paid for. That makes it the first place to look when Amazon says a code has already been redeemed, because the funds may already be sitting in your account.

Amazon applies the balance automatically to your next eligible order, so you don’t need to select it at checkout.

Why isn’t my Amazon gift card working?

An Amazon gift card most often stops working because the code is being applied to the wrong account or Amazon store, or because it has already been redeemed. Those two causes are the quickest to rule out, so check them first. Confirm which email address you’re signed in with, then open your gift card balance and balance history to see whether the code has already been claimed.

If neither explains it, find your symptom in the table below.

What you see Likely cause What to do
The code is rejected as invalid A typing mistake, or characters that look alike Re-enter the code slowly. A physical card's claim code has 14 or 15 characters, so count them. In the app, try scanning it instead
The code is rejected as already redeemed It was claimed earlier, possibly by you on another account Open Your Gift Card Balance and check the history for the last four digits. Then check any other Amazon accounts you own
The code is accepted but the balance isn't there You're signed in to a different account Sign out, sign in with the account you meant to use, and open the Gift Cards page
The card won't work on your local Amazon site A card issued for amazon.com only works on amazon.com Shop on amazon.com, or ask the sender for a card issued for your country's store
The code is a promotional certificate Promotional credits come with conditions, such as eligible items or an end date Read the terms shown with the offer before you rely on it
The sticker is scratched or the code is unreadable The card is damaged Look for the 16- or 30-digit serial number on the back and give it to Amazon customer service
You can't pay for a gift card with your balance
Gift card balance can't buy other gift cards Pay for the gift card with another payment method

‍

If you type a code by hand, copy it from the original email whenever possible, or use the camera scan in the app for a physical card. Both cut out typing mistakes. If the card still won’t work after these checks, contact Amazon customer service and have the card’s serial number ready.

One safety point: never read a claim code out to someone who contacts you first and asks for it. Anyone holding the code can spend the balance.

Can you combine multiple gift cards?

Yes. Every code you redeem is added to the same Amazon gift card balance on your account, so you don’t need to merge cards yourself. If you hold three cards, redeem each code in turn, and the balance page shows the running total, with each claim listed in your balance history.

Amazon applies that balance to your next eligible order automatically. If an order costs more than your balance, you can pay the difference with another payment method on your account.

Two limits matter once the money is in:

  • You can’t transfer it: A balance can’t be moved to another Amazon account, so a code redeemed on a family member’s account stays there.
  • You can’t take it back out: Amazon doesn’t let you cash out or resell a redeemed balance, and a gift card balance can’t be used to buy another gift card.

Because redeeming is a one-way step, hold off on redeeming a card you’re not sure you’ll spend. A card that’s still unredeemed can be sold, and this guide explains how to sell a gift card for cash instead.

Redeeming a US Amazon gift card from outside the US

A US Amazon gift card is tied to Amazon’s US store, so you apply the code on amazon.com, and the balance only pays for orders there. It doesn’t carry over to a local Amazon site such as Amazon.co.uk, and Amazon doesn’t let you move a redeemed balance from one country’s store to another. If someone sends you a US card while you’re abroad, check this before you redeem it, because the balance can’t be moved afterwards.

What the balance can buy depends on what amazon.com will deliver to where you live. Eligible items, shipping options, and import costs vary by country, so check the delivery options on a product page before relying on a card to pay for it. A gift card also can’t be turned into cash, so it’s the wrong tool if what you need is money in your bank account.

That situation comes up often in Nigeria, where a relative or client in the US sometimes sends an Amazon card because it's the simplest thing to hand over. If the goal is to get money to you, you can send money from the US to Nigeria instead, and spend it anywhere once it arrives.

If you’d rather shop on amazon.com without a gift card, you can spend online with a Grey virtual card. You create the card in the Grey app and fund it with your USD balance, and Amazon is one of the merchants where it works. Creating a card costs a one-time $5, with no monthly fee. Because amazon.com charges in dollars, the 2% plus $0.50 charge on non-USD card purchases doesn’t apply. If you start from naira, converting to dollars carries a 1% fee, capped at $6, plus the exchange-rate margin shown in the app before you confirm.

Frequently asked questions about how to redeem an Amazon gift card

Do Amazon gift cards expire?

Standard Amazon gift cards don’t carry an expiry date, but promotional credits and certificates can have an end date. Check the terms shown with the offer, and redeem any promotional code before that date.

Can you redeem an Amazon gift card without an Amazon account?

No. Amazon stores the value of a gift card as a balance on an account, so you need to sign in or create an account before you can apply the code. Once the balance is on your account, it applies to your next eligible order.

What happens if you enter the wrong claim code too many times?

Amazon can temporarily stop further attempts if a code keeps failing, and it doesn’t publish how many tries it allows. Stop after a couple of failed tries, check the code character by character, and contact Amazon customer service with the card’s serial number if you’re still blocked.

Can you use an Amazon gift card to buy another gift card?

No. A gift card balance can’t be used to buy another gift card, so you need another payment method for that purchase. Your balance still covers eligible physical and digital items.

Is it safe to buy a discounted Amazon gift card from a reseller?

It’s risky. Discounted cards sold on social media or by unknown sellers are a common route for scams, and the code may already be used or may have been obtained fraudulently. Buy from Amazon or from a retailer you trust, and check that the code works as soon as you receive it.

Can you redeem a US Amazon gift card on Amazon.co.uk?

No. A card issued for amazon.com only works on amazon.com, and Amazon doesn’t move a redeemed balance between country stores. To spend in pounds on Amazon.co.uk, you need a card issued for that store.

Open a Grey account and spend your balance online with a virtual card.

7 best peer-to-peer payment apps for sending money

•

•

2 min read

The best peer-to-peer payment apps let you send money to friends and family in seconds using a phone number, email address or username. Venmo, Zelle, Cash App and PayPal lead in the US, while Grey covers payments to people abroad. Compare fees, transfer limits, speed and whether the app works across borders.

Choosing a peer-to-peer payments app should be simple, but the right option depends on who you are paying and where they live. An app that works well for sending money to a friend in the US may not help when you need to pay someone abroad. Fees, transfer limits, and how quickly the money arrives can also vary.

Some apps are designed for local payments, while others offer ways to send money internationally. Before choosing one, consider whether you need free bank transfers, instant payments, or a way to send money across borders without paying more than necessary.

This guide compares seven peer-to-peer payment apps, including their key features, costs, and limitations, so you can choose the right option for your needs.

What is a peer-to-peer payment app?

A peer-to-peer payment app is an app that lets you send money directly to another person using a linked bank account or debit card. Instead of withdrawing cash or exchanging bank details, you can often pay someone using their phone number, email address, or username. Apps like Venmo, Cash App, and PayPal make everyday payments easier, from paying friends back to sharing household bills.

The main difference between a peer-to-peer payment app and a regular bank transfer is how you send the money. With a payment app, you can often select a contact and send funds in a few taps. A bank transfer usually requires the recipient’s bank details, such as their account number and bank name. However, both methods can move money between bank accounts, depending on the service.

Not every app supports the same payment methods or locations. Some focus on payments within the US, while others offer international transfers. Before choosing an app, check its fees, transfer limits, processing times, and whether it supports the country where your recipient lives.

The 7 best peer-to-peer payment apps

From instant transfers to international payments, these seven peer-to-peer payment apps offer different features for sending money to friends, family, and other people.

  1. Grey
  • Best For: Freelancers, remote workers, and expats needing international multi-currency accounts.
  • Fees: Free to receive domestic USD/EUR/GBP bank transfers; a 1% fee applies to auto-convert funds into local African currencies (like NGN or KES). Outgoing international wire fees vary by destination network.
  • Limits: Transaction and daily limits fluctuate dynamically based on user identity verification tier and the specific source currency channel (often starting around $2,000 to $5,000 daily).
  • Speed: Local wallet swaps are instant. International outgoing transfers generally take 1 to 3 business days depending on the receiving country's banking rail.
  1. Venmo
  • Best For: Casual, social expense splitting among friends.
  • Fees: Free for standard bank/debit transfers. A 3% fee applies if funded via credit card, and a 1.75% fee (minimum $0.25, maximum $25) applies for instant debit card cash-outs.
  • Limits: A rolling weekly limit of $4,999.99 for person-to-person payments after completing identity verification.
  • Speed: Standard bank transfers take 1 to 3 business days, while instant transfers to a linked debit card take under 30 minutes.
  1. Zelle
  • Best For: Rapid, secure bank-to-bank domestic transfers.
  • Fees: 100% Free. Neither Zelle nor its partner retail banks charge fees for standard or instant P2P movement.
  • Limits: Limits are determined directly by your participating bank, but typically hover around $500 to $2,500 daily for consumer checking accounts.
  • Speed: Instant. Funds pass directly between integrated bank accounts within minutes.
  1. Cash App
  • Best For: Combined peer transfers, high-yield savings, and micro-investing.
  • Fees: Free for standard P2P transfers. A 3% fee applies for credit card funding, and a 0.5% to 1.75% fee applies for instant cash-outs.
  • Limits: Up to $7,500 per week for sending and an unlimited receiving capacity once basic account verification is completed.
  • Speed: Standard wallet withdrawals take 1 to 3 business days, while instant debit card transfers execute in minutes.
  1. PayPal
  • Best For: High-value transactions, online shopping, and commercial buyer/seller fraud protection.
  • Fees: Free for domestic US "Friends & Family" transfers funded by a bank balance or debit card. Credit cards incur a 2.9% + fixed fee. Commercial "Goods & Services" transactions cost the seller 2.99% + $0.49.
  • Limits: Verified accounts can send up to $60,000 per transaction, with no cumulative daily or weekly caps.
  • Speed: Standard balance withdrawals take 1 to 3 business days, while instant debit card withdrawals take under 30 minutes for a 1.75% fee.
  1. Apple Cash
  • Best For: iPhone users seeking seamless integration inside iOS Messages.
  • Fees: Free for standard balance clearance. A 1.5% fee (minimum $0.25, maximum $15) applies if you opt for an instant debit card cash-out.
  • Limits: Users can send up to $10,000 per transaction and a maximum cumulative cap of $10,000 within any rolling 7-day period.
  • Speed: Standard transfers land in your bank in 1 to 3 business days. Instant transactions update your external debit card balance within minutes.
  1. Google Wallet
  • Best For: Android users wanting cross-platform flexibility for tap-to-pay and peer transfers via Google Pay.
  • Fees: Free for standard bank account deposits. Instant cash-outs to a linked debit card require a 1.5% premium fee (minimum $0.31).
  • Limits: A standard cap of $5,000 per rolling 7-day period (or up to $10,000 for verified commercial profiles).
  • Speed: Standard ACH withdrawals complete in 1 to 3 business days, while instant debit card pushes process in minutes.

P2P payment apps comparison table

Each payment app has different fees, sending limits, and international payment options. Compare the costs of instant transfers and card payments, how much you can send, and whether you can use the app to pay people in other countries.

App Instant transfer fee Card funding fee Weekly sending limit International support
Grey 1% fee plus an exchange rate margin. Varies by currency and card type $3,000 Yes; supports global accounts and multiple currencies
Venmo 1.75% (minimum $0.25, maximum $25) Free for debit; 3% for credit cards $4,999.99 for verified accounts No; US only
Zelle Free; transfers are generally fast Not applicable; uses linked bank accounts Set by bank, often 2,500–5,000 No; US only
Cash App 0.5%–1.75% Free for debit; 3% for credit cards $7,500 for verified accounts Limited; US and UK
PayPal 1.75% (maximum $25) Free for US debit-funded P2P; credit card fees apply No weekly limit stated; up to $60,000 per transaction Yes; available in many countries, with conversion fees
Apple Cash 1.5% (minimum $0.25, maximum $15) No separate fee for eligible debit funding $10,000 No; US only
Google Wallet 1.5% (minimum $0.31) Free for debit cards $5,000 over a rolling seven-day period Limited; P2P sending depends on region

‍

Are peer-to-peer payment apps safe?

Peer-to-peer (P2P) payment apps are generally safe for sending money, but they are not free from risks. Scammers may trick you into sending money to the wrong person, and recovering it can be difficult once you approve the payment. Unlike some credit card purchases, transfers may not come with automatic purchase protection. Before sending money, double-check the recipient’s details and make sure you trust them.

Common scams include fake payment notifications, phishing messages, and claims that someone sent you money by mistake. Be careful when buying items from strangers, especially if they ask you to use a payment option that offers no buyer protection. You should also check Zelle transfer limits and your app’s rules before making large payments, as limits and protections vary by provider.

Another thing to consider is deposit insurance. Money held in a payment app is not automatically FDIC-insured in every case. Coverage depends on how the funds are held and the provider’s arrangements. The Consumer Financial Protection Bureau offers guidance on payment app risks and protecting your money.

How to pay someone in another country

Zelle and Venmo are useful for sending money within the US, but they are not designed for sending payments directly to recipients in most other countries. If you need to pay family, friends, or service providers abroad, you need a service that supports international transfers.

Grey lets you send USD to 170+ countries, giving you a way to pay recipients abroad without relying on a US-only payment app. You can choose the destination, enter the recipient’s payment details, and check the exchange rate and applicable fees before confirming the transfer.

For example, if you need to support family or pay someone in Mexico, you can send money from the US to Mexico directly to their Mexican bank account in pesos. Your recipient does not need a Grey account to receive the money. Transfer times and fees depend on the destination and funding method, so check the details before sending.

Frequently asking questions

1. What is the most popular peer-to-peer payment app?

Venmo and Cash App are popular choices for everyday payments in the US, while PayPal serves users in many countries. Zelle is widely used for sending money directly through participating banks. The best option depends on where you live, who you pay, and which apps they already use.

2. Which P2P app has no fees?

Zelle generally charges no fees for sending or receiving money, although your bank may apply charges. Venmo and Cash App offer free standard transfers to linked bank accounts, but instant withdrawals and credit card payments may cost extra. Check each app’s current fee schedule before sending money.

3. Can you use Venmo or Zelle internationally?

Venmo and Zelle are primarily designed for domestic US payments and generally cannot send money directly to international bank accounts. If you need to pay someone abroad, choose a service that supports your destination country, such as Grey, Wise, or Remitly.

4. What is the safest peer-to-peer payment app?

The safest option depends on how you send money and who receives it. PayPal offers purchase protection for eligible transactions, but not every personal payment is covered. Whichever app you choose, verify the recipient, protect your login details, and avoid sending money to strangers you cannot trust.

5. How much can you send on a P2P app?

Sending limits vary by app, account verification, bank, and payment method. Zelle limits are set by participating banks, while PayPal limits depend on account status and transaction details. Check your account’s current limits before making a large payment to avoid delays or declined transfers.

6. How do you send money to family abroad?

To send money to family abroad, choose an international payment service that supports their country and preferred payout method. Grey, Wise, and Remitly offer different international transfer options. Compare exchange rates, fees, delivery times, and available payment methods before choosing how to send the money.

Whether you’re supporting family, paying a supplier, or sending money to a friend overseas, Grey helps you send money abroad in minutes, so your money gets where it needs to go.

How to sell gift cards for cash in the US

•

•

2 min read

If you have a gift card you'll never use, selling it can help you turn that unused balance into cash. Whether you received an unwanted gift card, have leftover shopping credit, or simply need money for something else, there are several ways to sell gift cards in the US. Online gift card exchanges offer convenience, physical kiosks provide quick in-person transactions, and peer-to-peer marketplaces let you negotiate directly with buyers.

The amount you receive depends on the retailer, card balance, demand, and selling method. Some gift cards sell closer to their face value than others, so comparing offers before accepting one can help you get a better deal. Payout times also vary, ranging from immediate payment at some kiosks to several business days for online transactions.

Before choosing where to sell, check the platform's fees, payment options, and verification requirements. Be cautious with private buyers who ask for your card number or PIN before payment, as gift card scams can leave you with nothing.

This guide explains how to sell gift cards safely, compare payout options, and choose the method that best fits your needs.

Where can you sell gift cards for cash?

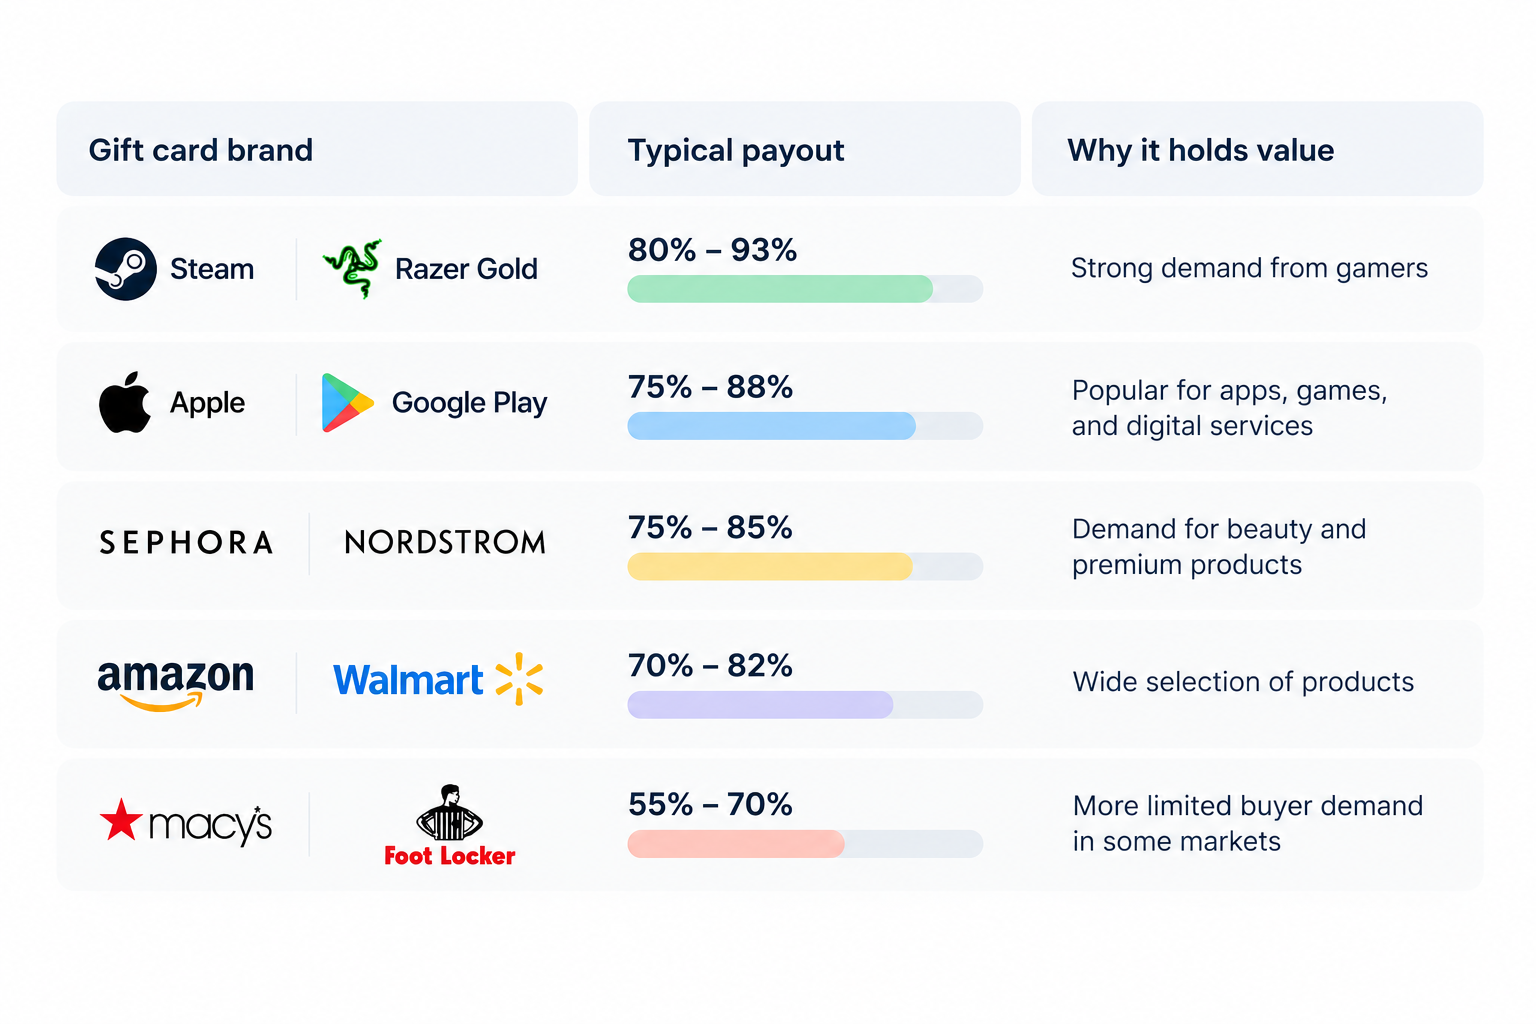
Typical payouts for selling gift cards range from 60% to 93% of the card’s face value, depending on the retailer, platform, and selling method. Understanding how digital gift cards work can help you choose the right selling method and protect your balance.

1. Dedicated gift card trading apps

Gift card trading apps typically offer around 70% to 85% of your card’s value. You submit your card details, receive an offer, and get paid after verification. Check the app’s fees, supported retailers, and payout methods before accepting an offer.

2. Direct cash-out websites

Specialised websites such as GiftCash may offer payouts of approximately 75% to 93% for eligible cards. Rates depend on demand, brand, and balance. Compare the final offer with other platforms, as the highest advertised rate may not apply to your card.

3. Peer-to-peer marketplaces

P2P marketplaces let you negotiate directly with buyers, with typical returns of 60% to 85% after fees. You may secure a better price, but fraud risks are higher. Use trusted platforms and never share your card's redemption code before payment is secured. If you also need to purchase or keep track of gift cards, buy and manage gift cards with Grey to explore your options.

What rate should you expect when selling gift cards?

The rate you receive depends on the gift card brand, how many buyers want it, and how easily the card can be resold. Amazon, Apple, and Steam gift cards often have strong demand, while cards for less popular or region-specific retailers may sell for less.

A card's resale value is not the same as its face value. If your gift card is worth $100 and a buyer offers 80%, you will receive $80 before any additional fees.

Typical gift card resale rates by brand

Chart of gift card payout rates by retailer.

‍

Why do gift card rates differ?

  • Brand popularity: More buyers usually mean better resale rates.
  • Ease of resale: Cards that sell quickly may attract higher offers.
  • Card format: Physical cards with receipts may be easier to verify than some digital codes, depending on the buyer.
  • Country and currency: US-issued cards may attract stronger demand than cards restricted to other regions.
  • Fees and verification: Platforms may reduce their offers to cover processing costs and fraud risks.

How to sell a gift card step by step

Follow these steps to turn an unused gift card into cash while reducing the risk of delays, rejected submissions, or scams.

1. Check your balance: Visit the retailer's official website to confirm the remaining balance and make sure the card has been activated.

2. Confirm the card details: Check the brand, issuing country, currency, denomination, and whether you have a physical card or digital code.

3. Keep your proof of purchase: Save the original receipt, activation slip, or purchase confirmation email. Some buyers require proof to verify the card's origin.

4. Compare offers: Check the current payout rate on reputable trading platforms and compare the final amount you will receive after fees.

5. Submit your card: Create an account, select the correct card category, and upload clear images or enter the digital code through the platform's official submission process.

6. Wait for verification: The buyer checks the card's validity and balance. Track your transaction and respond to requests for additional information.

7. Receive your payout: Once approved and marked as paid, withdraw the money using an available payment method. Keep your transaction receipt for your records.

Important: Never share your gift card code with an unverified buyer or send it through public comments or unofficial messages.

How to avoid gift card scams

Selling gift cards for cash can be convenient, but a careless transaction can leave you with an empty balance and no payment. Knowing the warning signs can help you protect your money.

1. Check for drained cards: Confirm your gift card balance on the retailer's official website before trading. Submit it promptly through a trusted platform, as anyone who obtains the code may redeem the balance first.

2. Avoid fake buyers: Be cautious of social media traders promising unusually high rates or instant payments. Use reputable platforms with clear verification procedures and buyer protection where available.

3. Watch for overpayment scams: Never refund an alleged excess payment based on a screenshot or an unverified check. Confirm that funds have actually cleared before releasing your card.

4. Keep your PIN secret: Never share your redemption code, PIN, or photos showing the complete card details with an unverified buyer. Once someone redeems the balance, recovering your money may be difficult.

Always verify the buyer, confirm payment independently, and keep transaction records.

Getting your payout when living abroad

Selling gift cards through US platforms can be useful, but receiving your money while living abroad requires the right payment method. You may not need a US bank account if the platform supports international payouts or allows you to withdraw through an eligible financial service. Before selling, confirm the available payout currencies, withdrawal methods, and account requirements.

If you live in Nigeria, for example, you may want to receive USD and convert it to naira when you need local spending money. Grey supports cross-border transfers, and you can explore how to send money from the US to Nigeria to understand the available transfer options. Check the applicable fees, exchange rate, and delivery time before moving your funds.

You can also open a USD account with Grey to explore options for receiving and managing dollars, subject to eligibility and availability. Keeping funds in USD before converting them may help you choose when to exchange, but always compare the total costs and withdrawal options first.

Frequently asked questions

1. What is the best place to sell gift cards?

The best place to sell gift cards depends on your preferred currency, payout speed, and the card you own. Platforms such as Cardtonic, GiftCardsToNaira, GiftCash, and Gameflip offer different options. Compare their rates, fees, supported brands, and payment methods before choosing where to sell.

2. How much can you get for a gift card?

The amount you receive depends on the card’s brand, value, demand, and resale platform. Some gift cards may sell for 60% to 93% of their face value, but rates vary. Check current offers before selling so you understand how much you will receive.

3. Can you sell a partially used gift card?

You may be able to sell a partially used gift card, depending on the platform’s rules. The marketplace must support the card and allow its remaining balance to be verified. Check the requirements first, and disclose the exact balance to avoid disputes with the buyer.

4. How long does a gift card payout take?

Gift card payout times depend on the platform, verification process, and payment method. Some services process approved transactions quickly, while others may take several hours or longer. Before selling, check the estimated processing time and confirm whether additional identity or card verification is required.

5. Is selling gift cards legal?

Selling gift cards you legitimately own is generally legal, but the rules depend on your location, the card issuer’s terms, and the transaction. Avoid selling cards obtained through fraud or using platforms that facilitate illegal activity. Check local regulations and the marketplace’s terms before completing a sale.

6. How do you sell a US gift card from outside the US?

To sell a US gift card while living abroad, choose a reputable platform that accepts your card brand and country of residence. Check its exchange rate, fees, verification requirements, and payout options. Confirm that you can withdraw the proceeds in your preferred currency before submitting your card details.

What is the currency of Italy? Euro symbol and code

•

•

2 min read

The currency of Italy is the euro, identified by the code EUR and the symbol €. If you are planning a trip to Rome, shopping in Milan or sending money to someone in Italy, understanding the local currency can help you manage your money and avoid unnecessary charges.

Imagine arriving in Italy, ready to explore its historic streets, enjoy a meal at a local restaurant or pay for your hotel. You will need euros for everyday purchases, whether you are paying by card or carrying cash. Euro banknotes come in different denominations, while coins are available in cents and euros. Although cards are widely accepted, having some cash can be useful for smaller purchases and places that prefer cash payments.

Currency exchange fees, ATM charges and your bank's foreign transaction fees can increase your spending without you noticing if you always have to convert. If you need to send money to Italy, exchange rates and transfer fees affect how much your recipient receives. This guide explains the Italy currency, its symbol and code, and practical ways to spend and transfer money while keeping costs down.

What is the currency of Italy?

Italy uses the euro (€) as its official currency. Whether you are visiting Rome, shopping in Milan or paying for accommodation in Venice, you will use euros for everyday transactions. The currency is shared by many European countries, making travel and payments across participating nations more convenient.

The euro’s official currency code is EUR, while its symbol is €. You will see the symbol before prices in many Italian shops, restaurants and online stores. One euro is divided into 100 cents. Euro banknotes are available in different denominations, alongside coins ranging from one cent to two euros, which you can use for smaller purchases.

The European Central Bank (ECB), working with the national central banks of eurozone countries, is responsible for monetary policy and maintaining price stability across the euro area. It helps manage the euro’s value by setting key interest rates and using other monetary policy tools.

Italy is a member of the eurozone, the group of European Union countries that use the euro as their official currency. This means you can generally use the same currency when travelling between Italy and other eurozone destinations, although your bank may still charge fees for certain transactions.

Euro notes and coins in Italy

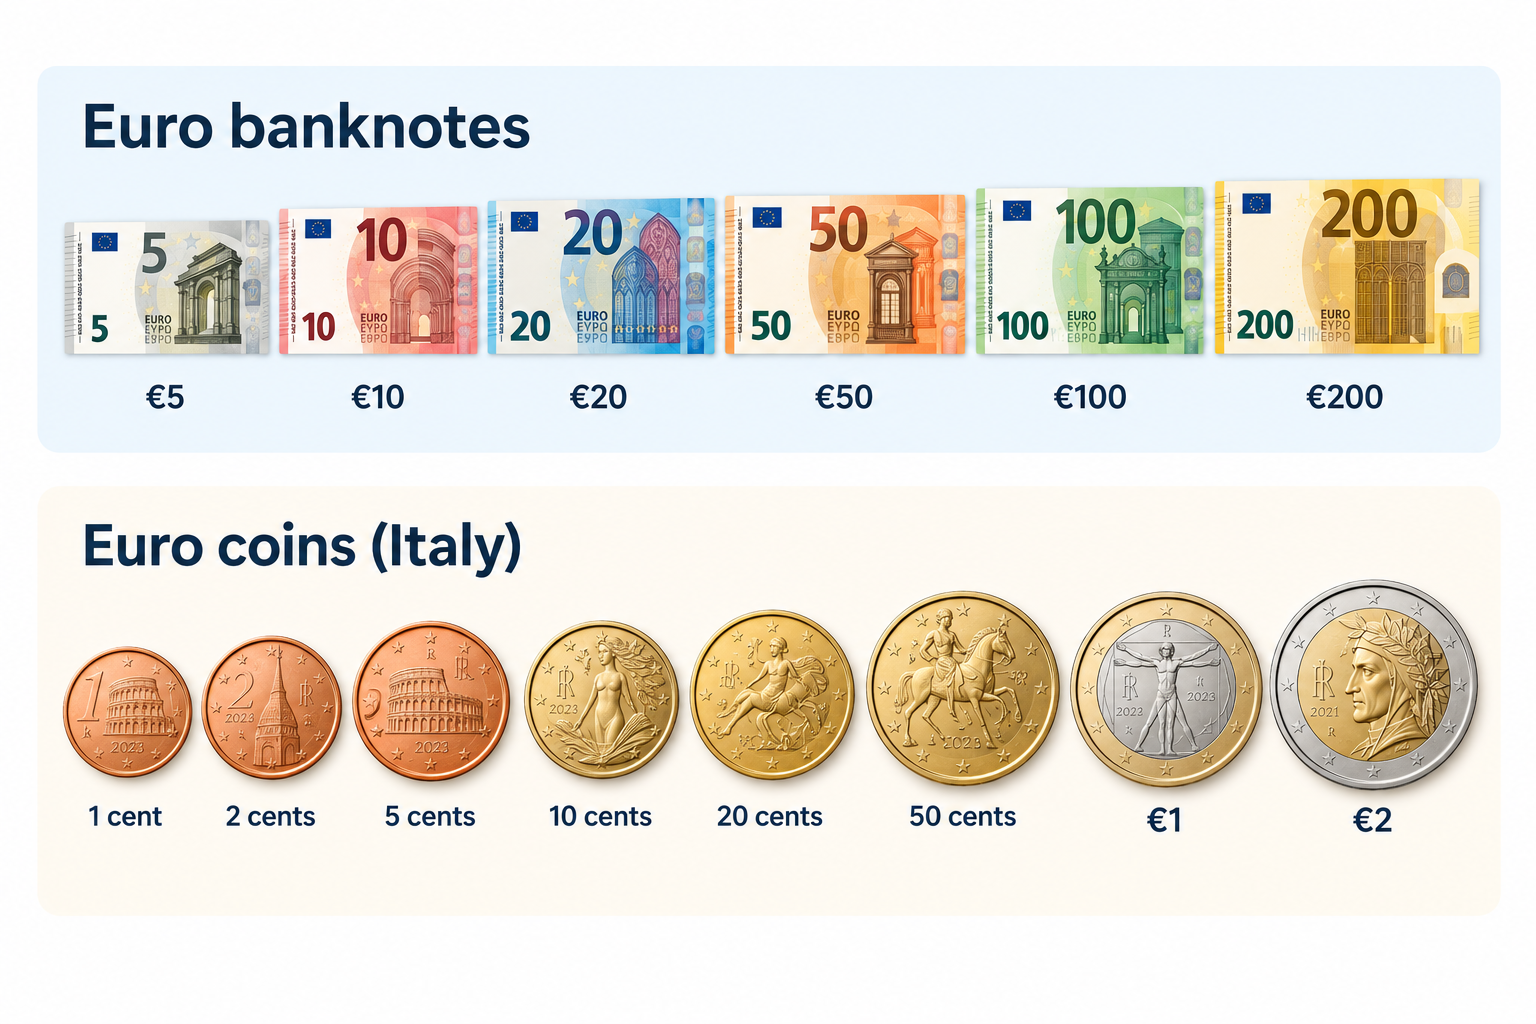
When you visit Italy, you will use euro banknotes and coins for everyday purchases, from buying coffee to paying for meals and transport. Euro banknotes come in denominations of €5, €10, €20, €50, €100 and €200. Although the €500 note is no longer issued, existing notes remain valid. Banknotes share common designs across the eurozone, featuring architectural styles from different periods in European history.

__wf_reserved_inherit

Euro coins come in eight denominations: 1, 2, 5, 10, 20 and 50 cents, plus €1 and €2. Each coin has a common European side and a national side featuring designs selected by its issuing country. All euro coins can be used across the euro area.

Italy’s national coin designs reflect its rich artistic and cultural heritage. The €1 coin features Leonardo da Vinci’s Vitruvian Man, his famous drawing illustrating the proportions of the human body. Other denominations showcase Italian landmarks and masterpieces, including Dante Alighieri, the Colosseum and Sandro Botticelli’s Birth of Venus. These designs celebrate Italy’s contribution to European art and history. The European Central Bank oversees euro banknotes and contributes to maintaining confidence in the currency across participating countries.

Should you pay by cash or card in Italy?

When travelling around Italy, you can pay by card at most hotels, restaurants, supermarkets and shops in major cities, where Visa and Mastercard are widely accepted. However, keeping some euros in your wallet can help when shopping at local markets, making small purchases or visiting places where card payments are unavailable. Before travelling, check your bank’s foreign transaction fees so you know how much you could spend on charges.

You are not expected to tip everywhere in Italy, as tipping is not compulsory, but you can leave a small amount or around 5–10% when you receive particularly good service. Check your bill for any service charge before deciding what to leave.

To manage your spending digitally, you can use a Grey virtual card for eligible purchases in euros, including online bookings and payments at merchants that accept Visa. Depending on your card setup, you may also be able to add it to Apple Pay or Google Pay for contactless payments. Check applicable fees and currency conversion rates before spending.

How to get Euros for a trip to Italy

Before travelling to Italy, decide how you will access euros for meals, transport, shopping and accommodation while keeping exchange costs low. You can exchange money before departure, withdraw euros from ATMs in Italy or use a payment card that supports euro spending.

ATMs operated by established banks are convenient for withdrawing cash, but check your bank’s withdrawal charges and any fee displayed by the ATM before confirming. Exchange bureaux are another option, although you should compare exchange rates and commissions to avoid paying more than necessary.

To avoid unnecessary conversion costs, choose euros rather than your home currency whenever an ATM or card terminal offers dynamic currency conversion. This allows your card provider to handle the conversion instead of accepting the machine’s potentially unfavourable rate. You should also check whether your bank charges foreign transaction fees.

A Grey virtual card offers another way to pay for eligible purchases in euros. Check Grey’s card fees and exchange rates, and compare them with your bank’s charges to find a cost-effective way to spend while travelling.

Also read: Italy digital nomad visa: Requirements, costs and process

How to send money to Italy

Whether you are supporting a family in Italy, paying tuition fees or covering accommodation and other expenses, you need a reliable way to send money in euros without losing track of exchange rates and transfer costs. Grey makes cross-border transfers easier by allowing eligible users to send money from Nigeria to European bank accounts in EUR. You can fund your Grey account, review the available exchange rate and fees, and transfer euros directly to your recipient’s bank account.

Grey is also a multi-currency platform, allowing you to hold and convert supported currencies to manage international payments in one place. This can be useful when you earn in one currency but need to pay expenses in euros. Before confirming a transfer, check the live exchange rate, applicable fees and the final amount your recipient will receive.

Frequently asked questions about the currency of Italy

1. Does Italy use the euro or the lira?

Italy uses the euro (€) as its official currency, not the Italian lira. The lira was replaced by the euro in 1999 for accounting purposes, with euro banknotes and coins entering circulation in 2002. Today, you need euros to pay for everyday purchases, transport, meals and accommodation in Italy.

2. What is the euro symbol and code?

The euro symbol is €, and its official three-letter currency code is EUR. You will see these used on Italian price tags, restaurant menus, receipts and online bookings. One euro is divided into 100 cents. When exchanging money or sending payments to Italy, use EUR to identify the currency correctly.

3. Can you use US dollars in Italy?

US dollars are not generally accepted for everyday purchases in Italy because the euro is the official currency. You should exchange dollars for euros or withdraw euros from an ATM. Some tourist businesses may accept other currencies, but their exchange rates may be unfavourable. Paying in euros usually makes costs easier to compare.

4. Is it better to pay with cash or card in Italy?

Cards are widely accepted in Italian cities, hotels, restaurants and shops, making them convenient for everyday spending. However, carrying some euros is useful for markets, small purchases and places that do not accept cards. Check your bank's foreign transaction fees and choose euros rather than your home currency when prompted at payment terminals.

5. How much cash should you take to Italy?

The amount depends on your travel plans, accommodation and spending habits. For many travellers, carrying around €50–€100 for initial expenses and small purchases is a reasonable starting point, while using a card for larger payments. You can withdraw additional euros as needed, but check ATM charges and your bank's withdrawal limits first.

6. How do you send money to Italy?

You can send money to Italy through a bank transfer or an international money transfer service. Compare exchange rates, transfer fees and delivery times before choosing. Grey supports eligible cross-border transfers and multi-currency services, allowing users to send money in euros to supported destinations. Check availability, fees and recipient requirements before confirming your transfer.

Arrow (up)

Back to top