How to create US and UK bank accounts as a migrant worker in Brazil

Olayoyin Olorunmota

TABLE OF CONTENT

SHARE THIS POST

Brazil, the largest of all 33 Latin American countries, is a popular destination for immigrants, housing over 1.7 million immigrants as of 2022.  For migrant workers who’ve made Brazil their home, managing finances can sometimes be a hassle.
Fret not, there’s good news. Opening US and UK bank accounts can make your financial life much smoother.

This guide will show you how to use Grey to set up US and UK virtual bank accounts, helping you to send, receive, and manage money effortlessly as a migrant worker in Brazil.

Why should you open a US or UK bank account as a migrant worker?

Having US and UK bank accounts comes with several advantages:

  • Receive payments globally: Get paid in USD or GBP, whether you're working remotely or freelancing.
  • Better exchange rates: Avoid the hidden fees and poor exchange rates associated with traditional money transfer services.
  • Easier transactions: Make seamless payments for international services, subscriptions, or goods.

With Grey, you can enjoy all these benefits without visiting a physical bank branch.

Also read: How to manage multiple currencies as an expatriate in Mexico using Grey

Step-by-step guide to opening US and UK bank accounts w Grey

The process is pretty straightforward. Here’s how you can get started:

1. Sign up for Grey

Creating an account with Grey is simple, requiring only a few personal details. Here’s what you need to do.

  • Visit Grey.co: On your browser, enter Grey.co and click on “Get started – it’s free.”
__wf_reserved_inherit
  • Choose your country: Select your current country of residence. This helps Grey tailor the setup to your location.
__wf_reserved_inherit
  • Enter your details: You’ll be prompted to provide your full name, email address, and phone number, then create a secure password.
__wf_reserved_inherit
  • Verify your email: Grey will send a one-time password (OTP) to your email address. Simply enter the code on the site to complete this step.
__wf_reserved_inherit

Once you’re set-up, you’re ready for identity verification — a step required for secure access to financial services.

2. Verify your identity for secure access

Here’s what you’ll need to provide:

  • Government-issued ID: A valid passport or national ID card is required. Make sure it’s clear and up-to-date.
  • Proof of address: A recent utility bill or bank statement will verify your location. Grey uses this document to confirm your residency.
  • Submit your documents for review: Once uploaded, Grey will review your documents, a process that typically takes a few business days. Clear and accurate documentation speeds up approval.

3. Access your US and UK bank accounts

  • Once your identity is verified, log in to your Grey account.
  • Navigate to the “Accounts” section and select “Create Account.”
  • Choose the currency (USD for a US bank account or GBP for a UK account).
  • Your virtual bank account details, including your account number and routing number, will be generated instantly.

Also read: How to manage multiple currencies as an expatriate in Brazil using Grey

How to use your US and UK bank accounts

Now that your accounts are set up, here’s what you can do:

Receive payments

Share your account details with employers, clients, or family abroad to receive payments in USD or GBP directly into your Grey account.

Convert to local currency

Use Grey to convert your USD or GBP to local currencies like Mexican pesos, Colombian pesos, or Brazilian reais, depending on the country you’re in.

Navigate to the “Convert” section in the app, select the currency pair, and confirm the transaction. Funds are instantly transferred to your local wallet.

Withdraw funds

Transfer your funds to a local bank account or mobile money service for easy access to cash.

Benefits of using Grey as a migrant worker in Brazil

  • No hidden fees: Transparent pricing ensures you keep more of your money.
  • Competitive exchange rates: Maximise your earnings when converting currencies.
  • Fast transactions: Receive and transfer money instantly, without delays.
  • Global accessibility: Use the Grey app to manage your finances from anywhere, anytime.

Tips for managing finances as a migrant worker

  • Budget wisely: Allocate your income across savings, daily expenses, and remittances to your family.
  • Track exchange rates: Use Grey’s real-time rates to convert funds at the best times.
  • Secure your accounts: Enable two-factor authentication (2FA) for added security.

Simplify banking across borders with Grey

Life as a migrant worker in Brazil doesn’t have to be difficult. With Grey, you can create US and UK bank accounts in minutes, receive payments globally, and manage multiple currencies.

Create your Grey account today or download the app to enjoy inclusive global banking, designed for you to carry your dreams across borders.

Last updated:

June 15, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

How to view your transaction limits on your Grey account

2 min read

When making bulk transfers from your bank accounts or financial services like Grey, you need to be wary of your transaction limits.

Transaction limits are the maximum amount of money you can either withdraw, transfer, deposit, or spend in a single transaction. Sometimes, it could be how much you can spend in a day, week, or month.

On Grey, there are limits on how much you can transact with too. This post will show you how to view these limits and share helpful information about account limits.

How Do Bank Account Limits Work?

Banks and financial institutions usually set bank limits. This is why it varies based on account levels, the country, and transaction methods. So, for example, a student account would have a significantly lower limit than a Tier 3 business bank account would.

Once this amount is set, you can only transact within the limit. Once you exceed that limit, the bank won’t be able to process any further transactions until it resets.

In unique cases where the transaction amount is alarming, financial institutions are required to notify regulators as part of the anti-money laundering measures.

Why Do Banks and Financial Services Have Transaction Limits?

Grey account transaction limits are important because they help protect the customer and the bank from any potential fraud cases. When there’s a limit, there’ll be a lesser loss incurred.

Limits are also a security measure to prevent money laundering. If there’s a maximum threshold, these services can better comply with regulations and prevent any illegal activities around finances.

How to View Your Grey Account Transaction Limits

Transaction limits on Grey vary based on deposits, withdrawals, and card spend limits. You can currently spend up to $10,000 on your Grey virtual card at a maximum of $ 2,500 per transaction.

For withdrawals and deposits, there are daily and monthly limits. Here’s how to check how much you have left on your Grey account;

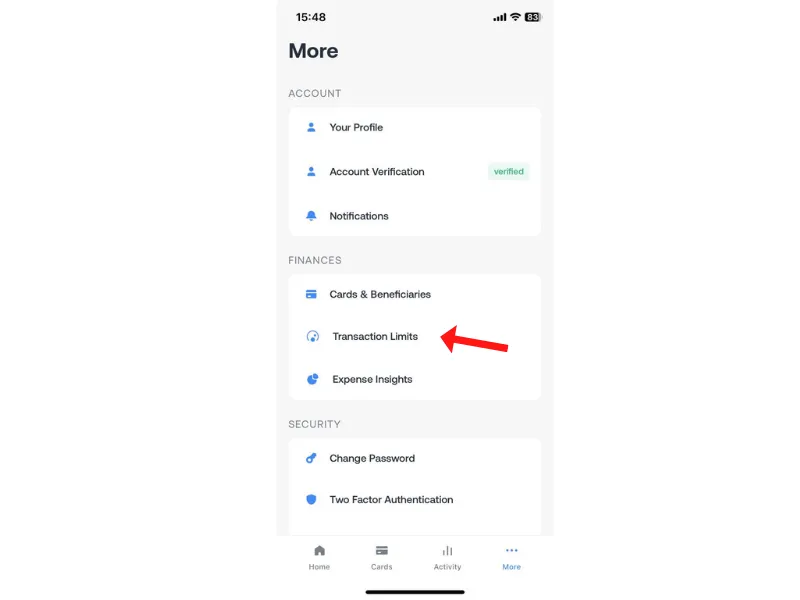
  • Log in to your Grey Mobile app
  • On the navigation bar located at the bottom of your screen, tap on “More”
  • Tap on “Transaction Limits”
grey-account-transaction-limits
  • Choose to view either “Withdrawal limits” or “Deposit limits”

You’ll see a breakdown of your daily and monthly account limits. You’ll also see how much you have left to exceed that limit.

Can I Increase My Transfer or Deposit Limit on Grey?

Unfortunately, at this time, you cannot increase your deposit or spend limit on your Grey account. You can, however, take advantage of the daily limit reset to split your transactions across several days.

Fortunately, the limits on Grey are much higher than what you’d get on your domiciliary bank account. If you’d like to know more about how Grey foreign accounts work, you can always explore our guides and product updates here.

Why your deposits and incoming transactions on Grey are pending

2 min read

Occasionally, when you receive money from a client, business partner, or loved one, you might get a notification asking you to verify that transaction. During this period, your funds will be allocated to a pending balance. We’ve received a lot of questions concerning why this is a requirement for some transactions, especially deposits. 

That’s why in this post, we’ll be clarifying what a pending balance means, why certain transactions require verification, and how you can access your funds once they are in your pending balance. 

What is a pending balance?

A pending balance is a type of wallet designed to temporarily hold funds received from unverified transactions on Grey. Unfortunately, this means that you won’t be able to access the funds in this balance. However, you can see how much you’ll receive once you verify this transaction. 

The real reasons why your transactions are in a pending balance

With the rise in fraud cases and chargebacks, there are now new regulatory requirements from the governing bodies of financial institutions. In line with these requirements, we have to prioritize the safety and security of your financial transactions (both inflow and outflow).

So, if there’s an inconsistency between your account name and the payment details, we are required to verify that the transaction is, in fact, legitimate. This is a safety and precautionary measure to ensure that we;

  • Verify that all funds received by our users are legitimate
  • Protect you from any potential fraud case by verifying that your funds are legitimate
  • Reduce the risk of any fraudulent activity that can harm you in the future. Some examples are money laundering, identity theft, and online scams.
  • Provide safe services for everyone and serve as a deterrent against potential fraudsters.
  • Are a responsible financial institution that’ll serve you for a long time.

How to verify a pending transaction on Grey

If you do get a prompt to verify your pending transaction, don’t worry. It’ll only take a few minutes. Here’s what you need to do; 

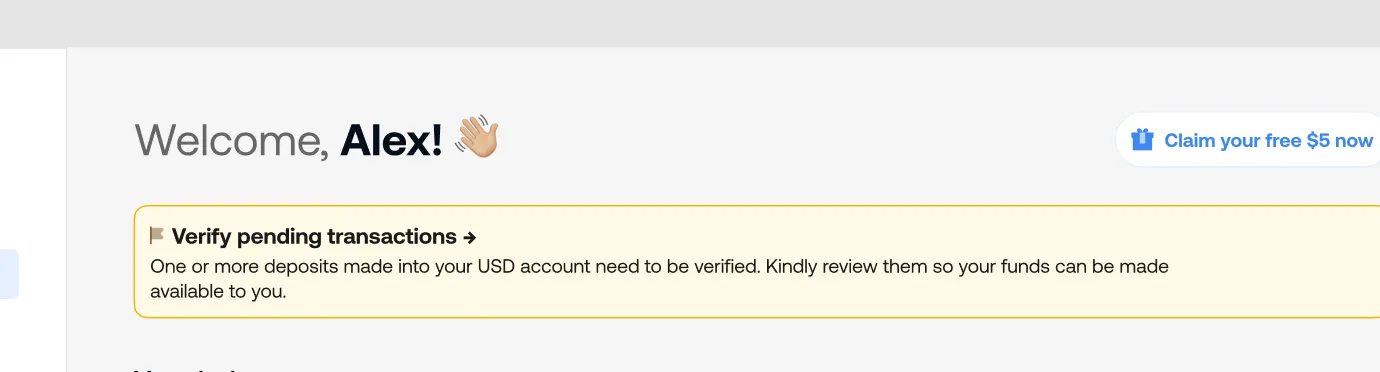
  • Login to your Grey app
  • Tap on the message asking you to verify a transaction.
verify-pending-deposit
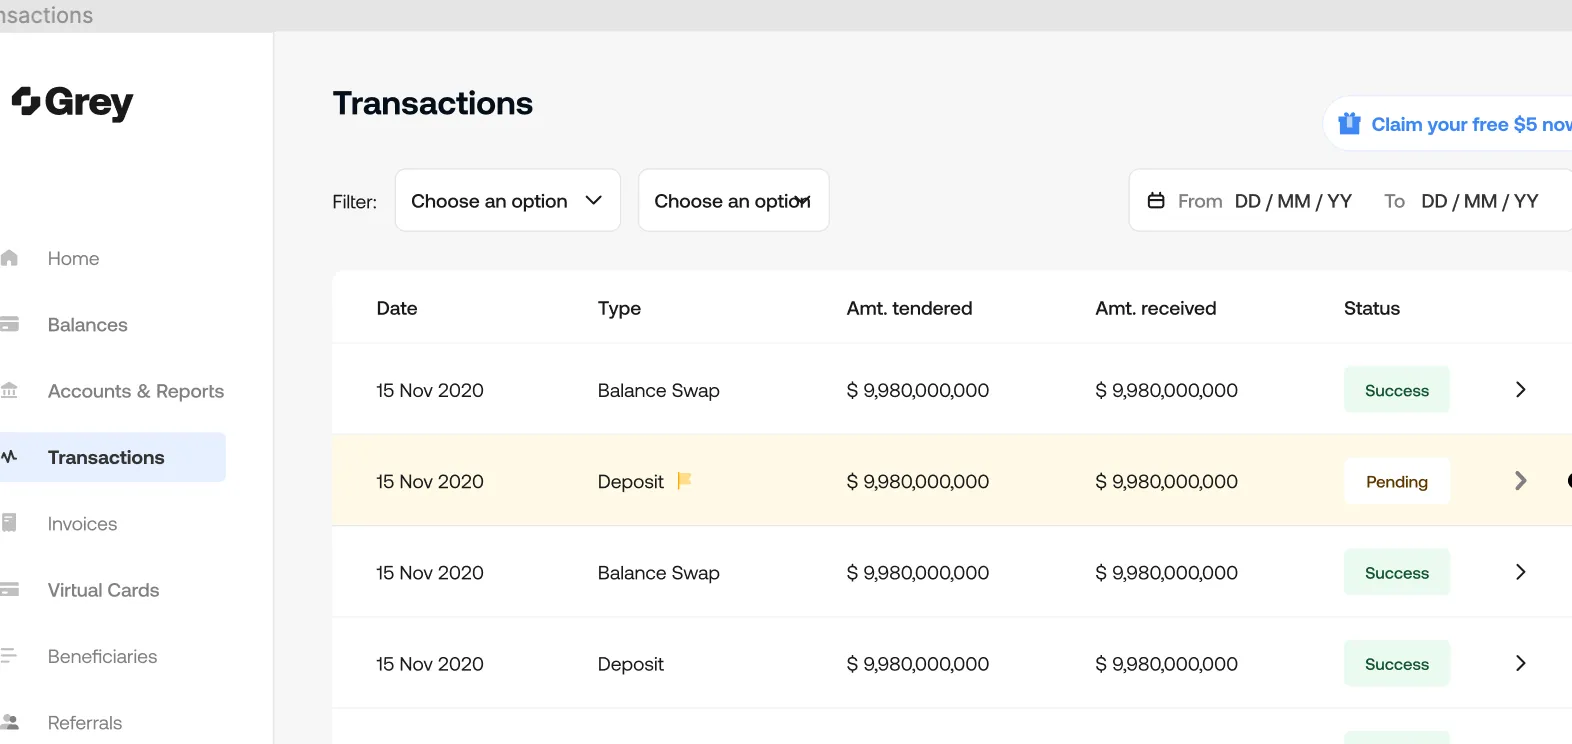
  • You will see the required deposit you need to verify, highlighted in yellow.
pending-deposit-on-Grey
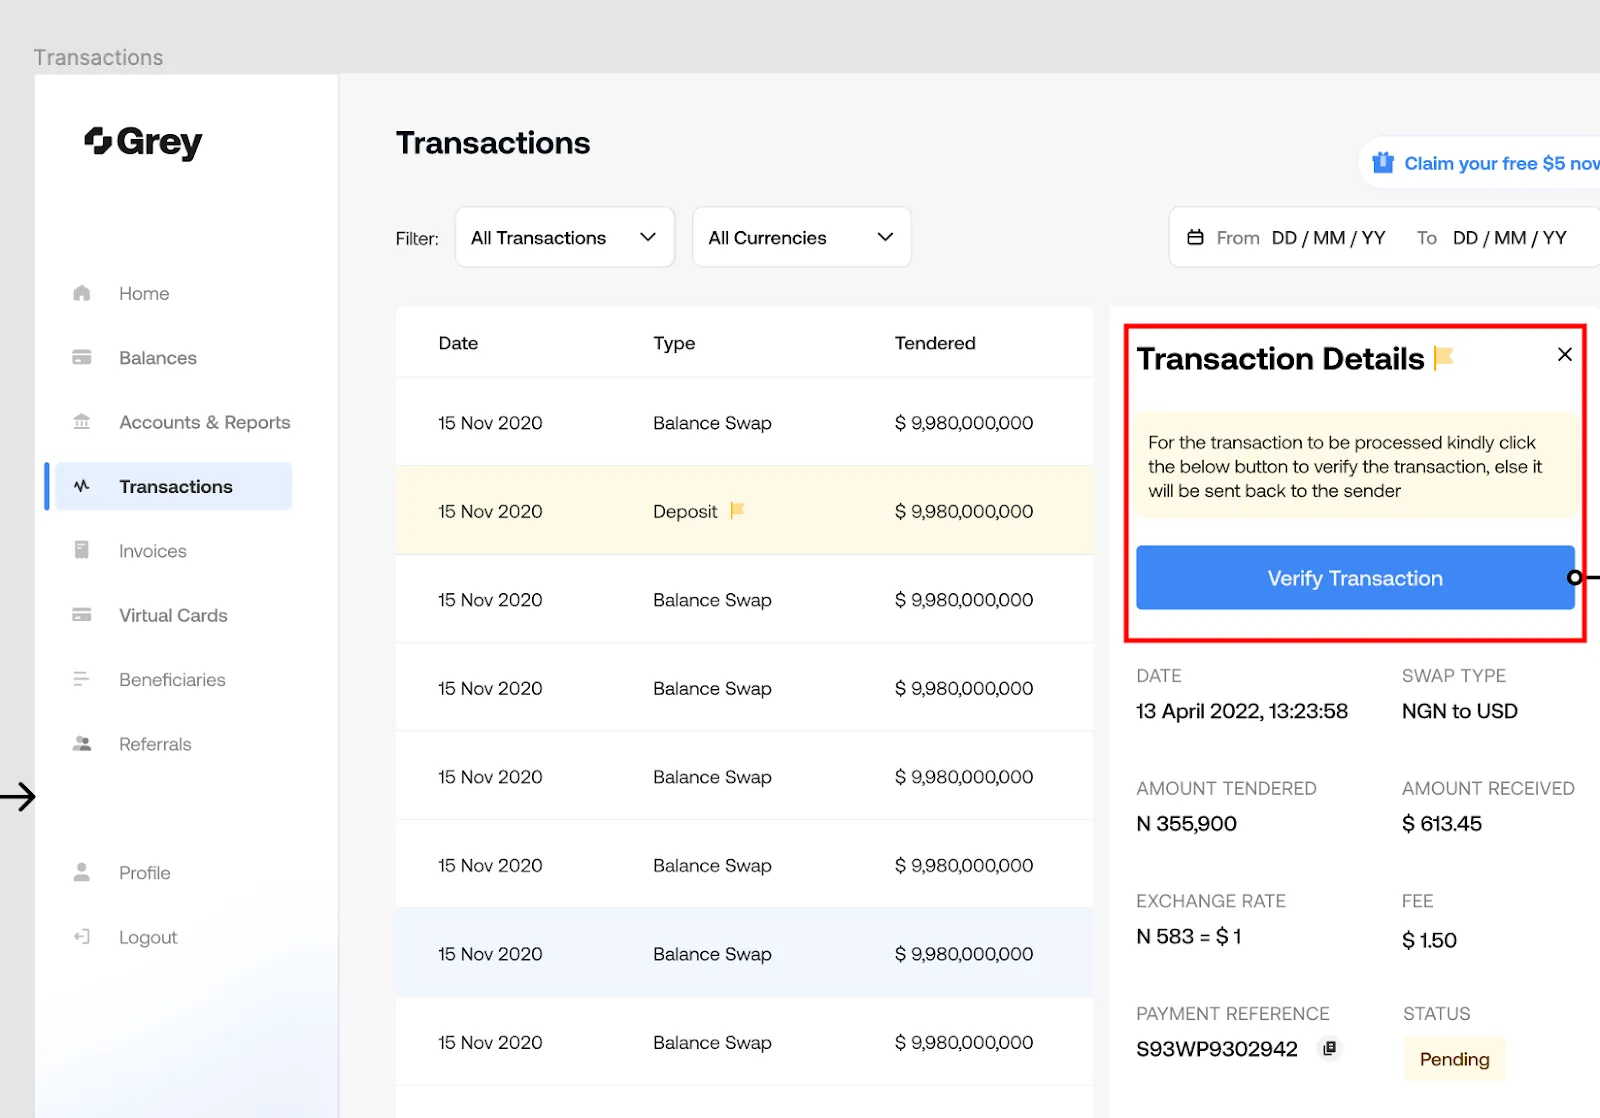
  • Tap on it and then tap on 'verify the transaction.'
verify-pending-transaction
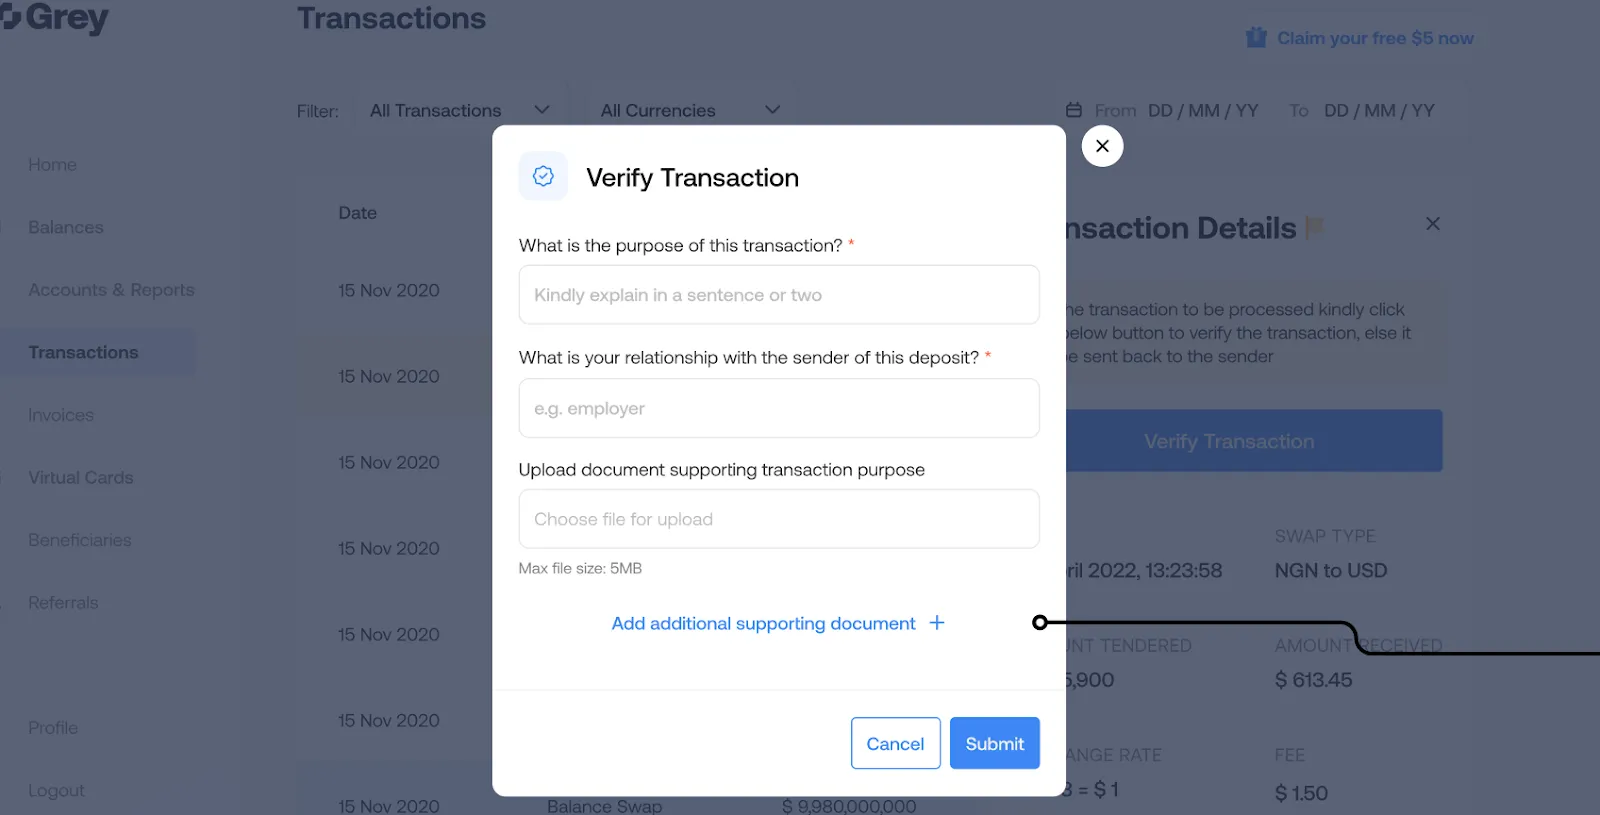
  • Enter a clear purpose of the transaction. E.g., payment for a service, deposit from a family member, etc. Remember to be truthful here.
  • Enter what your relationship with the sender is, e.g., employer, client, brother, sister, etc.
fill-verification-form
  • Upload your supporting documents and submit them.

The supporting documents you’ll be required to upload will depend on where your money is coming from. Once you submit the verification form, your transaction will be reviewed within 24-72 working hours. 

If everything checks out, you’ll receive the funds in your available balance, where you can access your money.

What happens when I cannot verify my pending transaction?

If you do not have sufficient documents to prove that the transaction is legitimate, the funds will be reversed to the sender’s originating account. This can take anywhere between 7-10 working days. 

If the rare occasion that the sender doesn’t get the money, we’ll give you a refund telex so they can trace the status of the refund. 

The bottom line

At Grey, we take your financial security seriously, and this is why we’ve implemented several measures to ensure that you’re in the clear when it comes to any financial risks.

For more information on pending transactions, please visit our help center, and we’ll be happy to help out in any way we can.

Here’s how to get paid on Upwork in Nigeria, Kenya & Tanzania

2 min read

Upwork is a leading online platform that connects freelancers with clients from all over the world. Freelancers from Nigeria, Kenya, and Tanzania can use this platform to find work and get paid for their freelance services.

However, getting paid on Upwork can be a challenge for Africans, especially if you’re not familiar with how the payment system works. That’s why in this post, we’ll show you how to set up a functional payment method on your Upwork account.

Also read: How to receive payments from freelance platforms easily in 2025

What you need before setting up a payment method on Upwork

Right off the bat, you’ll need a foreign bank account - preferably a US, UK, or EU bank account. This is because although Upwork offers several payment methods, the most effective ones are withdrawals to a bank account and to M-PESA for Kenyans.

Your bank account name or M-PESA details must also match your verified name on Upwork. If it doesn’t, your transaction might be delayed until you verify that you’re an authorized user - which can take weeks.

Considering how Upwork requires a 5-day security period before you can even access your funds for withdrawals, adding extra compliance times for name mismatch should be completely avoided.

To avoid all of these hassles, we recommend opening a global foreign account on Grey. Here, you’ll get a foreign account domiciled abroad and in your name. This makes withdrawals seamless and even faster.

How to withdraw to your bank account from Upwork

Once you’ve created a Grey foreign account and gotten your account details, here’s how to get your money from Upwork;

  • Login to your Upwork account and visit the settings section
  • Tap on “Get Paid” and select “Add method”
  • Choose the setup button for your preferred method and enter your banking details.
  • Select how frequently you want to withdraw your earnings and complete the payment method setup.

PS: When you add your banking details, Upwork verifies your payment method first. This takes three days. So it means you won’t be able to withdraw immediately after you enter your payment details.

This is why we recommend adding a backup payment method. For example, if you’re in Kenya, you can add your M-PESA details as another withdrawal option.

How long does it take to get paid on Upwork?

The time it takes for your payments to get to your bank account varies. We’ll review how long it takes for US bank accounts, other foreign bank accounts, and M-PESA.

US bank accounts

Since US withdrawals on Upwork are ACH deposits, they’ll get to your bank account within 1-3 business days. This excludes banks and public holidays. Unlike other options, withdrawals via this method are completely free.

UK and EU bank accounts

Withdrawals to UK and EU banks can take up to 2 business days, excluding bank and public holidays. Receiving payments into your UK and EU bank accounts incurs a 0.8% fee. Additionally, payments to your UK bank account have specific fees: £15 for BACS transactions and £25 for CHAPS transactions.

M-PESA

Mobile money transfer, or M-PESA, is only available on the platform for Kenyan freelancers. Unlike bank transfers, withdrawals to M-PESA are instant. However, certain situations might cause the transfer to be delayed for about 24 hours. The withdrawal fee is also $0.5.

Other ways to ensure seamless withdrawals on Upwork

  • Be sure to always submit your payment request on time. This way, you can receive the payments early and process your withdrawals on time.
  • Keep track of your payments. Use Upwork’s payment tracker to ensure that you get paid the right amount at the right time. Track this by visiting the “reports’ section and then tapping on your “transaction history”

Wrapping up

Getting paid on time from Upwork in Nigeria, Kenya, and Tanzania is easy if you follow these simple steps. Set up your payment method with a Grey account, verify it on Upwork, submit your payment request, and keep track of your payments.

With these tips, you can enjoy a seamless payment process and focus on delivering high-quality work to your clients. Start by getting a foreign bank account from Grey.

How to send money to Nigeria from the UK

2 min read

If you need to send money to Nigeria from the United Kingdom, there are several options available to you. Whether you need to send money to friends or family, pay certain bills, or make a business transaction, choosing a safe and reliable method that offers competitive rates and fast transfer times is important.

In this blog post, we’ll explore the most reliable way to send Pounds to Naira from the UK. With this information, you’ll be able to make an informed decision and send money to Nigeria with a lot more confidence.

The best way to send money to Nigeria from the United Kingdom

The best way to send money to Nigeria from the United Kingdom is through a money transfer service. A money transfer service is a company that allows you to send money from one location to another. They typically charge a fee and may also offer different exchange rates depending on the currency being sent.

Money transfer services are often better than other transfer options because they typically offer faster transfer times, competitive exchange rates, and lower fees. They usually have better customer service and provide more security for your money during the transfer process.

There are many reputable money transfer service providers like Western Union. However, the western union can be quite slow and tedious. This is why we recommend using Grey. Asides from being a reputable and reliable money transfer app, you can track your transaction in real-time and be sure it’ll deliver quickly to your recipient in Nigeria.

Why should I use Grey to send money to Nigeria?

If you’re still uncertain about whether Grey is an ideal option for your cross-border money transfers, here are a few reasons why you should choose Grey;

  1. 100% digital transfers: Rather than queuing up at the bank, you can transfer pounds from your UK bank account, swap to Naira and send it to your recipient - all on your mobile device.
  2. The best exchange rates and transfer fees: You get transparent exchange rates that are highly competitive with the current market rates. We also don’t charge any hidden fees. What you see upfront is what you pay for.
  3. Speedy transactions: For starters, converting currencies on Grey is instant. So you immediately get the equivalent in your Naira balance. Our transfers are also fast and prompt. This means when you transfer your Naira balance to your Nigerian recipient, they’ll get it in a few minutes.
  4. Free P2P transfers: Skip the currency conversions if your recipient has a Grey account. You can send them pounds directly, and they’ll receive it instantly. There are also zero transfer charges when you send money using Grey’s P2P.
  5. Instant transfer notifications: Get notified for every single transaction you make on Grey. This way, you can account for your expenses, cash outflow, and other financial statements.

How long does money transfer to Nigeria from the UK take?

If you’re sending payments into your Grey UK bank account, it can take up to two business days, depending on the payment scheme the sending bank uses. Our GBP accounts are addressable in Faster Payments (FPS), BACS, and CHAPS.

Once you have the funds in your Grey account, conversions are instant, and transfers to Nigerian accounts only take a few minutes. As we’ve mentioned, P2P transfers from your Grey UK bank accounts are also instant.

How to send money to Nigeria with Grey

Ready to start sending money from the United Kingdom to Nigeria? Here’s how to do this with Grey;

On web

  • Login to your Grey account.
  • Request for a UK bank account if you don’t have one yet on Grey
  • Once you have an account, copy the account details and send GBP to it
  • You’ll receive a notification when the funds reflect on your Grey account
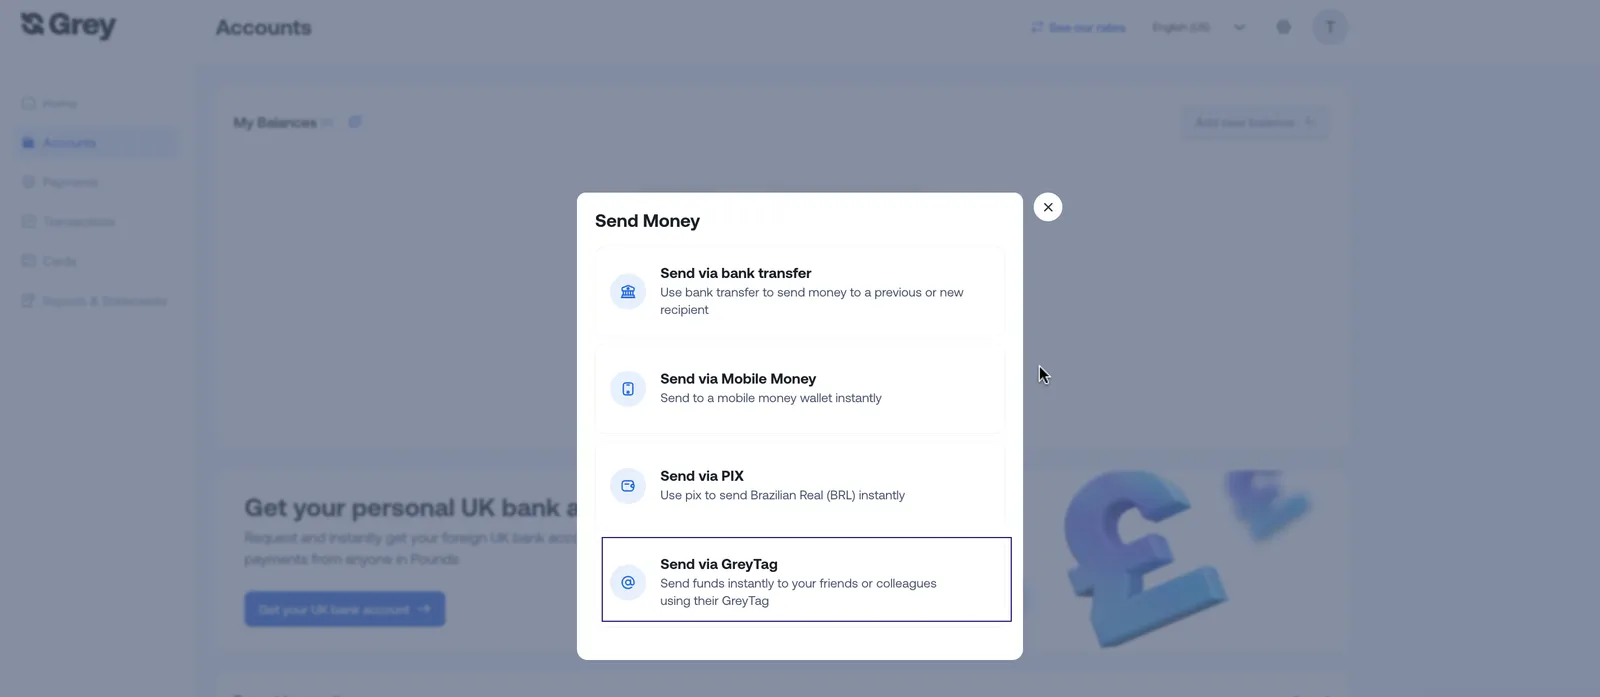
  • If you’re sending via p2p, simply tap on ‘Send GBP’ and then ‘Send via GreyTag’
__wf_reserved_inherit
  • Enter the GreyTag, and your recipient will receive it instantly
  • For direct Naira transfers, tap on ‘Swap GBP,’ enter the details of your swap, and it’ll reflect on your Naira balance
__wf_reserved_inherit
  • Tap on your Naira balance, tap on ‘Send NGN’, and choose ‘Send to New Recipient’
  • Enter the recipient’s details and then complete the transaction

On mobile

  • Log in to your Grey mobile app
  • Once you have a GBP account, copy the account details and send GBP to it
  • You’ll receive a notification when the funds reflect on your Grey account
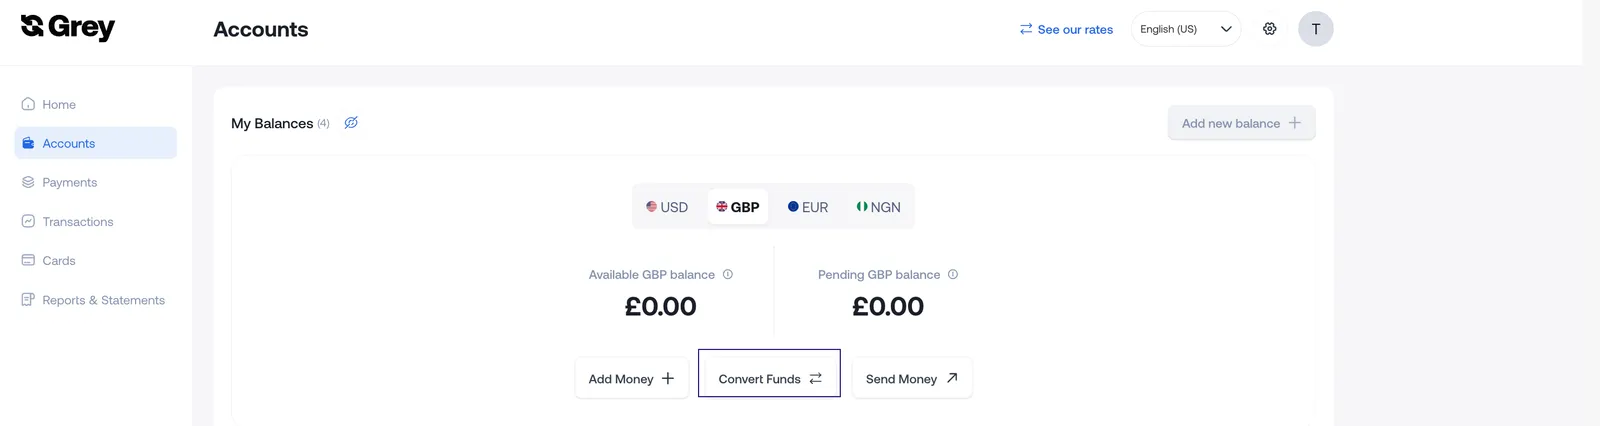
  • Tap on your GBP balance, and directly under it, tap on ‘Send Money’
  • If you’re sending via P2P, select ‘Send Using GreyTag’ from the options and complete the transaction with your recipient’s GreyTag.
  • For direct Naira transfers, tap on the three horizontal lines underneath your GBP balance and then ‘Swap GBP,’
  • Enter the details of your swap, and it’ll reflect on your Naira balance
  • Under your Naira balance, tap on ‘Send NGN’, and choose ‘Send to New Recipient’
  • Enter the recipient’s details and then complete the transaction

And that’s how to transfer money from the UK to Nigeria.

Grey is simplifying sending and receiving foreign payments for freelancers, remote workers, and businesses. On Grey, you can open a foreign bank account and receive payments from over 80 countries. Get started for free here.

Best apps to send money internationally from the US in 2026

2 min read

If you send money from the United States to family, friends, or business contacts abroad, you have probably noticed that the options have multiplied. Ten years ago, it was Western Union or your bank. Now there are over a dozen apps competing for each transfer, each with a different fee structure, exchange rate approach, and set of destination countries.

The problem is not a lack of options. It is the right app that changes depending on where you are sending, how much you are sending, and how your recipient wants to receive the money. An app that is excellent for sending $500 to India via bank deposit might be a poor choice for sending $200 to Kenya via M-Pesa.

This guide covers six of the best apps for sending money internationally from the US in 2026. For each one, we explain what it actually costs, where it works best, and what to watch out for. If you are looking for a broader overview of sending money from the US with Grey, the corridor hub page covers every supported destination.

How the main apps compare at a glance

App Best for Fee structure Speed Destinations
Grey Larger transfers to Africa and Asia 1% capped at ~$6 + flat payout fee Instant to 1-2 days 50+ countries
Wise Transparent mid-market rate transfers 0.41% to 1.5% (varies by corridor) 1-3 business days 80+ countries
Remitly Family remittances to Asia, Africa, Latin America $0 to $4.99 (varies by speed and corridor) Minutes (Express) to 3-5 days (Economy) 170+ countries
WorldRemit African mobile money corridors $0 to $4.99 (varies by destination) Minutes to 3 days 130+ countries
Sendwave No-fee transfers to Africa and Asia $0 fee (cost in exchange rate) Minutes 50+ countries
Western Union Cash pickup worldwide $2.99 to $14.99+ (varies by amount and method) Minutes to 5 days 200+ countries

Fee ranges are illustrative and vary by corridor, amount, and payment method. Always compare the total amount your recipient receives, not just the headline fee. Last checked: September 2026.

Grey

Grey is a multi-currency account provider that supports transfers from the US to over 50 countries. It is particularly strong on African corridors, where it offers both bank transfer and mobile money delivery, including M-Pesa in Kenya, MTN Mobile Money in Ghana, and direct bank transfers across the continent.

Grey charges a 1% conversion fee on all transfers, capped at the equivalent of $6 on major currency pairs (USD, EUR, GBP). That cap is the differentiator. On a $500 transfer, the fee is $5. On a $1,000 transfer, the fee is $6. On a $5,000 transfer, the fee is still $6. Most other apps charge a percentage that scales with the amount, or a flat fee plus a rate markup that grows with volume. Grey's cap means that anyone regularly sending above $600 pays less per transfer than they would on almost any other platform. Full details on Grey's fee calculator.

On top of the conversion fee, there is a flat payout fee per destination. For the US-to-India corridor, that is $1.50. For Kenya via M-Pesa, it is $0.50. For Ghana via mobile money, it is $1.00. UK destinations carry no separate payout fee.

Grey also provides multi-currency accounts (hold USD, EUR, and GBP), a virtual Visa card for online payments, and UPI delivery to India, which arrives in minutes. The UPI support is unusual among transfer apps and makes Grey a strong option for the US-to-India corridor.

Best for: US-based senders who regularly transfer larger amounts ($600+) to Africa or India and want a transparent, capped fee structure.

Wise

Wise is widely considered the benchmark for transparent international transfers. It uses the mid-market exchange rate with no markup, and the fee is shown upfront before you confirm. For most corridors, the fee ranges from 0.41% to 1.5% of the transfer amount, depending on the destination and payment method.

The advantage of Wise is predictability. The rate you see is the rate you get, and there is no hidden margin. The disadvantage is that the fee is a straight percentage with no cap, so on large transfers, it can add up. A $5,000 transfer at 0.5% costs $25 in fees. With Grey, the same transfer costs $6 in conversion fees plus a flat payout fee that depends on the destination.

Wise supports 80+ destination countries and offers a multi-currency account with a Wise debit card. It is an excellent all-round choice for US senders, particularly for bank-to-bank transfers in Europe and Asia. Its African coverage is solid for bank transfers but less comprehensive for mobile money delivery than Grey or WorldRemit.

Best for: Senders who prioritise exchange rate transparency and send moderate amounts to a wide range of countries.

Remitly

Remitly is built for family remittances. It offers two delivery speeds: Express (arrives in minutes, higher fee) and Economy (arrives in 3 to 5 business days, lower fee). The fee ranges from $0 to $4.99, depending on the corridor, payment method, and delivery speed.

Remitly's strength is its coverage of popular remittance corridors: India, the Philippines, Mexico, Pakistan, Bangladesh, Nigeria, Kenya, and Ghana are all well served. Delivery options include bank deposit, mobile wallet, cash pickup, and door-to-door delivery in some markets. First-time users often receive a promotional rate on their first transfer.

The trade-off is the exchange rate. Remitly does not use the mid-market rate. The rate includes a margin, so the headline fee may look low, but the total cost (fee plus rate) can be higher than Wise's on the same corridor. Always compare the final amount your recipient receives, not just the fee.

Best for: Frequent senders to South Asia, Southeast Asia, and Latin America who value delivery speed and flexibility (bank, wallet, or cash pickup).

WorldRemit

WorldRemit is the strongest app for mobile money transfers to Africa. It supports M-Pesa in Kenya, MTN Mobile Money in Ghana, Airtel Money in Uganda, and mobile wallets across dozens of African countries. If your recipient does not have a bank account or prefers receiving via their phone, WorldRemit covers more African mobile money networks than any other major US-based app.

Fees range from $0 to $4.99, depending on the destination, amount, and delivery method. Like Remitly, WorldRemit includes a margin in the exchange rate, so the headline fee does not tell the full story. Cash pickup is available in some countries through partner agent networks.

WorldRemit also supports airtime top-ups, which let you add mobile credit to your recipient's phone directly. This is a niche feature, but useful for senders supporting family members who need phone credit more than cash.

Best for: Senders to sub-Saharan Africa who need mobile money delivery, particularly to countries with strong M-Pesa or MTN Mobile Money networks.

Sendwave

Sendwave charges no visible transfer fee. The cost is built into the exchange rate, similar to Pesa on the Nigeria corridor. The app specialises in transfers to Africa and parts of Asia, with a simple interface designed for speed.

The appeal is simplicity. You enter an amount, see what your recipient gets, and confirm. There is no fee line item to think about. But as with any zero-fee app, the total cost depends on the exchange rate markup. Compare the amount your recipient receives on Sendwave against what they would receive on Wise or Grey at the same moment to know whether the zero-fee model is actually cheaper.

Sendwave supports mobile money and bank transfer in most African markets. It is owned by WorldRemit's parent company (Zepz), but operates as a separate app with its own rates and fee structure.

Best for: Small, frequent transfers to Africa and Asia, where simplicity and speed matter more than optimising the exchange rate.

Western Union

Western Union has the largest cash pickup network in the world, with over 500,000 agent locations across 200+ countries. If your recipient needs physical cash and does not have a bank account or mobile money wallet, Western Union is often the only practical option.

Fees range from $2.99 to $14.99 or more, depending on the amount, destination, and delivery method. The exchange rate includes a margin. Western Union is rarely the cheapest option for bank-to-bank transfers, but its reach is unmatched for cash pickup in remote locations.

Western Union also offers bank deposit and mobile wallet delivery in many countries, though its digital experience is less polished than purpose-built apps like Wise or Remitly.

Best for: Senders whose recipients need cash pickup at a physical agent location, particularly in countries with limited banking infrastructure.

How to choose the right app for your transfer

The best app depends on three things: where your recipient is, how they want to receive the money, and how much you are sending.

If you send large amounts ($600+) regularly to Africa or India, Grey's $6 fee cap makes it the cheapest published option. On a $2,000 transfer, Grey charges $6 while Wise charges $10 to $30, depending on the corridor, and Remitly's combined fee and rate markup can exceed that.

If you prioritise exchange rate transparency, Wise is the strongest choice. The mid-market rate with no markup means you always know the true cost.

If your recipient needs mobile money in Africa, WorldRemit has the widest mobile money network. Grey covers M-Pesa (Kenya) and MTN Mobile Money (Ghana) well, but WorldRemit reaches more networks across more countries.

If your recipient needs cash pickup, Western Union's 500,000+ agent network is unmatched.

If you send small amounts frequently and want simplicity, Sendwave's zero-fee model removes the decision fatigue, though you should periodically check whether the rate is competitive.

Also read: How to send money from Nigeria to any country in 2026 covers the outbound Nigeria corridor, where the competitive landscape is very different.

Frequently asked questions

What is the cheapest app to send money internationally from the US?

It depends on the amount and destination. For transfers above $600, Grey's 1% fee capped at $6 is the lowest published rate among apps with transparent pricing. For smaller amounts, Wise's percentage-based fee (from 0.41%) or Remitly's Economy tier may be cheaper on specific corridors. Sendwave charges no visible fee but builds cost into the exchange rate. Always compare the final amount your recipient receives.

Is Wise or Remitly better for sending money from the US?

Wise is better for transparency: it uses the mid-market exchange rate with no markup, and the fee is shown upfront. Remitly is better for speed and delivery flexibility: its Express option delivers in minutes and supports bank, mobile wallet, and cash pickup. Wise is usually cheaper on total cost for bank-to-bank transfers. Remitly is stronger for mobile wallet delivery in Asia and Africa.

Can I send money from the US to M-Pesa in Kenya?

Yes. Grey, WorldRemit, and Sendwave all support M-Pesa delivery from the US to Kenya. Grey charges $0.50 per M-Pesa transfer plus a 1% conversion fee capped at $6. The transfer is instant.

What is the cheapest way to send money from the US to India?

Grey offers a $1.50 flat payout fee plus a 1% conversion fee capped at $6, with delivery via UPI in minutes. Wise charges from approximately 0.41% with delivery in 1 to 2 business days. Remitly's Economy option is often competitive for smaller amounts. On a $1,000 transfer, Grey costs $7.50 total (conversion cap + payout fee).

How long does it take to send money from the US internationally?

It depends on the destination and app. Transfers via Grey to India (UPI) and Kenya (M-Pesa) are instant. Transfers to the UK and most of Europe arrive within 1 to 2 business days. Remitly's Express option delivers in minutes on popular corridors. Bank-to-bank transfers via Wise typically take 1 to 3 business days.

Is Grey available in the United States?

Yes. Grey is licensed by FinCEN in the US as a Money Services Business. US residents can open a Grey account, hold multiple currencies, and send money to 50+ countries. Grey also provides virtual Visa cards and multi-currency accounts for receiving international payments.

Related reading

How to send money from Nigeria to any country in 2026 covers the outbound Nigeria corridor, where most competitors do not operate, and Grey's positioning is very different from the US market.

Cheapest way to send money from Nigeria in 2026 compares fees across Grey, Flutterwave Send, Pesa, and Eversend for the Nigeria outbound market.

Exchange rates on Grey are variable and include a margin over the mid-market rate. Always review the rate before confirming a conversion. Grey is a financial technology company, not a bank. Banking services are provided by licensed banking partners. This article is general information, not financial advice.

How to send money from Dubai to Nigeria

2 min read

It's salary day. You've already done the maths: AED 3,000 for rent, AED 1,500 for food and transport, AED 2,000 to send home to Lagos. You walk into the exchange house near Al Fahidi metro, take a ticket, and wait.

When your number comes up, you slide your Emirates ID across the counter and say "Nigeria, bank transfer." The receipt shows a fee of AED 15. Looks cheap. What the receipt doesn't show is that the exchange rate they've used is 3% worse than the actual market rate. On AED 2,000, that's another AED 60 gone. You won't see it because it's baked into the rate, not listed as a fee.

That AED 75 total cost isn't the worst deal in Dubai. But it's not the best, either. And if you're sending money home every month, twelve transfers at AED 75 each is AED 900 a year. Enough to matter.

To send money from Dubai to Nigeria, you can use a bank transfer, an exchange house, or a fintech app. Fintech apps are usually the fastest and cheapest, often delivering naira within minutes. Compare the total cost, which includes both the fee and the exchange rate margin, before you send.

This guide walks you through every way to send money from the UAE to Nigeria. It explains the real costs (not just the advertised fees) and shows you how to make sure your recipient gets the most naira possible for every dirham you send.

Ways to send money from Dubai to Nigeria

There are three main ways to transfer money from Dubai to Nigeria. Each suits a different situation. The right one depends on how much you're sending, how fast it needs to arrive, and whether your recipient has a bank account.

1. Bank wire transfer (SWIFT)

Your UAE bank sends the money via the SWIFT network to a Nigerian bank account. This is the route most people think of first, and it's the most expensive for regular transfers.

UAE banks typically charge AED 50-100 as a flat outgoing transfer fee. The receiving Nigerian bank may charge an additional fee upon arrival (typically $10 to $20 or the naira equivalent). And the exchange rate your bank offers for AED to NGN is almost never competitive. Banks aren't in the business of offering tight FX rates on retail transfers. They build their margin into the rate.

Delivery takes 2 to 5 business days. During that window, the exchange rate can fluctuate, so the naira amount your recipient receives may differ from what you saw when you initiated the transfer.

Use it if: you're sending a large amount (above AED 20,000) where the flat fee is a small percentage of the total. Skip it if: you need the money to arrive today, you're sending less than AED 5,000, or you send monthly and want to minimise annual cost.

2. Exchange houses

Al Ansari Exchange, UAE Exchange (now Lulu Exchange), and similar operators are the traditional choice for Dubai residents sending money to Nigeria. You walk in with AED in cash or a debit card, the operator processes the transfer, and your recipient receives naira in a Nigerian bank account or as cash pickup.

The stated fees are low: typically AED 10 to 30. That's the number on the board, and it's designed to look attractive. The real cost is in the exchange rate. Exchange houses buy USD or AED from the wholesale market and sell them to you at a 2-4% markup. On an AED 5,000 transfer, a 3% rate markup is AED 150. Add the AED 15 fee, and your true cost is AED 165, not AED 15.

Delivery is faster than banks: same-day to next business day for bank deposits, and within hours for cash pickup. The cash pickup option is important for recipients who don't have a bank account or who need physical naira urgently.

Use it if your recipient needs cash pickup, you prefer to conduct the transaction in person, or you don't have a smartphone for app-based transfers. Skip it if: you're cost-sensitive and willing to compare rates on an app before sending.

3. Fintech apps

Digital transfer services handle the conversion and delivery through their own network, bypassing some of the traditional banking intermediaries. Fees are typically lower, rates are closer to mid-market, and delivery is faster (minutes to hours). Most require Emirates ID verification on your first transfer. See also virtual dollar cards in the UAE to learn how UAE residents can hold and spend USD digitally.

The advantage is transparency. Most fintech apps show you the exchange rate, the fee, and the exact naira amount the recipient will get before you confirm. There's no mystery about where your money went. The disadvantage is that not all apps are licensed for the UAE-Nigeria corridor, and regulatory coverage varies. Check that your provider is licensed by the UAE Central Bank before sending.

Use it if: you want the lowest total cost, fastest delivery, and full visibility on the rate. Skip it if: you need cash pickup (not all apps support it) or you prefer face-to-face transactions.

Comparing fees, speed, and exchange rates

The single most important lesson in sending money from Dubai to Nigeria: never compare fees without comparing exchange rates. A service that charges AED 0 in fees but marks up the exchange rate by 3% is more expensive than one that charges AED 25 but gives you a rate within 0.5% of mid-market.

The "total cost" is the fee plus the exchange rate margin. Here's what that looks like on an AED 5,000 transfer:

Method Stated fee Rate margin Speed True cost on AED 5,000
Bank wire (SWIFT) AED 50 to 100 1.5 to 3% 2 to 5 business days AED 125 to 250
Exchange house AED 10 to 30 2 to 4% Same day to 2 days AED 110 to 230
Fintech app AED 0 to 25 0.5 to 1.5% Minutes to hours AED 25 to 100
Grey (hold USD, convert to NGN) Flat fee per transfer Grey rate Minutes See grey.co for current rates

Focus on the "true cost"— not just the fee you see. Two exchange houses might charge AED 15 and AED 30, but the one with a better exchange rate could put more naira in your recipient’s hand, even if their fee is higher.

Over 12 monthly transfers of AED 5,000, the gap between the most expensive method (bank wire at AED 250 per transfer) and the cheapest (fintech at AED 50 per transfer) is AED 2,400 per year. That's a flight home.

All numbers here are estimates based on publicly available information from mid-2026. Fees and rates can change quickly, so double-check the total cost right before you send.

Hidden costs most guides skip

The fee and the exchange rate margin aren't the only costs. Three others can reduce what your recipient actually receives:

Intermediary bank charges: SWIFT transfers sometimes pass through one or two intermediary banks on the way to Nigeria. Each intermediary can deduct $5 to $20 from the transfer. You won't know this happened until your recipient reports receiving less than expected. This is most common with bank wires and doesn't apply to fintech apps (which use their own settlement networks).

Receiving bank charges: The Nigerian bank that receives the deposit may deduct its own fee, typically NGN 500-2,000, depending on the bank and the transfer amount. This comes from the naira your recipient receives, not from your dirham total. It's invisible to the sender.

Double conversion: If your provider converts AED to USD first, then USD to NGN, you're paying two conversion margins. This is common with exchange houses that don't offer a direct AED/NGN rate. Ask whether the conversion is direct (AED to NGN) or indirect (AED to USD to NGN). If it's indirect, the true cost is higher than the table above suggests.

Cash pickup markup: If your recipient collects cash rather than receiving a bank deposit, some providers charge a less favourable rate for the cash option. The difference can be 0.5 to 1%. It's rarely disclosed upfront.

Step by step: Sending AED to Naira

Regardless of your chosen method, the process follows the same structure. Here's what to prepare before you start:

  1. Choose your provider. Bank, exchange house, or fintech app. Use the cost comparison above. For first-time digital transfers, you'll need to create an account and verify your identity.
  2. Provide your identification. Emirates ID is mandatory for all UAE-based transfers. Some providers also require your passport. First-time users go through a KYC (Know Your Customer) check that typically takes 10 to 30 minutes. Once verified, subsequent transfers don't require re-verification.
  3. Enter the recipient's details. You need: their full name as it appears on their Nigerian bank account or national ID, their bank name and account number (10 digits for Nigerian banks), and their phone number. For cash pickup, the recipient needs a government-issued ID and the reference number you'll receive after sending.
  4. Enter the amount in AED. The provider shows the exchange rate, the fee, and the exact naira amount the recipient will receive. Check the naira figure carefully. If it looks lower than expected, the rate margin is probably wider than the competition.
  5. Fund the transfer. Options include: bank transfer from your UAE account (free but adds a day), debit card (instant, usually free), credit card (instant, but many providers charge a cash advance fee of 2 to 3% on top), or cash at a physical location.
  6. Confirm and share the reference. You'll get a confirmation with a tracking number. Share it with your recipient so they know the money is on the way and can confirm receipt. Most fintech apps show real-time delivery status in the app.
  7. Keep the receipt. Store the confirmation for your records. If you're in the UAE on a work visa and regularly send money, your employer or immigration authorities may request proof of remittance. It's rare, but having receipts is a good habit.

There's no legal cap on how much you can send from the UAE to Nigeria. But providers impose their own limits. Transfers above a certain threshold (typically AED 10,000 to 35,000 depending on the provider) trigger enhanced due diligence: pay slips, employment letters, or a source-of-funds declaration. This is standard anti-money-laundering procedure, not a sign that anything is wrong.

A simpler way with Grey

The traditional Dubai-to-Nigeria transfer follows a two-conversion path: AED converts to USD (or remains in AED), then to NGN at the receiving end. Each conversion has a margin. Two margins on one transfer is how the total cost compounds without the sender noticing.

Grey changes the flow. You hold USD before you convert, see the USD-to-NGN rate in real time, and send money across borders with Grey when the rate works for you. The rate and the fee are visible before you confirm. No hidden markup layered underneath.

Here's where it gets practical. Say you earn AED 10,000 per month and want to send AED 2,000 home. Instead of walking into the exchange house on payday and accepting whatever rate they're offering, you hold USD in your Grey account and watch the NGN rate. If the rate is strong on Tuesday, you convert and send on Tuesday. If it dips, you wait. The money sits in USD until you're ready.

Over a year, even small improvements in timing can save hundreds of dirhams. You can also track and hold multiple currencies if you're managing money across more than one corridor. For Nigerians in Dubai supporting family in Lagos, parents in Ibadan, and a sibling in Abuja, a single account handles it all.

If you’re sending money to Nigeria, you can hold USD with Grey and send it home whenever the exchange rate looks good — no hidden costs, just clear rates.

Frequently asked questions about sending money from Dubai to Nigeria

What's the cheapest way to send money from Dubai to Nigeria?

Fintech apps typically deliver the lowest total cost when you account for both the fee and the exchange rate margin. Exchange houses appear cheaper because their stated fees are lower (AED 10 to 30), but the 2 to 4% exchange rate markup adds a hidden cost that often exceeds the fee itself. For regular senders, holding USD in a Grey account and converting to NGN when the rate is favourable saves more over a year than any single-transfer comparison.

How long does it take to send money from Dubai to Nigeria?

It depends on the method. Fintech apps deliver in minutes to a few hours. Exchange house bank deposits arrive on the same day or the next business day. Cash pickup can be collected within hours. Bank wire transfers take 2 to 5 business days and can take longer if an intermediary bank is involved. The speed is determined by the method, not the country. A fintech transfer to Nigeria is no slower than one to India or the Philippines.

What documents do I need to send money from the UAE to Nigeria?

Emirates ID is required for all methods. Some providers ask for your passport. First-time digital users complete a KYC verification (10 to 30 minutes, one-time). For large transfers, typically above AED 10,000 to 35,000, depending on the provider, you may need a recent pay slip, an employment letter or contract, and a declaration of the source of funds. Regular senders who've already been verified don't repeat the documentation each time.

Is it legal to send money from Dubai to Nigeria?

Yes, completely. The UAE Central Bank regulates all remittance services operating in the country. Licensed exchange houses, banks, and fintech providers all operate under its supervision. There's no government cap on how much you can send. Individual providers set their own per-transaction and per-month limits, and transfers above certain amounts trigger enhanced checks as a standard regulatory requirement.

Why does the naira amount change between transfers?

Because the AED-to-NGN exchange rate fluctuates daily. The naira has been particularly volatile against the dollar and dirham in recent years. If you sent AED 2,000 last month and your family received NGN X, sending the same AED 2,000 this month might yield a different naira amount, even with the same provider and fee. This is normal FX behaviour. It's also why holding USD and choosing when to convert (rather than converting on payday every time) can make a measurable difference over the course of a year.

Can I send money from Dubai to Nigeria using my phone?

Yes. Most fintech apps and several exchange houses (including Al Ansari and Lulu Exchange) offer mobile apps for UAE-to-Nigeria transfers. Create an account, verify with your Emirates ID, add your recipient's Nigerian bank details, and fund the transfer by card or bank transfer. Once verified, subsequent transfers take under five minutes.

What exchange rate will I get when sending AED to NGN? It depends on the provider and the moment you send. No provider gives you the exact mid-market rate. Fintech apps typically offer rates within 0.5 to 1.5 percentage points of the mid-market rate. Exchange houses are 2-4% off. Banks are 1.5 to 3% off. The only way to know is to compare at least two providers at the exact moment you're ready to send. For a broader look at the Nigeria corridor, see sending money to Nigeria.

Open a Grey account and send money home to Nigeria with clear rates and no hidden margins.

Disclaimer: This article is for informational purposes only. Fees, exchange rates, and transfer limits change frequently. All cost estimates are based on publicly available data as of mid-2026 and should be verified at the point of sending. Grey is not a bank. Grey is a licensed financial services provider offering multi-currency accounts.

Arrow (up)

Back to top