<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/how-non-u-s-residents-can-open-accounts-at-chase-wells-fargo-and-bank-of-america#article","headline":"How non-US residents can open accounts at Chase, Wells Fargo, and Bank of America","description":"A practical guide to opening a US bank account as a non-US resident in 2026. Exact requirements for Chase, Wells Fargo, and Bank of America , and the Grey alternative that works without a US address.","inLanguage":"en","url":"https://grey.co/blog/how-non-u-s-residents-can-open-accounts-at-chase-wells-fargo-and-bank-of-america","mainEntityOfPage":{"@id":"https://grey.co/blog/how-non-u-s-residents-can-open-accounts-at-chase-wells-fargo-and-bank-of-america#webpage"},"datePublished":"2024-10-30T15:24:19.185Z","dateModified":"2026-07-01T00:37:13.316Z","author":{"@type":"Person","@id":"https://grey.co/authors/olayoyin-olorunmota#person","name":"Olayoyin Olorunmota","url":"https://grey.co/authors/olayoyin-olorunmota","jobTitle":"Content Writer","sameAs":["http://www.linkedin.com/in/olayoyinolorunmota","http://x.com/yoyin_michael"]},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/how-non-u-s-residents-can-open-accounts-at-chase-wells-fargo-and-bank-of-america#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/67224ebf67ab7498cc794154_How%20to%20open%20Chase%20Wells%20Fargo%20and%20Bank%20of%20America%20nonresident%20accounts%20requirements%20and%20process.avif","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/67224ebf67ab7498cc794154_How%20to%20open%20Chase%20Wells%20Fargo%20and%20Bank%20of%20America%20nonresident%20accounts%20requirements%20and%20process.avif","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/how-non-u-s-residents-can-open-accounts-at-chase-wells-fargo-and-bank-of-america#webpage","url":"https://grey.co/blog/how-non-u-s-residents-can-open-accounts-at-chase-wells-fargo-and-bank-of-america","name":"How to Open a US Bank Account as a Non-Resident: Chase, Wells Fargo, and Bank of America | Grey","description":"A practical guide to opening a US bank account as a non-US resident in 2026. Exact requirements for Chase, Wells Fargo, and Bank of America , and the Grey alternative that works without a US address.","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/how-non-u-s-residents-can-open-accounts-at-chase-wells-fargo-and-bank-of-america#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/how-non-u-s-residents-can-open-accounts-at-chase-wells-fargo-and-bank-of-america#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/how-non-u-s-residents-can-open-accounts-at-chase-wells-fargo-and-bank-of-america#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"How non-US residents can open accounts at Chase, Wells Fargo, and Bank of America","item":"https://grey.co/blog/how-non-u-s-residents-can-open-accounts-at-chase-wells-fargo-and-bank-of-america"}]}] </script>

How non-US residents can open accounts at Chase, Wells Fargo, and Bank of America

Olayoyin Olorunmota

TABLE OF CONTENT

SHARE THIS POST

A US bank account makes international income genuinely easier to manage. It gives you a USD account with ACH routing details that most freelance platforms, payroll systems, and international clients can pay directly ,  without conversion fees at the point of receipt. The challenge for non-residents is that the major US banks were built for people who live in the United States, and their account-opening processes reflect that.

This guide covers the exact requirements for Chase, Wells Fargo, and Bank of America in 2026 ,  what each bank actually needs from you, where each falls short for non-residents who do not have a US address, and a practical alternative for those who cannot meet those requirements.

At a glance: which bank suits which situation

Bank In-person required? US address required? SSN required?
Chase Sometimes , depends on documentation Yes , must show proof No , foreign TIN accepted in some cases
Wells Fargo Yes , always Yes , US proof of address required No , foreign TIN may suffice
Bank of America Yes , always Yes , both US and foreign address required No , FTIN accepted
Grey No , fully online No , no US address needed No , not required

Also read: How to open Pounds account as a non-UK resident

The US address requirement is the most significant barrier for most non-residents. All three major banks require proof of a US physical address. If you do not have one, your options at these banks are limited regardless of how complete your other documentation is.

Chase Bank

Chase is the largest bank in the United States by assets and has the widest branch network. Non-US residents are generally eligible to open a Chase account, and in some cases it is possible to do this online ,  but only if you have US-issued documentation to verify your address and identity. If your address and identification are foreign, you will need to visit a branch in person.

Eligibility

Chase accepts non-residents who have a valid US residential address. People who split their year between the US and another country and have a US property are typically the strongest candidates. Non-residents with no US address will find the process difficult ,  Chase's online application requires a US address field that cannot be left blank with a foreign address.

Required documents

  • A valid passport with photo , this is the primary form of identification.
  • Proof of US residential address , a utility bill, bank statement, or lease agreement in your name at a US address. This is where most non-residents without US property are stopped.
  • A tax identification number , Chase typically requires a US TIN (Social Security Number or ITIN), though in some cases a foreign tax ID number may be accepted. Confirm with your branch before visiting.

Account types available

Chase offers checking and savings accounts for non-residents. A basic checking account is the most accessible starting point, giving you ACH routing details, a debit card, and access to Chase's online banking and mobile app. The Chase Total Checking account is the standard entry-level option. It carries a $12 monthly service fee, waivable if you receive at least $500 in direct deposits per month, maintain a $1,500 daily balance, or hold an average beginning day balance of $5,000 across linked Chase accounts. For a non-resident without US direct deposit set up, the $12 fee will apply until you meet one of these conditions.

What to know before you go

If you need to visit a branch, call ahead to confirm the branch handles non-resident account openings ,  not all branches are equally familiar with the process. Bring all documentation in the original, not photocopied. If your primary language is not English, Chase has interpretation services available in branch.

Wells Fargo

Wells Fargo requires an in-person visit to a US branch for all non-resident account openings ,  there is no online route. This makes it the most demanding of the three banks in terms of logistics, but the documentation requirements are broadly similar.

Eligibility

Non-residents can open a Wells Fargo account but must do so in person at a US branch. Wells Fargo representatives will guide you through the specific requirements at your appointment. Like Chase and Bank of America, a US residential address and proof of that address are required.

Required documents

  • A valid passport or government-issued photo ID , a passport is the preferred primary identification.
  • Proof of US residential address , a utility bill, bank statement, or lease agreement. The address must be a US physical address, not a PO box.
  • A tax identification number or foreign equivalent , a US TIN is preferred, but some foreign tax identification numbers are accepted. Confirm the specific foreign TIN your country issues before visiting.

Also read: Can non-residents open a US bank account online in 2026?

Account types available

Wells Fargo offers standard checking and savings accounts for non-residents. The Everyday Checking account is typically the starting point, providing direct deposit capability, a debit card, and access to Wells Fargo's branch and ATM network. It carries a $10 monthly service fee, waivable with a $500 minimum daily balance, $500 or more in qualifying direct deposits per month, or a linked Wells Fargo Campus Card or Campus ATM card. Again, non-residents without US payroll direct deposit will typically pay the monthly fee unless they maintain the minimum balance.

What to know before you go

Wells Fargo is the most opaque of the three banks on its non-resident requirements. Unlike Bank of America, which publishes a specific eligibility checklist on its website, Wells Fargo's published guidance says little more than that representatives will help you on arrival. In practice, requirements vary between branches and between individual representatives ,  two people with identical documentation have reported different outcomes at different locations.

The practical implication: call the specific branch before visiting, describe your situation precisely ,  country of residence, visa status if any, documentation you have ,  and ask directly whether that branch handles non-resident account openings. If the person you reach is unsure, ask to speak with a branch manager. An uninformed representative can turn you away even if the branch is capable of opening the account. Because the in-person requirement is mandatory and your trip to the US may be time-limited, this call is worth making before you book anything.

Also read: What non-US residents need to open a US bank account

Bank of America

Bank of America has a dedicated non-resident banking programme and is arguably the most structured of the three in its approach. It has specific eligibility criteria, a two-form-of-ID requirement, and a clear document checklist that sets clearer expectations than the other banks.

Eligibility

Bank of America's non-resident programme has specific eligibility requirements that differ from Chase and Wells Fargo:

  • You must have a physical US address , not a PO box.
  • You must not be a US citizen.
  • You must not be a permanent US resident (green card holder).

The exclusion of permanent residents is notable ,  Bank of America's non-resident programme is specifically for temporary visitors, international students, and professionals on non-immigrant visas, not for people who have established permanent residency.

Required documents

Bank of America requires two forms of identification ,  one primary and one secondary ,  plus proof of both a US and foreign address, and a tax identification number.

Primary ID (one of the following):

  • Foreign passport with or without visa
  • US Non-immigrant Visa and Border Crossing Card (DSP-150)
  • Mexican, Guatemalan, Dominican, or Colombian Consular ID
  • Canadian Citizenship Certificate Card

Secondary ID (one of the following):

  • Foreign or US driver's licence with photo
  • Debit or major credit card with a Visa or Mastercard logo
  • Major retail credit card from a nationally recognised company
  • US Department of State Diplomat ID
  • Mexican Voter Registration Card with photo

Tax identification:

  • A Foreign Tax Identification Number (FTIN) issued by a country other than the US. A US SSN or ITIN is not required unless you have already been issued one.

Proof of address

You must provide both a US physical address and a foreign home or permanent residence address. For the US address, one of the following is accepted:

  • Government-issued photo ID showing a US address
  • Current utility bill with your name and US address
  • Rental agreement or similar document

Account types available

Bank of America offers three main account tiers for non-residents through its Advantage Banking range: SafeBalance (no overdraft, simple structure), Advantage Plus (flexible with more features), and Advantage Relationship (comprehensive with relationship benefits). For most non-residents opening an account for the first time, SafeBalance or Advantage Plus are the practical starting points. SafeBalance carries a $4.95 monthly fee with no waiver option ,  it is a flat fee by design. Advantage Plus carries a $12 monthly fee, waivable with one qualifying direct deposit of $250 or more per month, or a minimum daily balance of $1,500. Non-residents who cannot set up US direct deposit immediately should factor the $4.95 to $12 monthly cost into their decision.

What to know before you go

Schedule an appointment at a Bank of America financial centre before visiting ,  walk-in service is available but appointments are faster. Bank of America has language interpretation services covering over 206 languages, so language is not a barrier. The two-form-of-ID requirement is stricter than Chase and Wells Fargo, so prepare both primary and secondary documents before your visit.

Do you need a Social Security Number?

None of the three banks absolutely require a Social Security Number (SSN) from non-residents, but all three ask for some form of tax identification. Here is the distinction:

Identifier What it is Who it is for
SSN Social Security Number issued by the US Social Security Administration US citizens and authorised workers , denotes work authorisation in most cases
ITIN Individual Taxpayer Identification Number issued by the IRS Non-residents who are ineligible for an SSN but need to file US taxes or open certain accounts
FTIN Foreign Tax Identification Number issued by your home country Accepted by Bank of America and some Chase branches as an alternative to a US TIN

Read on to see how non-US citizens can open a US bank account online

International students: If you are in the US on a student visa and working through your university or a practical training programme, your university may help you apply for an SSN. Students not authorised to work who still have taxable income (scholarships, for example) may need to apply for an ITIN instead. Confirm your tax status before visiting any bank.

How to apply for an ITIN

If you determine that you need an ITIN to open a US bank account, here is how the process works:

  • Form W-7. Complete IRS Form W-7, which is the Application for IRS Individual Taxpayer Identification Number. The form is available as a free PDF on the IRS website at irs.gov.
  • Identity documents. You must submit certified or notarised copies of identity documents alongside Form W-7. Acceptable documents include a foreign passport (the only document accepted on its own), or a combination of documents such as a national ID card plus a foreign birth certificate. The IRS publishes a full list of accepted documents on the W-7 instructions page.
  • Submission. Mail your completed W-7, certified identity documents, and any required tax return to the IRS Austin Service Centre in Texas, or use an IRS Taxpayer Assistance Centre or an Acceptance Agent to submit in person. Acceptance Agents (authorised by the IRS) can certify your documents so you do not need to mail originals.
  • Processing time. The IRS states that ITIN processing takes 7 to 11 weeks when submitted by post, or faster through an Acceptance Agent. Plan accordingly if you are opening a bank account on a fixed timeline.

The honest barrier: the US address requirement

Every major US bank requires proof of a US physical address to open an account. This requirement exists because US banking regulations require banks to verify customer identity against a known address, and a foreign address alone does not satisfy their compliance processes.

In practice, this means the traditional US bank account route is straightforward for people who already spend significant time in the US ,  international students with university housing, professionals on work visas with a US employer address, or frequent travellers with US property. For people based entirely outside the US who receive USD income from clients or platforms, the process is more difficult and often requires a trip to the US specifically to open an account.

This is the gap that makes a Grey account a practical alternative for many non-residents.

Opening a USD account without a US address

Grey gives you a USD account without requiring a US address, a US TIN, or an in-person visit. You open your account online, receive a US account number and ACH routing number, and can start receiving USD payments from Upwork, Payoneer, international clients, and global payroll systems immediately. There is no minimum balance, no monthly fee for the account itself, and no requirement to ever set foot in the United States.

Where Grey differs from a traditional US bank account in practical terms:

Feature Traditional US bank (Chase/WF/BofA) Grey
US address required Yes, mandatory No
In-person visit required Yes (WF, BofA) or sometimes (Chase) No, fully online
SSN or ITIN required Often yes or foreign TIN No
USD ACH routing number Yes Yes
Hold USD balance Yes Yes
GBP and EUR accounts No Yes, included
Virtual card for spending Debit card (physical) Virtual Mastercard, Apple Pay and Google Pay
Convert to local currency Wire transfer with bank FX rate In-app conversion at competitive rates

The practical difference is most significant at the point of setup. A traditional US bank account is more powerful once you are established in the US ,  you build credit history, you have full FDIC-insured deposit access, and you can access the full range of US financial products. Grey is better suited to people who earn in USD, GBP, or EUR but are based in Nigeria, Ghana, India, Kenya, or another market ,  you receive, hold, and convert on your terms without the US address requirement.

If you are pursuing a traditional US bank account: practical tips

  • Call ahead: Confirm document requirements by calling the specific branch before visiting. Requirements can vary between branches of the same bank, and a wasted trip is expensive if you are travelling to the US specifically to open an account.
  • Visit at a quiet time: Banks are more likely to open accounts for non-residents during quieter periods in a branch. Monday mornings and mid-afternoon on weekdays tend to have shorter waits and more time for the representative to work through non-standard applications.
  • Bring supporting context: If you have a university, employer, or property in the US, bring documentation that demonstrates a genuine connection to the country. This is not always required but it helps representatives understand your situation and reduces the chance of a flat refusal.
  • Know your foreign TIN: All three banks accept foreign TINs in at least some circumstances. Research the specific TIN format your country issues (Nigeria issues a Tax Identification Number through FIRS, India issues a PAN card) and bring the original document.
  • Schedule before you travel: If you are visiting the US for other reasons and want to open a bank account while you are there, schedule your branch appointment before you arrive rather than trying to walk in on the day.

Which option is right for you

If you are already in the US or planning a trip: the traditional bank route is worth pursuing. A Chase, Wells Fargo, or Bank of America account gives you access to the full US banking infrastructure, credit building, FDIC insurance, Zelle, wire transfer access, and a financial relationship that becomes more useful the longer you are in the country. Bank of America has the most structured non-resident programme and is likely the clearest starting point.

If you are based outside the US and receive USD income from international clients or platforms: Grey gets you a functional USD account with ACH routing details immediately, without requiring a trip to the United States. It is a different product from a full US bank account, but for the specific problem of receiving USD earnings as a non-resident, it addresses the core need directly.

Opening a US bank account as a non-citizen is more accessible than many people expect, provided you choose the right option for your needs. If you're looking for a simpler way to receive USD payments without visiting the US, open a Grey account or donwload the app today. You'll get US account details, making it easy to receive money from clients, employers, and businesses worldwide

Further reading

How to withdraw from Payoneer to your Grey account

How to get your first remote job

How to withdraw your remote job salary at the best exchange rates

Last updated:

October 2, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

How to receive US dollar payments in India: 4 ways compared

•

•

2 min read

The default way Indian banks handle inbound USD is: receive the wire, convert to INR immediately at their own rate, credit your account in rupees, and deduct fees at every step. You never see the dollars. You never choose the conversion rate. You never decide when to convert. The bank decides all three, and the bank's rate is never the mid-market rate. That automatic conversion is where freelancers, consultants, and remote workers lose the most money on international payments.

The cost of this setup is not small. A 2% to 3% FX spread on every transfer, intermediary deductions on SWIFT wires, and receiving bank charges add up to lakhs lost annually for anyone earning regular USD income. This guide covers the four main ways to receive US dollar payments in India, what each one actually costs on a real invoice, the compliance requirements (purpose codes, FIRC, FEMA) that most payment guides skip entirely, and how to set up an infrastructure that gives you control over when and at what rate your dollars become rupees.

The four main ways to receive USD in India

1. US ACH or Fedwire transfers

ACH (Automated Clearing House) and Fedwire are US domestic transfer systems. When a US client pays you via ACH or Fedwire, the money moves within the US banking system to a US-based account. This is important because US companies strongly prefer paying vendors through their domestic payment rails. Their finance teams process ACH payments the same way they pay local contractors, which means less friction on the client side and faster approval on yours.

ACH transfers typically cost the sender nothing or a small flat fee (usually under $1). Fedwire transfers may cost the sender $15 to $30, depending on their bank. On your end, the cost depends on where the funds land. If you are receiving into a virtual USD account from a fintech provider, the provider charges a deposit fee (Grey charges 0.8%, minimum $2, maximum $10). There is no intermediary bank deduction because the payment never leaves the US banking system.

ACH is best for recurring payments from US-based clients, such as monthly retainers, project milestones, or regular consulting fees. If most of your clients are American, setting up a virtual USD account that supports ACH and Fedwire deposits is typically the lowest-cost option for regular income.

2. International wire transfers (SWIFT)

SWIFT is the global messaging network that banks use to route cross-border payments. When a client outside the US (or a US client whose bank does not support ACH to your provider) sends you a wire transfer, it travels through the SWIFT network. This is the most universally accepted method, but it is also the most expensive.

The costs stack up at multiple points. The sending bank charges a wire fee, typically $20 to $50, depending on the country and bank. If the payment routes through an intermediary (correspondent) bank, that bank deducts another $10 to $25 from the transfer amount. Your receiving bank may charge an additional inward remittance fee of $5 to $15. On a $2,000 invoice, total fees can range from $45 to $90, which is 2.25% to 4.5% before any currency conversion. Settlement takes 2 to 5 business days.

SWIFT makes sense for large, infrequent payments where the fixed fees represent a smaller percentage of the total: invoices above $5,000, corporate contracts, or one-off project payments. For smaller recurring payments, the per-transfer cost makes SWIFT significantly more expensive than ACH.

Also read: Top platforms to earn US dollars in India

3. Payment aggregators

Payment aggregators collect funds from your client (usually via card or local bank transfer) and remit the proceeds to your Indian bank account. The most common ones Indian freelancers encounter are PayPal, Razorpay (for businesses accepting international payments), and Stripe (with limited availability for payouts in India).

PayPal charges 2.99% on incoming goods and services payments, plus a currency conversion spread of 3% to 4% above mid-market when you withdraw to INR. On a $2,000 payment, that is roughly $60 in transaction fees plus $60 to $80 in conversion loss, totalling $120 to $140. Razorpay's international payment gateway charges 3% per transaction for international cards. These platforms are convenient for clients who prefer paying by card or who are not set up for bank transfers, but the cumulative cost is the highest of all four methods.

Aggregators are best for small, one-off projects where the client insists on paying by card, or for marketplace payouts (Upwork, Fiverr) where the platform dictates the payment method.

4. Cross-border transaction caps

India's cross-border payment framework includes transaction-level limits in certain categories. Some payment setups cap individual cross-border transactions at ₹25 lakh per unit of goods or services. If your invoice size approaches that range, bank-led rails such as SWIFT are usually more suitable than aggregator platforms. Having access to a USD receiving account through a provider like Grey gives you more flexibility when handling higher-value international payments, because the funds arrive in USD first and you control the conversion timing and method.

How the four methods compare
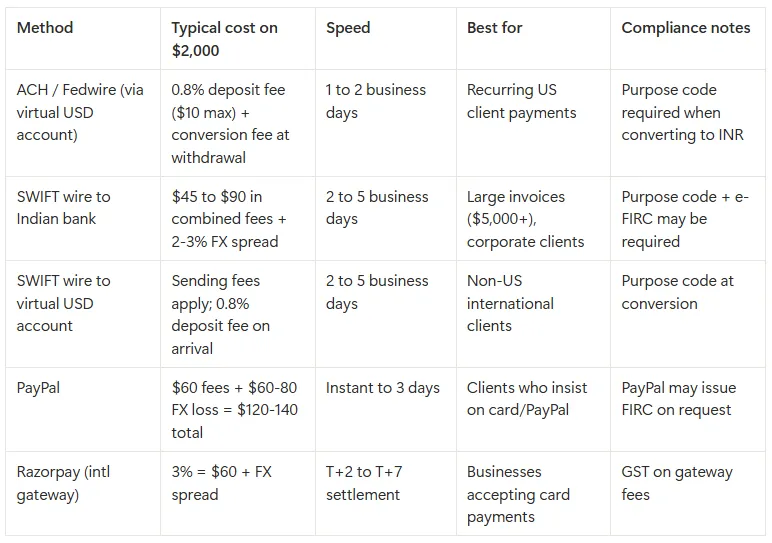
__wf_reserved_inherit

The compliance layer most freelancers overlook

Receiving USD payments in India is regulated under the Foreign Exchange Management Act (FEMA) and RBI reporting guidelines. Getting the compliance right upfront prevents delays, frozen transfers, and problems during audits.

Purpose codes

Indian banks require a purpose code on every inward remittance to classify the transaction under FEMA. Common codes for freelancers include those for software development, consulting, and marketing services. These codes are defined under the RBI purpose code list for inward remittances. Providing the correct code on your invoice and communicating it to your client's bank reduces the risk of your payment being held for manual review. Vague or missing purpose codes are one of the most common reasons for delayed credits.

You may also like: How to receive money from UK clients in India

FIRC and e-FIRC

If you export services (which includes freelancing for foreign clients), you may need a Foreign Inward Remittance Certificate (FIRC or e-FIRC) for GST export documentation, audits, and platform compliance. Only authorised dealer banks issue e-FIRC documentation. Confirm your bank's process for issuing these certificates in advance, because requesting them after the fact can take weeks. If you receive payments through a virtual USD account and then transfer to your Indian bank, the e-FIRC is issued by the Indian bank that receives the final INR credit.

‍

Export realisation timelines

India requires that export proceeds be realised (received in India) within a prescribed period. Long-pending invoices can create compliance issues. Keep your documentation organised and follow up on overdue payments early. For a complete explanation of FIRC requirements, tax implications, and RBI compliance rules, see Grey's guide on FIRC, taxes, and compliance for Indians earning foreign currency.

Which setup is right for your situation

The right payment method depends on three factors: where your clients are located, your average invoice size, and whether you want to hold USD or convert to INR immediately.

For most clients in the US, a virtual USD account that supports ACH and Fedwire is typically the lowest-cost option. Your US client pays you the same way they pay a local vendor. You receive the funds in USD, hold them until you are ready to convert, and withdraw to your Indian bank at a rate and time you choose. SWIFT works as a backup for clients whose banks do not support ACH to their provider.

Global clients across multiple countries: Ensure your account can receive international SWIFT wires without intermediary deductions eating into your payment. A multi-currency account lets you hold USD, GBP, or EUR and convert only when the rate is favourable, rather than accepting your bank's automatic conversion on arrival.

Large invoices ($5,000+): Direct bank rails (SWIFT or Fedwire) are preferable to aggregator platforms. The fixed fees are lower as a percentage of the total than the percentage-based fees aggregators charge. A $10,000 invoice through PayPal costs roughly $600-$700 in combined fees and FX losses. The same invoice received via SWIFT to a virtual USD account costs $10 in deposit fees plus the conversion cost when you move to INR.

Priority is maximising take-home INR. Compare the total cost at every step: incoming transfer fees, deposit fees, FX margin versus the mid-market rate, and withdrawal fees. Small differences in FX margins compound significantly over a year of regular payments. A 1% difference on $3,000 per month is $360 annually.

Also read: A guide for Indians getting paid by clients abroad

Common mistakes to avoid

Relying on a single payment method leaves you exposed if that channel has downtime, compliance issues, or fee changes. The safest setup is ACH or Fedwire as your primary rail with SWIFT as a fallback. Ignoring FX spreads is the most expensive mistake: the difference between mid-market and a 3% markup on $2,000 is $60 per transfer. Waiting until a compliance request arrives to organise your documentation can delay your funds for days or weeks. Sending invoices without detailed service descriptions triggers manual review at Indian banks because the purpose of the remittance is unclear. Include the service type, project reference, and your client's details on every invoice.

How Grey works for Indian freelancers receiving USD

Grey provides Indian freelancers, consultants, and remote professionals with USD, GBP, and EUR foreign currency accounts that can receive payments via ACH, Fedwire, or international SWIFT wire transfers. The setup is fully digital: sign up at grey.co or download the Grey app, complete KYC verification with your PAN card, Aadhaar, and proof of address, and your account details are available within 24 hours.

When a payment arrives via ACH or Fedwire, Grey charges a 0.8% deposit fee (minimum $2, maximum $10). The funds sit in your USD wallet. You can hold them in dollars for as long as you need, which is useful if you want to wait for a more favourable exchange rate or if you have USD expenses (software subscriptions, SaaS tools, advertising spend) that you can pay directly using a Grey virtual card. The virtual card costs $5 to create with no monthly maintenance fee. Transactions on USD-priced sites incur no additional fee; purchases on non-USD websites carry a 2% + $0.50 cross-border fee.

When you are ready to convert to INR, Grey charges a 1% conversion fee capped at $6 per transaction. The conversion rate is displayed before you confirm, so you see exactly how much INR you will receive. Transfers to your Indian bank account require your IFSC code and typically arrive the same day. You can check Grey's fee calculator to see the exact cost for any transaction amount before you commit.

Instead of relying on automatic bank conversions that happen at arrival, or juggling multiple platforms for different currencies, you receive USD through one account, manage your balance in dollars, and convert to INR when the timing and rate suit you.

Grey charges a 0.8% fee on deposits (minimum $2, maximum $10), a 1% conversion fee (capped at $6), and a withdrawal fee that varies by currency. Exchange rates on Grey are variable and include a margin over the mid-market rate. Cross-border card transactions on non-USD websites incur a 2% + $0.50 fee. Always review fees and the conversion rate before confirming a transaction.

How international wire transfers work: fees, time, receiving and cheaper alternatives

•

•

2 min read

If you’ve ever sent an international wire transfer, you probably know the amount you pay at the start isn’t always the full cost. Your bank might charge around $45 to send the money, the receiving bank may charge another $13, and if the payment passes through an intermediary bank, another $10 to $25 can disappear along the way. All that for a transfer that can still take 1 to 5 business days to arrive.

And those are only the fees you can easily see. Exchange-rate markups and intermediary charges can make the final cost considerably higher than the wire fee your bank advertises. In this guide, we’ll break down where those costs come from, how an international wire transfer actually works, how long it takes, how to receive one, and when paying for one makes sense compared with other ways to send money abroad.

An international wire transfer is an electronic payment sent from one bank to another across national borders, typically via the SWIFT messaging network. The sending bank debits your account, routes a payment instruction through one or more intermediary banks, and the receiving bank credits the recipient’s account. The process can involve currency conversion, compliance screening, and interbank settlement, which can affect both the cost and how long the transfer takes.

How an international wire transfer works, step by step

SWIFT isn't a payment system. It's a messaging network. This distinction matters because it explains why international wires are slow and expensive: SWIFT tells banks what to do, but the actual money moves through a separate settlement process between the banks themselves.

Here's what happens when you wire $1,000 from a US bank account to a recipient in Nigeria:

Step 1: You Initiate the Transfer

You tell your bank to send money internationally. You provide: the recipient's full name (exactly as it appears on their bank account), their bank name, their account number or IBAN, the receiving bank's SWIFT/BIC code, and the amount you want to send. Your bank charges an outgoing wire fee, typically $25 to $50.

Step 2: Your Bank Screens the Transaction

Before sending anything, your bank runs the transfer through compliance checks. In the US, the Office of Foreign Assets Control (OFAC) screens every international wire for connections to sanctioned countries, individuals, or entities. Your bank also checks for compliance with anti-money laundering (AML) rules and may flag transfers over $10,000 for IRS reporting. This screening takes minutes for routine transfers but can hold up unusual or high-value transactions for hours or days.

Step 3: Your Bank Sends a SWIFT Message

Your bank creates a SWIFT message (typically an MT103 for single customer transfers) containing the payment instructions. This message travels through the SWIFT network to the receiving bank. SWIFT assigns every bank a unique 8 or 11-character code called a BIC (Bank Identifier Code). For example, Wells Fargo's SWIFT code is WFBIUS6S. JPMorgan Chase's is CHASUS33. Your bank uses the recipient bank's BIC to route the message correctly.

Step 4: Intermediary Banks Process the Transfer

This is the step most guides skip, and it's where the hidden costs live.

If your bank has a direct relationship (called a correspondent banking relationship) with the recipient's bank, the transfer moves directly. But most banks don't have direct relationships with banks in every country. In that case, the transfer routes through one or two intermediary banks that do have those relationships.

Each intermediary bank can deduct a processing fee from the transfer amount, typically $10 to $25 per intermediary. If your $1,000 transfer passes through two intermediaries, $20 to $50 may be deducted before the money reaches the recipient. You won't see this on your bank statement. Your recipient just received less than you sent, and neither of you knows exactly where the money went.

This is the single biggest frustration with international wire transfers: the sender pays a $45 fee and expects the recipient to get $1,000, but the recipient gets $955 because an intermediary bank took $45 along the way. For a detailed comparison with ACH, see ACH vs wire transfer explained.

Step 5: Currency Conversion

If the sender's currency differs from the recipient's, someone has to convert it. This can happen at the sending bank, at an intermediary bank, or at the receiving bank, depending on the arrangement. Whoever converts the currency adds a markup to the mid-market exchange rate, typically 1-3% for retail customers. On a $1,000 transfer, a 2% markup costs $20 in hidden fees that never appear as a line item. You see it only if you compare the rate you got to the mid-market rate at the time of transfer.

Step 6: The Receiving Bank Credits the Recipient

The recipient's bank receives the SWIFT message, verifies the details, runs its own compliance checks, and credits the recipient's account. The receiving bank may charge an incoming wire fee (median $13 in the US, varies by country). The recipient sees the funds in local currency, minus any intermediary deductions and the receiving bank's fee.

How long does an international wire transfer take?

Most SWIFT wires take 1 to 5 business days, but the time depends on the network your payment travels on. Not every international transfer uses the same system. The network affects how fast it arrives, how much it costs, and where you can send money. Here’s a quick comparison:

Network Typical time Cost range Geographic scope Bank account required?
SWIFT
1 to 5 business days $15 to $50+ per transfer Global (200+ countries) Yes (sender and recipient)
SEPA 1 business day (instant SEPA: seconds) Free to low (EUR 0 to 5) Europe (36 countries, EUR only) Yes (IBAN required)
Faster Payments (UK) Seconds to 2 hours Usually free UK only (GBP) Yes (sort code + account number)
ACH (US) 1 to 3 business days (same-day ACH available) Free to $3 US domestic only (USD) Yes (routing + account number)
CHAPS (UK) Same day (by 5:20 pm) GBP 20 to 35 UK only (GBP, same-day guarantee) Yes
Fintech rails
(Grey, Wise, Remitly)
Minutes to hours Varies (typically lower than SWIFT) 80 to 170+ countries No (some deliver to mobile wallets)

‍

Here’s the main thing to know: SWIFT is the only network that works worldwide, but it’s often the slowest and most expensive. SEPA and Faster Payments are much quicker and cheaper, but only work within Europe and the UK. ACH is just for US payments. Newer fintech services help fill in the gaps, using local payment networks on both ends to speed things up. For more about SEPA, check out our SEPA transfer guide.

What causes international wire transfer delays?

If your international wire transfer is taking longer than expected, one of these six factors is almost always the reason:

Correspondent bank routing. Each intermediary bank in the chain processes your transfer individually. If a correspondent bank is slow (common on routes through less-connected markets), the entire transfer stalls. Tracking is limited once the transfer leaves your bank.

Cut-off times and time zones. A transfer initiated in New York at 3 pm EST on Friday won't be processed by a London correspondent until Monday morning GMT. That's two business days lost to timing alone.

Compliance and AML screening. Banks screen every international transfer against sanctions lists and anti-money-laundering databases. If your transfer triggers a flag (large, round amounts; first-time transfers to certain countries; or transfers to individuals with common names that match watchlist entries), manual review is required. This can add 1 to 3 business days.

Incorrect recipient details. A wrong account number, a misspelt name, or an invalid SWIFT code doesn't just delay the transfer. It bounces it back. You then need to re-initiate with corrected details, which restarts the clock entirely. This is the single most avoidable cause of delays.

Currency conversion. If your bank doesn't hold the recipient's currency, it needs to source it from a correspondent. Less commonly traded currencies (Nigerian naira, Ghanaian cedi, Kenyan shilling) take longer to source than major currencies (EUR, GBP, JPY).

Public holidays. Banks don't process transfers on public holidays in either the sending or receiving country. A transfer sent on a holiday in Nigeria won't be credited until the next business day there, even if your bank processed it immediately.

What an international wire transfer actually costs

The stated fee is never the total cost. Here's every layer:

Fee Layer Typical Range Who Pays
Outgoing wire fee (your bank) $25 to $50 Sender
Exchange rate markup 1 to 3% of transfer amount Sender (hidden in rate)
Intermediary bank fee(s) $10 to $25 per intermediary Deducted from transfer
Incoming wire fee (recipient bank) $0 to $20 Recipient
SWIFT messaging fee Included in wire fee Sender (bundled)

‍

Example: $1,000 wire from the US to Nigeria via a major US bank. Outgoing fee: $45. Exchange rate markup at 2.5%: $25. One intermediary deduction: $15. Incoming fee at the Nigerian bank: $10. Total cost: $95. The recipient receives the equivalent of $905 in naira, not $1,000. That's a 9.5% total cost on a $1,000 transfer.

On large transfers ($10,000+), the percentage cost drops because the flat fees become proportionally smaller. Wire transfers become more cost-effective as the amount increases. For small transfers (under $500), the fixed costs make wire transfers extremely expensive as a percentage of the total.

Domestic vs international wire transfer

Feature Domestic Wire International Wire
Network Fedwire (US), CHAPS (UK) SWIFT
Speed Same day (before cutoff) 1 to 5 business days
Typical fee $25 to $30 $35 to $50 + intermediary
Currency conversion None Required (adds cost)
Intermediary banks None 0 to 2 intermediaries
Compliance screening Standard AML OFAC + AML + destination rules
Reversibility Generally irrevocable Generally irrevocable
Tracking Real-time via Fedwire SWIFT GPI (if supported)

‍

Domestic wires are faster, cheaper, and simpler because the money stays within one country's banking system. No currency conversion. No intermediary banks. No cross-border compliance checks. The Fedwire system in the US processes domestic wires in real time during business hours, with final settlement the same day.

International wires are slower because the money crosses multiple banking systems, each with its own compliance requirements, business hours, and settlement schedules. A wire from New York to Lagos may pass through a correspondent bank in London, adding a full business day. Time zone differences mean that a wire initiated at 3 pm in New York arrives after business hours in Lagos, pushing settlement to the next local business day.

When to use a wire transfer and when to skip it

Wire transfers aren't always the right choice. They're designed for specific situations where their unique properties (irrevocability, same-day domestic settlement, no amount cap) justify the cost.

Use a Wire Transfer For

Large, one-off transactions where the fixed fees are a small percentage of the total. Buying property, closing a business acquisition, or paying a large invoice. On a $100,000 transfer, a $45 wire fee is 0.045% of the total. On a $500 transfer, it's 9%.

Time-critical payments where same-day or next-day settlement matters. Contract deadlines, supply chain emergencies, legal settlements. No other standard banking method offers this speed for large amounts.

Payments to countries or banks with no fintech coverage. If the recipient's bank isn't supported by any digital transfer service, a SWIFT wire may be the only option. This is common for transfers to some banks in Central Asia, parts of the Middle East, and smaller institutions in Africa.

Skip the Wire Transfer For

Regular transfers under $5,000. The fixed fees and exchange-rate markups can make wire transfers expensive for smaller amounts. A fintech service like Grey (1% capped at $6 for currencies including NGN, USD and EUR; see the full list of Grey conversion fees), Wise (0.41% to 1.5%), or Remitly ($0 to $4.99) may offer a lower overall cost for transfers under $5,000.

Recurring payments (monthly remittances, contractor payments, subscription invoices). The cost compounds. Twelve wire transfers at $45 each amount to $540/year in bank fees alone, before exchange-rate markups and intermediary deductions. A multi-currency account that receives via ACH or local payment rails eliminates most of this cost. For comparison, see SWIFT code vs routing number.

Payments where you need the recipient to receive the exact amount you quoted. Intermediary deductions are unpredictable. You might send $1,000, and the recipient might get $955 or $980 or $1,000, depending on which intermediaries handle the transfer. If the amount matters (paying an exact invoice, meeting a minimum deposit), a fintech service with transparent, upfront pricing is more reliable.

How to send an international wire transfer

If you've decided a wire is the right choice, here's what you need:

Information required: recipient's full legal name (as it appears on their bank account), recipient's bank name and branch address, recipient's account number or IBAN, receiving bank's SWIFT/BIC code, the amount and currency, and the purpose of the transfer (some banks and countries require this).

Where to initiate: most US banks let you send international wires through online banking, mobile app, by phone, or in-branch. Online is the fastest. Some banks restrict first-time international wires to in-branch or phone for security. Check your bank's policy before you need to send urgently.

Timing: initiate domestic wires at least 1 to 2 hours before your bank's cutoff time (usually 4 to 5 pm ET). For international wires, initiate 3 to 4 hours before the cutoff. Wires initiated after the cutoff are processed the next business day.

Tracking: ask your bank for the SWIFT reference number (also called a UETR under SWIFT GPI). The recipient's bank can use this to trace the transfer if it doesn't arrive within the expected window.

How to receive an international wire transfer

If someone abroad is wiring money to you, they need your bank's SWIFT code, your account number (or IBAN for European accounts), your bank's name and address, and your full name as it appears on the account. Some sending banks also ask for the receiving bank's routing number as a secondary reference.

What information does the sender need?

The exact fields vary by bank, but the standard set for an international wire transfer is:

Your full legal name as it appears on your bank account. A mismatch between the name on the wire and the name on the account can cause delays or rejection.

Your bank account number. For US accounts, this is typically a 10 to 12-digit number. For UK accounts, it is the account number plus sort code. For European accounts, it is the IBAN.

Your bank's SWIFT/BIC code. This identifies the bank internationally. It is 8 or 11 characters. Your bank can provide it, or you can look it up on the SWIFT directory.

Your bank's name and address. Some sending banks require the full branch address, not just the bank name.

Your address. The address on file with your bank.

Purpose of payment (sometimes). Some countries require the sender to state the reason for the transfer. India, for example, requires an RBI purpose code on every inward remittance.

Your bank may charge an incoming wire fee (ranging from $0 to $20, depending on the bank). The money arrives in the currency the sender specified, or your bank converts it to your local currency, usually at a marked-up rate.

Common problems when receiving international wire transfers

The received amount is less than expected. This usually means intermediary banks deducted fees in transit. Ask the sender for the MT103 document (the SWIFT payment confirmation), which shows exactly what was sent and any deductions along the way. If the sender selected the SHA or BEN fee instructions, intermediary costs are deducted from the transfer amount.

The transfer is delayed by more than 5 business days. Common causes: incorrect SWIFT code, the sender's bank holding the payment for compliance review, a public holiday in an intermediary country, or the payment arriving after the recipient bank's daily processing cutoff. Contact your bank with the MT103 reference number to trace it.

The sender used the wrong account details. If the sender entered an incorrect account number or SWIFT code, the payment may be rejected or credited to the wrong account. Most banks will attempt to return a misdirected payment, but this can take weeks and may incur additional fees. Double-check all details before the sender initiates the wire.

Your bank asks for documentation. Some banks, especially in regulated markets, may hold incoming international wires until you provide supporting documents: an invoice, a contract, or a letter explaining the source of funds. This is a standard anti-money-laundering procedure. Having your documentation ready before the transfer arrives avoids delays.

For people outside the US who need to receive USD wires regularly: you don't need a US bank account. Grey provides USD account details (ACH routing number and account number) that can receive incoming transfers from US banks. You can also receive GBP via FPS, CHAPS, or BACS, and EUR via SEPA. The money arrives in your chosen currency, and you decide when to convert. No intermediary bank deductions, no surprise fees. Open a Grey account and share your account details with anyone who needs to pay you. You can also send money from the US through Grey's own transfer rails, bypassing SWIFT entirely.

Frequently asked questions about international wire transfers

How long does an international wire transfer take?

Most international wire transfers take 1 to 3 business days. Some take up to 5 business days if they route through multiple intermediary banks or if the destination country has additional compliance requirements. Domestic wires settle the same business day. Time zone differences, local bank holidays, and enhanced screening on large or unusual transfers can all add delays. Ask your bank for the SWIFT GPI tracking number to monitor the transfer in real time.

How much does an international wire transfer cost?

The median outgoing fee at US banks is $45. The median incoming fee is $13. But the stated fee isn't the total cost. Exchange-rate markups (1-3%) and intermediary bank deductions ($10-$25 per intermediary) can double the effective cost. For a $1,000 transfer, the all-in cost can range from $80 to $100. On large transfers ($10,000+), the percentage cost drops because flat fees are proportionally smaller.

Does a wire transfer go through on weekends?

Traditional SWIFT wire transfers don't process on weekends. If you initiate a transfer on Saturday, it won't begin moving until Monday. Some fintech services process transfers on weekends because they use their own settlement networks rather than relying on banking-hours-only SWIFT rails. If timing is critical, check whether your provider processes weekend transfers before sending.

Can I speed up an international wire transfer?

Partially. Initiate the transfer early in the day (before your bank's cut-off time). Use a debit card or pre-funded account if your bank offers this option (some banks process card-funded transfers faster). Double-check all recipient details before confirming to avoid bouncebacks. And consider using a fintech transfer service instead of SWIFT for corridors where speed matters more than the traditional banking route.

How do I track an international wire transfer?

Ask your bank for the SWIFT reference number (also called the UETR if they use SWIFT gpi). SWIFT gpi provides end-to-end tracking with real-time status updates. Not all banks have adopted GPI yet, in which case tracking is limited to your bank confirming when they sent the message and the recipient bank confirming when they received the funds.

What is a SWIFT code and how do I find one?

A SWIFT code (also called a BIC) is an 8 or 11-character code that identifies a specific bank on the SWIFT network. The format is: 4 letters (bank code) + 2 letters (country) + 2 characters (location) + 3 optional characters (branch). For example, WFBIUS6S is Wells Fargo (WFBI), United States (US), San Francisco (6S). You can find any bank's SWIFT code on its website, by calling the bank, or by searching the SWIFT directory at swift.com.

What is an MT103 and why does it matter?

An MT103 is the SWIFT payment confirmation document. It shows the amount sent, the sender and recipient details, the intermediary banks involved, and any fees deducted along the way. If your transfer is delayed or the received amount is less than expected, the MT103 is the document you need to trace the payment and identify where fees were deducted.

Can I receive an international wire transfer without a SWIFT code?

Not through the traditional SWIFT network. However, if the sender can make a domestic transfer in the same currency (for example, a US sender making an ACH transfer to your US-denominated account), no SWIFT code is needed. Multi-currency accounts like Grey provide local account details in USD, GBP, and EUR, allowing the sender to transfer domestically.

Can an international wire transfer be reversed?

Generally no. Wire transfers are designed to be irrevocable once processed. If you sent money to the wrong account, contact your bank immediately. They can request a recall through SWIFT, but the receiving bank is not obligated to return the funds, and the process can take weeks. This irrevocability is a feature for recipients (guaranteed funds) but a risk for senders. Always verify the recipient's details twice before confirming a wire.

What is the difference between a wire transfer and an ACH transfer?

Wire transfers are processed individually and settle the same day (domestically). They're irrevocable, have no amount cap, and cost $25 to $50. ACH transfers are batched, settle in 1 to 3 business days, are reversible in some cases, have lower fees (often free or under $3), and may have daily limits. Use wire for large, urgent, one-off payments. Use ACH for recurring transfers, payroll, and smaller amounts. For a detailed comparison, see ACH vs wire transfer explained.

Do I need a bank account to receive an international wire transfer?

You need an account that can receive SWIFT or domestic bank transfers. This can be a traditional bank account or a fintech account with its own banking details. Grey provides USD, GBP, and EUR account details that can receive wire transfers and ACH deposits without requiring a local bank account in the US, UK, or Europe. Open a Grey account to get your own receiving details.

Skip the $45 wire fee. Open a Grey account and receive USD, GBP, and EUR with your own account details. Convert when the rate works for you, and send to 50+ countries.

Disclaimer: This article is for informational purposes only. Wire transfer fees, exchange rates, and processing times vary by bank and may change. Transfer times and network availability vary by provider and corridor, and all timelines cited are typical ranges, not guarantees. Grey isn't a bank. We're a licensed financial services provider offering multi-currency accounts.

Wells Fargo routing numbers by state (ACH and wire)

•

•

2 min read

A payment is ready to go, but the form asks for one more detail: your Wells Fargo routing number. You know your account number and which Wells Fargo branch you use, but finding the right nine-digit number can be less obvious than expected. And getting it wrong can delay the payment or send you back to the form to start again.

Wells Fargo uses different ACH routing numbers depending on the state where the account was opened, and one number for domestic wire transfers across all states. The most commonly used numbers are 121042882 for California ACH and 121000248 for domestic wire transfers. Always confirm your specific routing number in the Wells Fargo app or by calling the number on the back of your card.

Which Wells Fargo number do I need?

  • Direct deposit and ACH payments: use the routing number for the state where your account was opened (see the table below), and confirm it in your account details.
  • Domestic wire transfers: use 121000248.
  • International wires: a routing number is not enough. Wells Fargo lists the SWIFT code WFBIUS6S for its US international services centres, so confirm the right code for your account with Wells Fargo before sending.

Knowing which Wells Fargo routing number to use matters when setting up direct deposits, receiving ACH payments, or sending a domestic wire. The right number depends on the transaction, so checking before submitting your payment details can help you avoid unnecessary delays.

Also read: How to open a Wells Fargo account from outside the US

Wells Fargo ACH Routing Numbers by state

The Wells Fargo routing number you need depends on the state where your account was opened. While some states share the same number, others have their own ACH routing number. The table below lists the routing numbers provided for each state, including the specific number shown for El Paso, Texas. Before using any of these numbers for a payment or direct deposit, check your Wells Fargo account details to confirm that you have the correct routing number for your transaction.

State ACH Routing Number State ACH Routing Number
Alabama 062000080 Montana 092905278
Alaska 125200057 Nebraska 104000058
Arizona 122105278 Nevada 321270742
Arkansas 111900659 New Hampshire 121042882
California 121042882 New Jersey 021200025
Colorado 102000076 New Mexico 107002192
Connecticut 021101108 New York 026012881
Delaware 031100869 North Carolina 053000219
Florida 063107513 North Dakota 091300010
Georgia 061000227 Ohio 041215537
Hawaii 121042882 Oklahoma 121042882
Idaho 124103799 Oregon 123006800
Illinois 071101307 Pennsylvania 031000503
Indiana 074900275 Rhode Island 121042882
Iowa 073000228 South Carolina 053207766
Kansas 101089292 South Dakota 091400046
Kentucky 121042882 Tennessee 064003768
Louisiana 121042882 Texas 111900659 (El Paso: 112000066)
Maine 121042882 Utah 124002971
Maryland 055003201 Vermont 121042882
Massachusetts 121042882 Virginia 051400549
Michigan 091101455 Washington 125008547
Minnesota 091000019 West Virginia 121042882
Mississippi 062203751 Wisconsin 075911988
Missouri 113105449 Wyoming 102301092

Wells Fargo wire transfer Routing number

When you send a domestic wire transfer from your Wells Fargo account, you use a single nationwide routing number rather than a state-specific number. The routing number for domestic wires is 121000248, so you do not need to search for a different number based on where your account was opened.

For an international inbound wire, you will need the Wells Fargo SWIFT code instead. Wells Fargo lists the SWIFT code WFBIUS6S for its US international services centres, which helps identify Wells Fargo when money is being sent internationally. Confirm the right code for your account with Wells Fargo before you share it. Understanding the difference between a SWIFT code and a routing number becomes important here because each one identifies your bank for a different type of payment.

The same distinction helps when looking at ACH vs wire transfers. ACH payments move through delayed electronic batches using state-specific regional clearinghouses, while wire transfers are processed individually in real time. When you send a wire, the transaction is settled directly through the Federal Reserve system rather than waiting for an ACH batch. That difference in processing is why the correct routing or SWIFT details matter when sending money to your Wells Fargo account.

Sources: the wire routing number and SWIFT code above were checked on 13 November 2026 against Wells Fargo's routing and account number page and its international resources page. Wells Fargo does not publish the state ACH list on those pages, so always confirm your own number in your account details.

Where to find your Wells Fargo routing number

Finding your Wells Fargo routing number is usually straightforward, and the quickest method depends on whether you have access to the mobile app, a cheque or online banking.

Check the Wells Fargo mobile app

Open the Wells Fargo app and sign in to your account. Select the account you need, then look for Account Details. Your routing number should appear alongside your account number and other account information.

Look at a Wells Fargo cheque

A Wells Fargo cheque also shows the routing number. Turn the cheque over to the bottom-left section of the front. The first nine-digit number in the sequence is the routing number, followed by your account number and cheque number.

Find it through Wells Fargo online banking

Sign in through the Wells Fargo website and select the relevant account. Open the account details or information section to view the routing number associated with that account. Make sure you are checking the correct account before sharing the details.

Need a USD account without Wells Fargo?

Getting paid by a US client can become frustrating when the payment requires US banking details that you do not have. Opening a traditional US bank account may not be practical either, especially when you live abroad and do not have a US residential address or the documents a local bank expects.

Grey gives eligible users access to USD account details that can be used to receive supported ACH and wire transfers, without requiring a US residential address. So when a client or employer asks for US banking details, you can provide the relevant information without opening a traditional Wells Fargo account.

Once your account is approved, the USD account details are available digitally, giving you a simpler way to receive eligible payments and manage the money online. Sign up for Grey or download the app to get started.

Frequently asked questions about Wells Fargo routing numbers

What is Wells Fargo's routing number for direct deposit?

The routing number for Wells Fargo direct deposit depends on the type of account and payment. Unlike domestic wire transfers, direct deposits use the ACH routing number associated with your account. Check your Wells Fargo account details or cheque rather than assuming the wire routing number applies.

Is the Wells Fargo ACH number different from the wire number?

Yes. ACH payments and domestic wire transfers can use different routing numbers. Wells Fargo uses 121000248 for domestic wire transfers, while your ACH routing number may differ. Checking the payment instructions before sending or receiving money helps ensure the transaction reaches the correct account without unnecessary delays.

Does Wells Fargo have one routing number for all states?

Wells Fargo uses a single routing number for domestic wire transfers nationwide: 121000248. However, ACH routing numbers can vary depending on where your account was opened. That means the answer depends on the type of payment you are making and the specific Wells Fargo account involved.

Where is the routing number on a Wells Fargo cheque?

Your Wells Fargo routing number appears along the bottom of the cheque. It is the first nine-digit number in the sequence, followed by your account number and cheque number. Looking at the bottom-left corner of the cheque makes it easy to identify the routing number quickly.

Can I use my Wells Fargo routing number for international transfers?

A routing number alone is generally not enough for an international wire transfer. International payments usually require Wells Fargo’s SWIFT code, along with your account details. Wells Fargo lists the SWIFT code WFBIUS6S for its US international services centres, while domestic wires use the routing number.

What is a routing number and where do you find it on a cheque?

•

•

2 min read

Did you know that 92% of Americans get their pay through direct deposit? Every one of those paychecks relies on a routing number, a simple nine-digit code that quietly does the work of making sure your money ends up in the right place.

A routing number is a nine-digit code that helps identify your bank during financial transactions. You'll usually see it printed at the bottom left of your cheque, right before your account number. These numbers are used for all sorts of things: direct deposits, ACH transfers, and domestic wires. But here's the catch: your bank might use different routing numbers for different types of transfers, such as ACH versus wire transfers.

If you've ever been asked for your routing number and had no idea where to look, don't worry, you're not alone. In this article, we'll explain exactly what a routing number is, how to find yours in less than a minute, and why some banks have more than one.

What is a routing number?

A routing number, sometimes called an ABA routing transit number, is a unique nine-digit code given to every US bank and credit union by the American Bankers Association (ABA). It's basically your bank's address in the world of finance, telling other banks where to send your money.

The first four numbers show which Federal Reserve district and processing centre your bank belongs to. The next four digits point to your specific bank within that district. The last digit is a sort of checksum: it helps make sure the number is valid.

Here's something that surprises a lot of people: your bank might have more than one routing number. That's because banks often use different numbers for different types of transactions, depending on which Federal Reserve network processes them:

  1. ACH routing number: Used for direct deposits, bill payments, and electronic transfers. Processed through FedACH in batches.
  2. Wire routing number: Used for domestic wire transfers. Processed through Fedwire individually in real time.
  3. Cheque routing number: Printed on the bottom of paper cheques. Processed through the Federal Reserve's cheque clearing system.

Some banks keep it simple and use the same routing number for all transactions. Others, like Wells Fargo, have different numbers by state for ACH transactions, while the wire number stays the same across the country. So, always double-check which one you need before you send or receive money.

Where to find your routing number

Here are the three quickest ways to find your routing number, ranked from fastest to slowest:

1. Your bank's mobile app: Just open your banking app, tap on your account, and look for something like "Account Details" or "Routing Number." This is usually the fastest way. Most people can find it in under 20 seconds.

2. On a cheque: If you have a cheque handy, glance at the bottom left corner. The routing number is the first set of nine digits, tucked between two funny-looking symbols (they're called MICR symbols). The next set is your account number, and the smallest set is the cheque number.

3. Your bank's website: Log in to your online banking, head to your account summary, and look for "Routing Number" in your account details. If you're stuck, just type "routing number" into the site's search or help section.

If those options don't work (maybe you don't have a cheque, the app, or online banking), you can always call your bank's customer service (the number is on the back of your debit card). They'll just need to verify who you are before giving you your routing number.

One tip: double-check whether your bank uses different routing numbers for cheques and electronic transfers. The number on your cheque might not be the right one for direct deposit or ACH payments. When in doubt, use the number from your app or online banking.

Where is the routing number on a cheque (check)?

Look at the bottom-left corner of a standard US cheque. The first group of numbers is nine digits long and is usually framed by two small symbols. This is your routing number. From left to right, you will see three groups of numbers:

  1. Routing number (nine digits): identifies your bank.
  2. Account number (varies in length, typically 8 to 12 digits): identifies your specific account.
  3. Cheque number (typically 3 to 4 digits): identifies this specific cheque. The same number also appears in the top-right corner of the cheque.

These numbers are printed in a special magnetic ink font called MICR (Magnetic Ink Character Recognition), which lets banks and cheque-processing machines read them automatically. The whole line of numbers at the bottom of a cheque is called the MICR line. Business cheques follow the same layout: the routing number is the first group of nine digits in the bottom-left corner.

A routing number is also called an ABA routing number, after the American Bankers Association, which administers the system. "ABA routing number" and "routing number" refer to the same nine-digit code. Larger banks often have several, one for each region or for different types of transactions, so confirm the number you need with your bank.

Routing number vs account number: What is the difference?

You'll usually need both your routing and account numbers for most transactions, but they do different jobs. The routing number identifies your bank, while your account number identifies your specific account at that bank. Here's a quick breakdown:

Routing Number Account Number
9 digits, always 8 to 17 digits (varies by bank)
Identifies your bank Identifies your specific account
Bottom left of the cheque Next to the routing number on the cheque
Same for all customers at the same bank (in the same state) Unique to you
Shared with employers, billers, and transfer recipients Shared with the same parties, but more sensitive
Public (can be looked up online) Private (only you and your bank know it)

‍

The main thing to remember: your routing number is public; anyone can look it up. But your account number is private. Don't share it with just anyone, since someone with both could try to pull money from your account. You need both numbers for ACH and wire transfers, so keep them together.

When do you need a routing number?

You'll need to share your routing number in the following situations:

  1. Setting up direct deposit. Your employer will ask for your routing and account numbers so they can deposit your paycheck directly into your account. Use your ACH routing number (not the wire one) for this.
  2. Sending or receiving a domestic wire transfer. The person sending you money will need your wire routing number (which may differ from your ACH number) and your account number.
  3. Setting up automatic bill payments. When you sign up for recurring payments, like utilities or subscriptions, they'll use your routing and account numbers to take money out via ACH.
  4. Moving money between banks. If you're transferring funds between your accounts at different banks, you'll need the routing numbers for both.

For international wire transfers, you won't use a routing number at all. Instead, the sender will need your bank's SWIFT or BIC code. Want to know more about the difference? Check out our guides on SWIFT codes vs routing numbers andACH vs wire transfers.

Routing numbers for Major US banks

The table below lists primary ACH routing numbers for major US banks, while highlighting where routing numbers may vary by state or account.

Bank ACH primary routing number
Chase 021000021
Citibank 021000089
Bank of America 026009593
US Bank 091000022
Wells fargo Varies by state (e.g., 121000248 for CA). See Wells Fargo routing numbers by state.

‍

Routing numbers identify the bank involved in a payment, but the correct number can vary by state and transaction type, so confirm it before sending money.

Frequently asked questions

Is a routing number the same as a sort code?

They're basically the same thing, but for different countries. Routing numbers are for the US (9 digits); sort codes are for the UK (6 digits). Both help identify a bank and a branch when you're making domestic payments. If you're sending money between a US and UK account, you'll use a routing number on the US side and a sort code.

Can two banks have the same routing number?

Nope, each routing number is unique to one bank (or sometimes a specific branch or region). The American Bankers Association assigns them, so no two operating banks will have the same one. If banks merge, the old routing numbers are either phased out or reassigned.

What happens if I give the wrong routing number?

If you give the wrong routing number, your payment might bounce back or go to the wrong bank. If it bounces, you just have to fix the number and try again. If it lands in the wrong bank, your bank will need to work with the other one to get your money back, which can take a while, so it's best to double-check before hitting send.

Where is the routing number on a Bank of America cheque?

Look at the bottom left corner of your Bank of America cheque. The first nine digits are your routing number, then comes your account number, and finally the cheque number. Just remember, Bank of America uses different routing numbers for each state, so the one on your cheque depends on where you opened your account.

Where is the routing number on a business cheque?

In the same place as on a personal cheque: the bottom-left corner, as the first group of nine digits in the MICR line. Business cheques follow the same standard layout.

Is the routing number the same for everyone at my bank?

Often, yes. Smaller and regional banks may use a single routing number for all their accounts. Larger national banks often use different routing numbers depending on the state or region where an account was opened, and some use separate numbers for ACH and wire transfers. Always confirm your specific routing number with your bank instead of relying on a general search result.

Is it safe to share my routing number?

Your routing number identifies your bank, not your account, and it is public. On its own it cannot be used to reach your money. Together with your account number, though, it can be used to set up payments, including debits, so only share both numbers with parties you trust and expect to be paying you or billing you.

What is an ABA routing number?

ABA stands for American Bankers Association, the organisation that administers the routing number system in the United States. "ABA routing number" and "routing number" refer to the same nine-digit code.

Can I find my routing number without a cheque?

Yes! Check your bank's mobile app under Account Details, log in to your bank's website, give customer service a call, or search online for your bank's name plus "routing number." Most banks make these numbers easy to find on their help pages.

Do I need a routing number for Zelle or Venmo?

Not usually. Zelle and Venmo use your email or phone number to send and receive money. But when you first link your bank account, you might need to provide your routing and account numbers to set things up. After that, you just use your email or phone number for transfers.

Not a US bank customer? You can open a Grey account and get your own USD routing and account details, so you can receive payments from US clients or employers, even if you don't have a US address.

Disclaimer: This article is for informational purposes only. Routing numbers, account details, and bank procedures can change over time. Always double-check with your bank before using any number for a financial transaction. Grey isn't a bank. We're a licensed financial services provider offering multi-currency accounts.

BBVA Mexico SWIFT code and how to send money to BBVA

•

•

2 min read

Trying to send money to a BBVA account in Mexico without the SWIFT code is like trying to mail a package without an address. A SWIFT code is a short combination of letters and numbers that informs the international banking system exactly where your money needs to go.

The SWIFT code for BBVA Mexico (BBVA Bancomer) is BCMRMXMM, used to route international transfers to a BBVA account in Mexico. You need it, along with the recipient's account number or CLABE, to send money from abroad. Always confirm the code with the recipient or BBVA before sending.

BBVA Mexico SWIFT/BIC code: BCMRMXMM

If you are sending money internationally to a BBVA Mexico account, whether to pay a supplier, support family, or settle a personal transaction, you need this code to route the transfer correctly. This guide explains what the code means, how to find it yourself, and what else you need to complete a successful transfer.

What is the BBVA Mexico SWIFT code?

BBVA Mexico is Mexico’s largest financial institution, established in 1932 with its headquarters in Mexico City.  It is the most profitable overseas subsidiary of BBVA Spain, its parent institution.

BBVA Mexico's SWIFT/BIC code is BCMRMXMM
You may also see it written as BCMRMXMMXXX, where the XXX identifies the head office. Both formats can be accepted for international transfers.

A SWIFT code is also called a Bank Identifier Code (BIC). It refers to an 8 to 11-character code that identifies a bank when sending money internationally. It tells the sending bank where to send the transfer. It may also specify the branch and location to route the transfer to.

BBVA Mexico was formerly known as BBVA Bancomer until 2019, when the bank rebranded. However, the SWIFT code BCMRMXMM remained unchanged after the rebranding. Only the bank’s name changed from BBVA Bancomer to BBVA Mexico, S.A. So, if you see older documentation referencing "BBVA Bancomer," the SWIFT code shown there is still valid.

BBVA Mexico's code (BCMRMXMM) is different from BBVA Spain’s code (BBVAESMMXXX). These are separate entities, even though BBVA Spain is the parent institution. If you're sending money to a Mexican BBVA account, use the Mexico-specific code. If you use BBVA Spain’s code instead, your money will be routed to the wrong account and may not be recoverable.

How to find the SWIFT code yourself

If you're unsure which SWIFT code to use, you can check:

  • Through online or mobile banking: If you or the recipient has access to BBVA Mexico's online banking or mobile app, the SWIFT/BIC code is usually listed under account details or international transfer information.
  • On a bank statement: Some BBVA Mexico statements include the SWIFT code with your account information.
  • On BBVA's official website: Check BBVA Mexico's website to confirm the current SWIFT codes for international transfers.
  • Directly from the recipient: If you're sending money to someone with a BBVA Mexico account, ask them to confirm their banking details before making the transfer. Some branches may have an extended SWIFT code.

SWIFT code vs CLABE: what is the difference?

If you're sending money to a BBVA Mexico account, you may need both the SWIFT code and CLABE, but they serve different purposes.

  • The SWIFT code (BCMRMXMM) identifies the bank in Mexico that receives the payment and how to route the transfer from the sending bank to BBVA Mexico. Think of it as the bank's international address that tells the international banking network where to send the money.
  • The CLABE (Clave Bancaria Estandarizada) is an 18-digit standardised interbank code unique to Mexico. It is required for all electronic transfers within the Mexican banking system. It identifies the specific account within BBVA Mexico where the funds should be paid. Think of it as identifying the specific mailbox at the address the SWIFT code points you to.

For an international wire transfer to a BBVA Mexico account, you generally need both the SWIFT code to route the transfer to the correct bank and the CLABE to ensure the funds land in the correct account.

How to send money to a BBVA Mexico (Bancomer) account

To send money to a BBVA Mexico account (the bank formerly called BBVA Bancomer) from abroad, ask your bank for an international wire and give it the recipient's full legal name, their 18-digit CLABE, the SWIFT code BCMRMXMM, and the bank's name and address. If you would rather avoid wire fees, you can also send through a transfer service such as Grey's US to Mexico route. The steps for a bank wire are below.

Step 1: Confirm all the recipient's details

You need the recipient's full legal name, their CLABE (18 digits), the SWIFT code (BCMRMXMM, or the specific branch code if provided), and the bank's name and address.

Step 2: Initiate the transfer through your bank

Log in to your bank's online platform or visit a branch. Select international wire transfer and enter the recipient's details exactly as provided, including the SWIFT code and CLABE.

Step 3: Enter the details

Enter the recipient's information exactly as provided. Double-check the SWIFT code and CLABE before continuing.

Step 4: Confirm the transfer currency

Depending on your bank and the recipient's account, you may be able to send USD or MXN. Confirm which currency the recipient expects before sending.

Step 5: Review fees before confirming

Your sending bank will typically charge an outgoing wire fee, commonly $25 to $50 for international wires from US banks. Correspondent banks in the routing chain may deduct additional fees before the funds reach BBVA Mexico.

Step 6: Track the transfer

Save the transfer reference your bank provides so you can track the payment if there is a delay. Many banks now support SWIFT GPI tracking, which shows where the transfer is in the routing chain and its estimated arrival time.

International wire transfers to Mexico typically take 1 to 5 business days, depending on the sending bank, the currency, and whether the transfer passes through one or more correspondent banks.

If you regularly send to Mexico, opening a multi-currency account can simplify the process rather than using international wires each time. You can hold money in your preferred currency before converting it for a transfer to Mexico.

A cheaper way to send money to Mexico

Traditional SWIFT transfers can come with several fees. Your bank may charge an outgoing wire fee, correspondent banks may deduct undisclosed fees along the way, and the exchange rate may include an additional 1-5% markup. These costs can reduce the amount your recipient receives.

Sending money from the US to Mexico with Grey offers a transparent alternative. You can see the exchange rate and transfer fee before confirming, so you know how much your recipient will receive in Mexican pesos. This is particularly useful for regular transfers, whether supporting family, paying a Mexican contractor, or handling personal finances across the two countries.

If you're planning a trip and sending money, our guide on the best time to visit Mexico covers weather, seasons, and money tips.

Send money to Mexico with Grey and avoid international wire fees, correspondent bank charges, and hidden exchange-rate markups.

Frequently asked questions about BBVA Mexico’s SWIFT code

What is BBVA Mexico's SWIFT code?

BBVA Mexico's SWIFT/BIC code is BCMRMXMM, sometimes shown as BCMRMXMMXXX. This code identifies BBVA Mexico's head office for international wire transfers. Some branches may have extended codes (such as BCMRMXMMPYM), so it's always best to confirm with the recipient before sending.

How do I send money to BBVA Bancomer from the US?

Bancomer is the former name of BBVA Mexico, so you send money to the same bank. Ask your bank for an international wire and provide the recipient's full legal name, 18-digit CLABE, the SWIFT code BCMRMXMM and the bank's name and address. Your bank will usually charge an outgoing wire fee, and correspondent banks may deduct more in transit. A transfer service such as Grey can be an alternative if you want the exchange rate and fee shown before you send.

Is BBVA the same as Bancomer?

Yes, in the sense that BBVA Mexico was formerly branded as BBVA Bancomer before a 2019 rebrand. It is the same institution with the same SWIFT code (BCMRMXMM) as before the name change. If you have older documentation or contacts referencing "Bancomer," the bank details remain accurate; only the name has updated.

Do I need the CLABE too?

Yes. The SWIFT code alone routes your transfer to BBVA Mexico as an institution, but it does not identify a specific account. The 18-digit CLABE (Clave Bancaria Estandarizada) identifies the exact account the funds should be credited to. Both are required for a complete and accurate international transfer to a Mexican bank account.

How long does a transfer take?

International wire transfers to BBVA Mexico typically take one to five business days, depending on your sending bank, the currency used, and whether the transfer passes through one or more correspondent banks in transit. Transfers sent through platforms using local payment networks rather than the full SWIFT correspondent chain can settle faster.

What are the fees?

Standard SWIFT wires from US banks typically incur an outgoing fee of $25 to $50, plus potential correspondent bank deductions of $15 to $30 in transit, and a currency conversion margin if the transfer is converted to Mexican pesos, generally 1% to 5% above the mid-market rate. These costs are not always fully disclosed before you send.

Is there a cheaper alternative to a SWIFT wire?

Yes. Platforms like Grey process international transfers with fees and exchange rates disclosed before you confirm. They often route payments through local payment networks rather than the traditional SWIFT correspondent-bank chain. This avoids the additional costs of a standard bank wire. This is often a cheaper alternative to a SWIFT wire, especially for regular transfers to Mexico.

Navy Federal wire transfer: how to send, fees and limits

•

•

2 min read

Navy Federal's routing number for wire transfers is 256074974. To send a wire, you complete Navy Federal's wire transfer form and submit it by secure message, at a branch, by phone or by mail. Domestic wires cost $20 and international wires cost $25.

Sending money by wire transfer is one of the fastest ways to move funds when timing matters. Whether you're paying for a property purchase, covering an urgent bill, supporting family, or transferring large sums securely, getting every detail right is essential. A single incorrect routing number or missing banking detail can delay your payment, cause unnecessary stress, or even result in additional fees. That's why understanding how Navy Federal wire transfers work before you initiate one can save you both time and money.

If you bank with Navy Federal Credit Union, knowing the correct routing number is only the first step. You'll also need to understand the differences between domestic and international wire transfers, what information recipients must provide, and the costs involved. Having this information ready helps ensure your transfer reaches its destination without avoidable complications.

This guide explains the Navy Federal wire transfer routing number, how to send both domestic and international wire transfers, the details you'll need before you begin, applicable fees, and practical tips to help your transfer go through smoothly the first time.

Navy Federal wires at a glance

  • Routing number: 256074974.
  • Domestic wire: $20 fee, with an expected wait of 1 to 2 business days.
  • International wire: $25 fee, with an expected wait of 5 to 7 business days.
  • How to request one: complete Navy Federal's wire transfer form and send it by secure message in online or mobile banking, at a branch, by phone or by mail.

Source: Navy Federal wire transfers page, checked on 13 November 2026.

Also read: Wire transfer vs ACH: cheapest way to receive USD

Navy Federal routing number for wire transfers

The Navy Federal Credit Union wire transfer routing number is 256074974. This is the routing number you should use when sending or receiving a domestic wire transfer through your Navy Federal account. Entering the correct routing number is essential, as it helps ensure your funds are routed to the right financial institution and prevents processing delays.

You may also see the wire transfer routing number referred to as an ABA routing number or ABA transit number. Assigned by the American Bankers Association (ABA), this unique nine-digit number identifies financial institutions in the United States for wire transfers and other banking transactions. Whenever you're asked to provide the ABA routing number for a Navy Federal wire transfer, use 256074974.

Also read: How ACH payments work for freelancers outside the US

How to send a domestic wire transfer with Navy Federal

Navy Federal does not let you key in a wire directly in online banking or the app. Instead, you complete its Domestic Wire Transfer Form and send it in. Have the recipient's banking details ready first to avoid delays.

  1. Gather the details: your name, address and account number, plus the recipient's name, account number, bank routing number and bank name.
  2. Complete the Domestic Wire Transfer Form from Navy Federal's wire transfers page.
  3. Submit the form by secure message in online or mobile banking, at a branch, by phone on 1-888-842-6328, or by mail.
  4. Wait for Navy Federal to contact you to process the wire, then keep the confirmation for your records.

Navy Federal lists an expected wait of 1 to 2 business days for domestic wires. Timing can vary depending on the receiving bank.

How to send an international wire from Navy Federal

Sending an international wire transfer through Navy Federal requires a few more details than a domestic transfer because the payment must pass through the global banking network. Before starting your transfer, confirm the recipient's banking information to minimise delays or rejected payments.

To complete the transfer, use Navy Federal's International Wire Transfer Form and provide the recipient's full name, account number, recipient bank name and address, the bank's SWIFT/BIC code, and the IBAN (International Bank Account Number) where applicable. Some countries may also require additional payment instructions or the details of an intermediary bank. Navy Federal recommends using the wiring instructions provided by the recipient's financial institution to ensure the funds are routed correctly.

Navy Federal lists an expected wait of 5 to 7 business days for international wires. Third-party wire requests over $5,000 must be submitted in writing, through a secure message or at a branch. Navy Federal's page does not publish a maximum limit for international wires, but larger transactions may be subject to additional verification. International wires can be cancelled within 30 minutes of submission for a full refund, unless the receiving institution has already received the funds.

How much does a Navy Federal wire transfer cost?

Before sending a wire transfer, it's important to understand the fees involved. Navy Federal Credit Union charges different fees depending on whether you're sending or receiving a wire and whether the transfer is domestic or international. While incoming wire transfers are free, outgoing transfers attract a flat fee.

Wire transfer type Navy Federal fee Traditional bank fees Grey fees
Incoming Domestic $0 $10–$15 0.8% via ACH/FedNow (Min $2, Max $10)
Outgoing Domestic $20 $25–$35 $20 flat via Fedwire
Incoming International $0 $15–$25 0.8% via local networks (Max $10)
Outgoing International $25 $35–$50+ Depends on the destination and currency. See Grey's fees.

Overall, Navy Federal's pricing is competitive compared with many traditional banks, particularly because it does not charge for incoming domestic or international wire transfers. However, international payments can still become expensive once exchange rate mark-ups and intermediary bank charges are added.

Navy Federal wire transfer limits

Navy Federal's wire transfer page does not state a daily or per-transfer dollar limit. It does say that third-party wire requests over $5,000 must be submitted in writing, through a secure message or at a branch. For the limit that applies to your account, call Navy Federal on 1-888-842-6328 or ask through secure message.

If you need to move a large amount, you can speak to a Navy Federal representative about how to submit it, or visit a branch for assistance. Another alternative is to transfer your funds to an external bank account via ACH and initiate the larger wire transfer from that financial institution if it better suits your transfer needs.

Grey as an alternative for international transfers

While Navy Federal Credit Union offers a reliable way to send money abroad, international wire transfers can become expensive once wire fees, exchange rate markups, and intermediary bank charges are factored in. Wires also need a signed form and, for some requests, a written submission or branch visit, which adds time. If you send money internationally on a regular basis, a digital money transfer platform can offer a faster, fully digital process. Compare the total cost, including the exchange rate margin, before you choose.

Navy Federal Credit Union Grey Finance
Transfer Process Wire request form submitted by secure message, at a branch, by phone or by mail 100% digital via web or mobile app
Outbound International Wire Fee $25 flat fee per transfer Depends on the destination and currency. See Grey's fees.
Exchange Rate Markup Not published on Navy Federal's wire page Rate includes a margin over the mid-market rate
Conversion costs Often built into the exchange rate Conversion fee depends on the currency pair

For anyone who frequently sends money overseas, a digital platform such as Grey can be a useful alternative to traditional bank wires, with a fully digital process and fees shown before you send. Check the exchange rate margin and fees for your currency pair before you decide.

Frequently asked questions

How long does a Navy Federal wire transfer take?

Navy Federal lists an expected wait of 1 to 2 business days for domestic wires and 5 to 7 business days for international wires. The actual time depends on the destination country, intermediary banks, time zones, and whether all recipient banking details were provided correctly.

Can I cancel a Navy Federal wire transfer?

International wires can be cancelled within 30 minutes of submission for a full refund, unless the receiving institution has already received the funds, according to Navy Federal. For any other wire, contact the credit union immediately if you notice an error or wish to stop the transfer. Once a wire has been completed, it is generally difficult or impossible to reverse.

What happens if I enter the wrong routing number?

Entering an incorrect routing number can delay your transfer, cause it to be rejected, or send the funds to the wrong financial institution. Always verify the recipient's banking details before submitting a wire transfer. Contact Navy Federal immediately if you realise you've entered incorrect information.

Does Navy Federal charge for incoming wire transfers?

No. Navy Federal Credit Union does not charge a fee to receive domestic or international wire transfers. However, if you're receiving an international wire, intermediary or correspondent banks involved in processing the payment may deduct their own fees before the funds reach your account.

Can I send a wire transfer from the Navy Federal app?

Not directly. According to Navy Federal's wire transfers page, you can send a secure message through mobile or online banking with your completed wire transfer form, and Navy Federal will contact you to process the wire. You can also submit the form at a branch, by phone or by mail.

Is there a minimum amount for a Navy Federal wire transfer?

Navy Federal does not publish a minimum amount for sending a wire transfer. You can generally send any amount that meets your needs, provided you satisfy the credit union's verification and account eligibility requirements.

Whether you're sending money within the US or abroad, understanding Navy Federal's wire transfer routing number, fees, limits, and processing times can help you avoid costly mistakes and delays. For international transfers, if you want a fully digital experience, Grey is an alternative. Open a Grey account today or download the Grey app to compare the cost of sending money internationally before you decide.

Arrow (up)

Back to top