<script type="application/ld+json">[{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/grey-vs-local-banks-the-best-currency-exchange-method-in-kenya#article","headline":"Grey vs. local banks: The best currency exchange method in Kenya","description":"ooking for the best currency exchange method in Kenya? See how Grey compares to local banks.","inLanguage":"en","url":"https://grey.co/blog/grey-vs-local-banks-the-best-currency-exchange-method-in-kenya","mainEntityOfPage":"https://grey.co/blog/grey-vs-local-banks-the-best-currency-exchange-method-in-kenya","datePublished":"2025-02-28T15:15:51.142Z","dateModified":"2026-06-15T17:07:49.574Z","author":{"@type":"Person","name":"Adeolu Titus Adekunle"},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co"},"image":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/67c1d1227f306511ad97438d_Grey%20vs.%20local%20banks_%20The%20best%20currency%20exchange%20method%20in%20Kenya.webp"},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/grey-vs-local-banks-the-best-currency-exchange-method-in-kenya#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"Grey vs. local banks: The best currency exchange method in Kenya","item":"https://grey.co/blog/grey-vs-local-banks-the-best-currency-exchange-method-in-kenya"}]}]</script>

Grey vs. local banks: The best currency exchange method in Kenya

Adeolu Titus Adekunle

TABLE OF CONTENT

SHARE THIS POST

Kenya's thriving economy, rich cultural diversity, and robust digital infrastructure make it an attractive destination for expatriates, freelancers, and businesses. However, navigating financial management can be challenging. Traditional banks often present hurdles such as high transaction fees, poor exchange rates, and sluggish processing times, causing many to seek better alternatives.

Fortunately, innovative digital solutions like Grey offer a more efficient currency exchange method in Kenya.

This article evaluates Grey's strengths and weaknesses compared with local banks to help you choose the best currency exchange method in Kenya.

Read also: 13 essential tools and resources for digital nomads in Kenya

Grey vs local banks: The best currency exchange method in Kenya

To determine the most effective currency exchange method in Kenya, we will assess the following criteria:

  • Exchange rate and pricing transparency
  • Currency conversion speed
  • Accessibility and user experience
  • Multi-currency support

Favourable exchange rates and transparent pricing

Securing reasonable exchange rates is crucial to maximising your earnings. Traditional banks in Kenya often add hidden markups to exchange rates, leading to higher costs. Transparent and fair exchange rates can significantly enhance financial management.

Unlike traditional banks, Grey offers competitive real-time exchange rates that closely mirror market rates. With Grey's transparent pricing model, users can monitor exchange rates and convert funds when advantageous, avoiding hidden fees.

Fast and hassle-free currency exchange

Traditional banks can be slow with currency exchange processes, often bogged down by paperwork and manual procedures. These delays can disrupt financial plans and create stress, particularly in urgent situations.

In contrast, Grey provides swift transaction processing, often within minutes. The entirely digital process eliminates paperwork delays, allowing expatriates and freelancers to manage their finances efficiently.

Read also: How freelancers in Kenya can receive payments from international clients

Accessible and user-friendly platform

A simple, user-friendly experience can transform how you manage currency exchanges. Many banks make this process difficult with cumbersome requirements and mandatory in-person visits. A more accessible and intuitive platform can significantly improve the experience.

Grey offers unparalleled convenience by enabling currency conversion from anywhere, eliminating the need for physical bank visits. The platform's user interface ensures seamless management of multiple currencies.

Comprehensive multi-currency support

A provider that supports multiple currencies is essential for global transactions. Unfortunately, many traditional banks in Kenya lack this flexibility, complicating transactions for expatriates, freelancers, and travellers.

Grey, however, offers multi-currency bank accounts, including British pounds (GBP) and Euro (EUR) accounts. This feature enhances financial flexibility, allowing users to hold, transact, and convert these currencies to Kenyan Shilling (KES) effortlessly.

Simple steps to open a Grey account in Kenya

Creating a Grey account is quick and straightforward, typically completed within minutes.

Sign up on Gre to enjoy the best currency exchange method in Kenya

Read more: How to open US and UK bank accounts in Kenya

  1. Visit Grey.co or download the mobile app and sign up with your email address.
  2. Provide your details and create a secure password.
  3. Verify your identity by uploading a valid government-issued ID (e.g., passport) and proof of address (e.g., utility bill or bank statement).
  4. Grey typically reviews your documents within minutes, with most approvals completed within 24 hours.

Read also: How to get an instant USD debit card in Kenya

Why Grey is the top currency exchange method in Kenya

Grey outperforms traditional banks in Kenya as the preferred currency exchange method. It provides competitive exchange rates, transparent and fair pricing, and faster transactions. As a fully digital solution, Grey offers expatriates, freelancers, and businesses the most reliable and convenient method for managing currency exchanges.

Enjoy seamless currency exchange by creating your Grey account today or downloading the app to experience the benefits firsthand.

‍

Last updated:

September 26, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

Chase business account: Fees, features and how to open

•

•

2 min read

Choosing a business bank account usually begins with the question of how much it will cost to keep the account running? Chase is a popular option for US businesses, but its business checking accounts come with different fees, transaction limits and waiver conditions, so the cheapest-looking option is not always the best fit.

Chase currently offers three main business checking accounts: Business Complete Banking, Performance Business Checking and Platinum Business Checking. They are designed for businesses at different stages, from a small operation handling regular deposits and payments to a larger business with higher transaction volumes.

The important part is knowing what you are getting for the monthly fee. Depending on the account, Chase may waive the fee when you meet certain balance, deposit or activity requirements. Understanding those conditions before opening an account can help you avoid paying for features your business does not need.

Which Chase business checking account fits your business?

Chase currently has three main business checking tiers, aimed at different stages of business growth.

Business complete checking

This is best if you’re starting or running a small business. The $15 monthly fee can be waived in several ways, including maintaining a $2,000 minimum balance. You also get tools such as QuickAccept for taking card payments.

Performance business checking

This is a better fit once your business has more money moving through the account. It has a $40 monthly fee, waived with qualifying average balances of $35,000. You also get up to 250 monthly banker-assisted transactions and incoming wires at no additional charge.

Platinum business checking

It's built for established businesses with heavier transaction and cash-management needs. The $95 monthly fee can be waived with a $100,000 average beginning-day balance, or $50,000 with certain linked Chase accounts. It includes up to 500 banker-assisted transactions and $25,000 in branch cash deposits without additional charges.

How do Chase business checking accounts compare?

The right Chase account depends on how much money your business keeps in the bank and how often you make deposits, payments and other transactions.

Account Monthly fee How to waive it Transaction allowance Free cash deposits
Chase business
complete checking
$15 Keep $2,000 minimum daily balance or meet other qualifying conditions Unlimited electronic; 20 non-electronic transactions Up to $5,000 per cycle
Chase performance
business checking
$30 Maintain $35,000 combined average daily balance Unlimited electronic; 250 non-electronic transactions Up to $20,000 per cycle
Chase platinum
business checking
$95 Maintain $100,000 combined average daily balance Unlimited electronic; 500 non-electronic transactions Up to $25,000 per cycle

‍

In simple terms: Business Complete suits smaller businesses with lighter activity. Performance makes more sense when you have larger balances and more transactions. Platinum is aimed at established businesses moving substantial amounts of money.

Chase business banking features and benefits

Online and mobile banking

Chase gives you several ways to manage the account without constantly visiting a branch.

  • Chase Business Online lets you view transactions, download account activity and set access controls for employees.
  • The Chase Mobile app includes Chase QuickDeposit, so eligible business owners can deposit checks by taking a photo.
  • Built-in invoicing tools allow you to create, customise and send invoices digitally, including by text.

Business cards and employee spending

Chase also gives you more control when other people need to spend or deposit money on behalf of the business.

  • Business debit cards include chip security and transaction alerts.
  • Employee deposit cards can be restricted to deposits at Chase ATMs and branches.
  • Additional employee debit cards can be issued with individual spending limits.

Payments and integrations

Chase can connect your banking with other parts of your business.

  • Chase QuickAccept lets you take card payments through your phone or a compatible card reader.
  • E-commerce businesses can connect to supported payment platforms, including Authorize.net.
  • Chase also provides payroll and other payment services to help manage business operations.

Also read: Bank of America business account: Fees, features and how to open

How to open a Chase business account

Opening a Chase business account is mostly about having the right information ready. The exact process depends on your business structure, and not every business type can apply online.

  1. Check your eligibility: Choose the business account that suits you. Business Complete Checking can be opened online or in a branch, while some other Chase business accounts require a branch visit.
  2. Prepare your documents: You will generally need two forms of ID, including one government-issued ID, plus your SSN, ITIN or EIN. Chase may also request business registration documents, such as formation papers or a DBA certificate.
  3. Provide business details: Be ready to explain what your business does, where it operates, expected sales, number of employees and the types and volume of transactions you expect.
  4. Apply online or visit a branch: If your business qualifies for online opening, complete the application through Chase. Otherwise, schedule a branch appointment and bring the required documents and people who need to be present.

Also read: Can non-residents open a US bank account online in 2026?

What are the best alternatives to Chase business banking?

Digital business banking providers and credit unions can offer a different experience from a traditional bank like Chase. The best choice depends on whether you value online banking, international payments, low fees or access to local branches.

Mercury business banking

Mercury is a digital business banking platform built mainly for online businesses and startups.

  • Best suited for: Tech startups, e-commerce companies and venture-backed businesses
  • Main advantage: $0 monthly fees, no transaction limits and strong software integrations
  • Best fit if: You want to manage your business entirely online and connect banking with accounting or financial tools.

Wise business

Wise Business is designed for companies that regularly send or receive money internationally.

  • Best suited for: International freelancers, agencies and import/export businesses
  • Main advantage: Mid-market exchange rates and local account details in multiple currencies
  • Best fit if: You regularly receive foreign currencies or pay contractors overseas.

Novo business banking

Novo is a digital business banking option for small businesses and independent workers.

  • Best suited for: Solo entrepreneurs, contractors and small service businesses
  • Main advantage: Free invoicing and integrations with popular business apps
  • Best fit if: You want simple online banking without relying on physical branches.

Local credit unions

Credit unions are member-owned financial institutions that can provide more personalised local banking.

  • Best suited for: Cash-heavy retailers, local shops and family businesses
  • Main advantage: Personalised service and potentially lower cash-deposit costs
  • Best fit if: You handle significant physical cash or expect to need local business lending.

Grey Business Banking

Grey Business is designed for businesses that work across borders, particularly SMEs, agencies, startups and digital teams serving international clients.

  • Best suited for: Businesses in emerging markets receiving international payments and managing overseas clients or teams.
  • Key advantage over Chase: No monthly maintenance fee, with access to virtual USD business accounts without requiring a physical US operating address.
  • Best fit if: You need a simpler way to receive and manage international business payments without setting up traditional banking infrastructure in another country.

A simpler way to manage cross-border business payments

Chase can be a strong choice for running a US-based business, but international money movement can require a different setup. If you receive payments from clients abroad, pay overseas contractors or regularly move money between countries, a traditional US business account may not cover everything you need.

Grey is a multi-currency financial platform that can complement your business banking setup. Instead of converting every international payment immediately, you can use supported currency accounts to receive and manage money, then convert currencies when needed through the Grey app.

For example, a US business receiving money from an international client could receive the supported currency through Grey, convert it and then use the funds for other payments. Grey also lets eligible users send money across supported countries, which can be useful when paying suppliers, contractors or moving business funds internationally

Chase works well for businesses that mainly operate in the US, but international payments can introduce extra steps. If clients pay from overseas or contractors work in other countries, moving money between accounts and currencies can become more complicated than expected.

Grey can sit alongside your Chase account to make the international side easier. With supported currency accounts, you can receive and hold foreign currency before deciding when to convert it, rather than converting everything immediately.

Frequently asked questions about Chase business accounts

What does a Chase business account cost?

Chase business checking fees depend on the account you choose. Business Complete Checking currently has a $15 monthly fee, while Performance and Platinum accounts cost more but offer higher transaction and cash-deposit allowances. Some fees can be waived if you meet specific balance or activity requirements.

How can you avoid the Chase business checking fee?

The easiest way depends on your account. Business Complete Checking's $15 fee can be waived through qualifying activities, including maintaining the required balance. Performance requires a qualifying $35,000 average balance, while Platinum generally requires $100,000 or a lower balance with certain linked Chase accounts.

Can you open a Chase business account online?

Yes, eligible businesses can apply online, although some business types or applications may require a branch visit. Online applicants provide ownership, tax and business information and may need to upload identification or registration documents. Chase's online process also asks about how the business operates and expects to use the account.

What documents do you need to open one?

Expect to provide government-issued identification, your SSN, ITIN or EIN, and information about owners. Chase may also request formation documents, business licences, Articles of Organisation or a DBA certificate, depending on your business structure. Requirements vary, so prepare your registration documents before starting the application.

Does Chase support international business transfers?

Yes. Chase business accounts can send and receive international wires, although fees vary by account and transfer method. For example, Performance Business Checking currently charges $40 for outgoing international USD wires made through chase.com, while qualifying international FX transfers can cost less.

What are the alternatives to Chase business banking?

If your business operates internationally, you may want something built around cross-border payments rather than traditional US banking. Digital providers such as Mercury, Wise Business or Novo can suit online businesses, while a multi-currency platform such as Grey can complement your bank account for international money management.

Google Ads billing, invoices and payments for Nigerian businesses (2026)

•

•

2 min read

If you are already running Google Ads from Nigeria, you have solved the payment problem. Your virtual dollar card or domiciliary account card works, your campaigns are running, and money is leaving the account. Now the questions change: Where do I find my invoices? Why does the charge on my card not match my daily budget? How do I record USD ad spend in my naira-denominated books? How do I reconcile billing across four client accounts?

This guide is for Nigerian businesses, agencies, and freelancers who are past the setup phase and need to manage Google Ads billing at scale.

If you are still setting up your first Google Ads payment method, start with How to Pay for Google Ads in Nigeria and come back here once your campaigns are running.

How Google Ads billing works for Nigerian accounts

Every Google Ads account created from Nigeria is billed in USD. There is no naira billing option. This has three consequences for how you manage billing: all invoices and receipts are in dollars, all threshold charges hit your card in dollars, and any reconciliation with naira-denominated accounting requires a conversion step.

The three billing models

Google Ads offers three billing models. The one your account uses depends on when you set it up and your eligibility:

Billing Model How It Works Who Gets It Nigerian Context
Automatic payments Google charges your card after ads run, either at your billing threshold or at the end of the month. Default for most advertisers. This is what most Nigerian advertisers use. Your Grey or dom account card is charged automatically.
Manual payments You pre-fund your account. Costs are deducted from the balance as ads run. Campaigns pause when the balance hits zero. Available in some countries. Not always available for Nigerian accounts. If available to you, this gives more control over spending. Check your account settings to see if manual is an option.
Monthly invoicing Google issues a monthly invoice. You pay on credit terms (net 30 or net 60). Businesses spending $5,000+/month with a clean payment history. Requires a formal application through Google's sales team. Rare but available for Nigerian agencies at scale. Requires a minimum ~$5,000/month spend, clean billing history, and application through a Google sales representative. The benefit: net 30 or net 60 payment terms instead of prepayment.

‍

Most Nigerian advertisers are on automatic payments. The rest of this guide assumes that model unless stated otherwise.

Billing threshold: why your charges do not match your daily budget

This is the single most confusing aspect of Google Ads billing for Nigerian businesses, and the one most likely to cause a mismatch between what you expect to pay and what actually hits your card.

Google does not charge your card daily. It charges when your accumulated ad spend reaches a billing threshold. New accounts start at $50. As your payment history builds, Google raises it:

Threshold Typical Trigger
$50 Account creation (default)
$200 After several successful $50 charges
$350 Continued clean payment history
$500 Established accounts with no billing issues

‍

On top of threshold charges, Google also charges any remaining balance at the end of each calendar month, even if it has not reached the threshold. So you may see two types of charges: mid-month threshold charges and an end-of-month sweep.

A $20/day advertiser with a $200 threshold sees a $200 charge roughly every 10 days, not a $20 charge every day. If your accountant is looking for daily charges that match your daily budget, they will not find them. The charges match your threshold, not your daily spend.

Daily budget overshoot: why Google sometimes charges more than your daily budget

Google can spend up to 2x your daily budget on any single day to compensate for low-traffic days. If you set a $20/day budget, Google may spend $40 on a high-opportunity day and then spend less on subsequent days to balance it out. Over a calendar month, your total spend will not exceed your daily budget multiplied by 30.4 (the average number of days in a month). So a $20/day budget caps at $608 per month.

This is not a billing error. It is how Google optimises delivery. But it means your Billing Activity may show individual threshold charges that seem higher than expected. Check the monthly total, not the individual daily or threshold charges, when reconciling.

Google Ads billing documents: what exists and where to find each one

Google Ads generates several types of billing documents. Nigerian accounts on automatic payments have access to most of them, but not all.

Document What It Contains Where to Find It Nigerian Accounts
Invoice Official billing record for a period. Includes charges, taxes, and totals. Billing > Documents Available if your account generates invoices (not all automatic payment accounts do). Check Documents page.
Statement Summary of billing activity over a period. Not a tax document. Billing > Documents Usually available. Useful for accountant handoff.
Payment receipt Proof that a specific payment was processed. Billing > Summary > expand month > Payments section Available for every card charge. Click the payment link to view/print.
Billing activity Detailed transaction log: charges, payments, credits, refunds, adjustments. Billing > Billing Activity Available. Shows last 3 months by default. Exportable as CSV or PDF.
Tax document VAT or withholding tax records where applicable. Billing > Documents Available. Google issues 7.5% VAT invoices for all Nigerian accounts. Download from Tax and statutory documents tab.

‍

How to download invoices

  1. Sign in to Google Ads.
  2. Click the tools icon in the top navigation.
  3. Under Billing, select Documents.
  4. Use the filters to select the document type (invoice, statement, etc.) and date range.
  5. Click on an individual document to view it, or select multiple and click Download selected for bulk export.
  6. Documents download as PDF.

If you do not see an invoice for a specific month, check whether your account generates invoices at all. Accounts on automatic payments may only produce payment receipts and billing activity, not formal invoices. In that case, the Billing Activity export serves as your primary accounting record.

How to download payment receipts

  1. Go to Billing > Summary.
  2. Expand the card for the month you need.
  3. Find the Payments section.
  4. Click the link next to the specific payment to view the receipt.
  5. Print or save as PDF from your browser.

Each receipt corresponds to one threshold charge or one end-of-month sweep. If your account was charged three times in a month (two threshold charges plus one month-end sweep), you will have three receipts.

How to export billing activity for your accountant

  1. Go to Billing > Billing Activity.
  2. Set the date range (default is last 3 months, but you can go back further).
  3. Click the download icon.
  4. Choose CSV for spreadsheet import or PDF for direct filing.

The CSV export is what your accountant or finance team will use for reconciliation. It includes every line item: ad charges, payments, credits, refunds, adjustments, and taxes. Export monthly and store alongside your Grey transaction history for cross-referencing.

Reconciling Google Ads spend with your business accounting

This is where most Nigerian businesses struggle: the billing is in USD, and the books are in naira. The reconciliation has three layers: matching Google's charges to your card transactions, converting USD charges to naira for your records, and allocating costs to the correct expense category.

Layer 1: Match Google charges to your card transactions

Every threshold charge Google makes appears as a transaction in your Grey app (or your bank statement if using a domiciliary account). Export your Google Ads Billing Activity for the month and your Grey transaction history for the same period. Match each Google charge to a Grey transaction by date and amount.

They should match exactly in USD. If they do not, look for:

Authorization holds that is settled at a different amount (rare but possible).

Credits or adjustments applied by Google between the charge and your export date.

Charges from non-Google merchants if you use the same Grey card for other platforms (Facebook, TikTok).

Layer 2: Convert USD charges to naira for your books

Nigerian businesses filing accounts in naira need to convert USD ad spend to naira. The question is: which exchange rate do you use?

There are two defensible approaches:

Option A: Use the Grey conversion rate on the day you funded. When you converted naira to USD in the Grey app, you received a specific rate. That rate represents your actual cost basis. If you deposited N141,500 and received $100, your cost per dollar was N1,415. Record your Google Ads charges at N1,415 per dollar for that funding batch.

Option B: Use the CBN rate on the date of each Google charge. Some accountants prefer to use the official CBN rate on the transaction date. This may differ from the rate you actually paid through Grey, but it aligns with the method prescribed for foreign currency transactions under Nigerian tax rules.

Whichever method you choose, apply it consistently throughout the financial year. Switching between methods creates reconciliation problems. Consult your accountant for the approach that fits your specific tax situation.

Record the Grey 1% conversion fee as a separate line item under financial charges or bank fees, not as part of your advertising expense. The $4+$1 card creation fee (if applicable) is also a financial charge, not an ad cost.

Layer 3: Allocate to the correct expense category

Google Ads charges should be recorded under advertising and marketing expenses in your chart of accounts. Do not combine them with other card transactions. If you use the same Grey card for ad spend and non-ad purchases (subscriptions, SaaS tools, domain renewals), separate them in your bookkeeping.

For agencies managing client accounts: each client's ad spend should be tracked as a separate cost center. If you use per-account billing in Google Ads, each charge already maps to one client. If you use consolidated billing, cross-reference the Google Ads account-level spend reports with the consolidated charges to allocate correctly.

Setting a backup payment method

Google allows you to add a backup card alongside your primary card. If your primary Grey card fails (insufficient balance, card expired, Grey server downtime), Google charges the backup instead of pausing your campaigns.

To add a backup: go to Payment Methods, add a second card (a domiciliary account card, a second Grey card, or any other USD card), and select "Set as backup." Only debit or credit cards can serve as backup methods.

Managing billing across multiple Google Ads accounts

Agencies and businesses running multiple Google Ads accounts (whether for different brands, markets, or clients) need to decide how billing is structured. The decision affects invoicing, reconciliation, and how easily you can track spend per account.

Per-account billing (recommended for most agencies)

Each Google Ads account has its own payment method. You add your Grey card to each account individually. Charges appear separately per account in your Grey transaction history. When Google charges Client A's account $200 and Client B's account $150, those are two distinct transactions in your Grey app.

Its advantages? Clean reconciliation, isolated billing (one account's issues do not affect others), a clear audit trail per client. One Grey card can be added to multiple Google Ads accounts. The card number is the same across all of them.

Consolidated billing through a Manager account (MCC)

Google's Manager account (MCC) can pay for all linked client accounts from one payment method. One Grey card, one set of charges. Google issues a consolidated invoice or billing summary covering all accounts.

The downside: reconciliation is harder. A single $800 charge from Google might cover four client accounts. You need to cross-reference Google Ads account-level reports to allocate the $800 across clients. For agencies with 10+ clients, this becomes time-consuming.

For most Nigerian agencies, per-account billing is the cleaner setup. Use consolidated billing only if you have a specific operational reason (for example, a single corporate card policy that requires all charges on one payment method).

Billing documents in Manager accounts

If the Manager account is the paying account, invoices and billing documents are generated at the Manager level, not the individual client account level. Users who only have access to a client account will not see billing documents. Grant billing access at the Manager level to anyone who needs to view invoices or export billing data.

Tax considerations for Nigerian businesses running Google Ads

This section provides general guidance. Consult a qualified Nigerian tax adviser for your specific situation.

VAT on Google Ads in Nigeria

Google charges 7.5% VAT on all Google Ads costs for accounts with a Nigerian billing address. This has been in effect since April 1, 2022, under the Finance Act 2021, which requires non-resident digital service providers to collect and remit VAT in Nigeria. The 7.5% is added to your ad spend, meaning a $100 campaign actually costs $107.50 before your card is charged.

Google issues VAT invoices to Nigerian accounts, available for download under Billing > Documents > Tax and statutory documents. These invoices show the 7.5% VAT separately from your ad spend. Your accountant will need these for VAT reporting and any input tax credit claims.

Withholding tax

Nigerian businesses making payments to non-resident companies may have withholding tax obligations. Google Ads payments are made to a Google entity outside Nigeria (Google Ireland or Google Asia Pacific, depending on your account). Since Google already collects and remits 7.5% VAT, the withholding tax treatment may differ from other international payments. Consult your tax adviser on whether additional withholding applies.

This is an area where professional advice is essential. The amounts involved (particularly for agencies spending hundreds of thousands of naira monthly on ads) can create significant tax exposure if handled incorrectly.

Deductibility of Google Ads spend

Google Ads costs are generally deductible as a business expense for companies' tax purposes under Nigerian tax law, provided they are incurred wholly, exclusively, and necessarily for the purpose of the business. Keep your Google Ads billing exports, Grey transaction history, and reconciliation records as supporting documentation.

Month-end billing workflow for Nigerian businesses

A structured month-end process prevents billing surprises and keeps your accountant productive. Here is a practical workflow:

Step Action Where
1
Export Google Ads Billing Activity for the month as CSV Google Ads > Billing > Billing Activity > Download
2
Download any available invoices or statements Google Ads > Billing > Documents
3
Export Grey transaction history for the same period Grey app > Transaction History
4 Match each Google Ads charge to a Grey transaction by date and USD amount Spreadsheet
5 Convert USD charges to naira using your chosen rate method (Grey rate or CBN rate) Spreadsheet
6 Record Grey conversion fee (1%) as a separate financial charge Accounting software
7 Allocate ad spend to correct expense category (per client if agency) Accounting software
8 Store all exports centrally (Google CSV + Grey export + reconciliation) Cloud storage / accounting software

‍

Run this workflow in the first three business days of each month. If you manage multiple accounts, repeat steps 1 and 2 for each account (or export from the Manager account if using consolidated billing).

Managing ad spend with a Grey multi-currency account

If your business runs advertising across multiple platforms (Google, Facebook, TikTok) and manages spend in USD, a Grey multi-currency account can centralize your advertising finances.

How it fits the workflow described above:

Single USD balance for all ad platforms. Fund once, pay Google Ads, Facebook Ads, TikTok Ads, and any Visa-accepting platform from one account. One transaction history covers all your ad spend.

Conversion fee visibility. Grey's 1% conversion fee (capped at the naira equivalent of $6) is shown before you confirm every conversion. No hidden spreads. Your accountant can record the exact fee for each funding event.

Transaction history export. Grey's transaction history shows every charge, organized by date and merchant. Export it alongside your Google Ads Billing Activity for a clean month-end reconciliation.

Separate ad spend from operations. If your business uses Grey for both ad payments and regular expenses (receiving client payments, paying suppliers), the transaction history distinguishes them by merchant name. Google charges appear as GOOGLE*ADS or similar. This simplifies allocation in your accounting software.

For agencies managing multiple clients, Grey's transaction history shows individual charges per Google Ads account (if using per-account billing), making per-client cost allocation straightforward.

Troubleshooting billing issues

Invoice is missing for a specific month

Not all accounts on automatic payments generate formal invoices. Check whether your account produces invoices by going to Billing > Documents. If the Documents page is empty, your account only generates payment receipts and billing activity. Use the Billing Activity CSV export as your primary accounting record. The data is the same; the format is different.

Charge amount does not match any single campaign's spend

This is expected. Threshold charges cover your total account spend across all campaigns, not individual campaigns. If you run three campaigns and your total spend reaches $200 (your threshold), Google charges $200 in a single transaction. To see per-campaign costs, use Google Ads reporting (not billing). Campaign-level costs appear in the Campaigns tab, not in Billing Activity.

Charged at month end for a small amount

Google sweeps any remaining balance at the end of the month. If you spent $130 during the month and your threshold is $200, Google charges $130 on the first of the next month (or the last day of the current month). This is normal behaviour, not an error.

Double charge or unexpected second charge in the same week

If your campaigns are spending faster than usual (a new campaign launch, a budget increase), you may hit your threshold more than once in a short period. Check Billing Activity to confirm each charge corresponds to a threshold event. If you see a genuine duplicate (two charges for the exact same amount at the same time), contact Google Ads support.

Billing Activity shows a credit or adjustment you did not expect

Google applies credits for various reasons: promotional credits, overcharge corrections, invalid click refunds, and service credits. These reduce your next billing charge. They appear as negative amounts in Billing Activity. Record them as credits against advertising expense in your books, not as income.

How promotional credits interact with VAT

Google charges 7.5% VAT on total ad spend, including the portion covered by promotional credits. If you receive a N10,000 promotional credit and spend N20,000 total (N10,000 from your card + N10,000 from the credit), Google charges 7.5% VAT on the full N20,000 worth of ad spend. The VAT on the credit-covered portion appears as a line item in your billing, even though your card was only charged for half the spend.

Your accountant needs to know this because the VAT amount on the invoice will be higher than what seems proportional to your card charge for that period. The credit reduces your ad cost but not the VAT obligation. Record the promotional credit as a reduction in advertising expense, and the full VAT amount as reported on the invoice.

Cannot see billing documents in a client account

If you are using a Manager account (MCC) as the paying account, billing documents are generated at the Manager level. Users with access only to the client account will not see them. Grant billing permissions at the Manager level, or export billing data from the Manager account and share it.

Refund timeline when closing an account or overpaying

If you close your Google Ads account with a remaining balance, or if Google overcharges due to a billing error, Google refunds to the card on file. For active account overpayments, refunds typically process within 1 to 4 weeks. For account closure refunds, the timeline is longer: 4 to 12 weeks is normal. Google processes the refund after all final charges, adjustments, and credits are settled.

Plan for this delay in your cash flow. If you are closing a Google Ads account with a significant balance, do not count on those funds being available in your Grey account for at least 4 weeks. For agencies closing client accounts, communicate the timeline to the client upfront.

Frequently asked questions

Can I change my Google Ads billing currency from USD to naira?

No. Google Ads does not support naira billing for Nigerian accounts. Your billing currency is set when the account is created and cannot be changed afterwards.

Why is my Google Ads charge different from my daily budget?

Google charges at billing thresholds, not daily. A $20/day advertiser with a $200 threshold sees one $200 charge every 10 days, not daily $20 charges. Google also charges any remaining balance at the end of the month.

Can I get Google Ads invoices emailed to me?

Monthly invoicing customers may receive invoices by email. Advertisers on automatic payments need to download billing documents from the Billing section in Google Ads. Google does not email receipts or billing summaries automatically for most accounts.

How do I record Google Ads spend in my naira accounts?

Convert each USD charge to naira using either the Grey conversion rate on the day you funded, or the CBN rate on the date of each Google charge. Apply one method consistently throughout the year. Record the Grey 1% conversion fee separately as a financial charge.

Is Google Ads spend tax-deductible for Nigerian businesses?

Generally yes, as a business advertising expense, provided the spend is incurred for business purposes and properly documented. Keep your Google Ads billing exports, Grey transaction records, and reconciliation files. Consult your tax adviser for specifics.

Does Google charge VAT on Google Ads for Nigerian businesses?

Yes. Google charges 7.5% VAT on all Google Ads costs for Nigerian accounts, effective since April 2022. This appears on your billing as a separate line item. Google also issues VAT invoices available under Billing > Documents > Tax and statutory documents.

Can I download all my Google Ads invoices at once?

Yes. Go to Billing > Documents, select a date range, check all documents, and click Download selected. They download as PDFs.

What should I give my accountant each month?

Four files: the Google Ads Billing Activity export (CSV), any invoices or statements from the Documents page (PDF), the VAT invoice from Tax and statutory documents (PDF), and your Grey transaction history for the same period. The VAT invoice is critical for input tax credit claims.

Related reading

How to Pay for Google Ads in Nigeria (2026) covers setting up your first payment method, including virtual dollar cards and domiciliary accounts.

How to Pay for Facebook Ads in Nigeria (2026) covers both naira and USD payment paths for Meta Ads.

Best Virtual Dollar Cards in Nigeria (2026) compares virtual card options for international business payments.

Alternatives to Domiciliary Accounts in Nigeria compares Grey to traditional bank-issued dollar accounts for businesses.

How to obtain a Morocco business visa

•

•

2 min read

Morocco is an emerging destination for global business in Africa. The Global Trade Outlook 2024 ranks Morocco among the world’s top 20 emerging trade centres. Its location in the northwest corner of Africa makes it a natural bridge between Europe and sub-Saharan Africa. This facilitates intercontinental trade, investment, and cultural exchange.

Visiting Morocco for business might require a Morocco business visa unless you are from a country with a visa exemption agreement. Also, many investors and business owners often experience difficulties in managing their finances in Morocco. Traditional banks and local exchange services often experience delays or offer unfavourable exchange rates. However, with a digital payment platform like Grey, you can manage your finances seamlessly without cumbersome paperwork.

This article is a guide to obtaining a Morocco business visa. It will also show you how to manage your finances efficiently in Morocco.

Read also: How to open US, UK and Euro bank accounts in Morocco

What is a Morocco business visa?

A Morocco business visa allows foreign nationals to enter the country for professional activities such as attending meetings, signing contracts, or participating in trade events. This visa is usually issued for short stays and can be single or multiple-entry, depending on the applicant’s requirements.

How to obtain a Morocco business visa

The procedure for obtaining a Morocco business visa depends on your nationality, duration of stay, and country of residence. Follow this step-by-step guide to apply for a business visa.

1. Check visa requirements

Before applying, check whether you need a visa based on your nationality. Some countries have visa-free agreements with Morocco for short stays.

Read also: Morocco visa requirements for EU citizens

2. Prepare the required documents

The specific documents may vary depending on your nationality and the Moroccan consulate handling your application. However, generally, you will need the following.

  • Completed visa application form – Available from the Moroccan embassy/consulate or their official website.
  • Valid passport – Must be valid for at least six months beyond your intended stay and have at least one blank page.
  • Passport-sized photographs – Usually, two recent colour photos with a white background.
  • Business invitation letter – A letter from your Moroccan business partner or host company. The letter should specify the nature and purpose of your visit, duration of stay, and financial responsibility.
  • Cover letter from your company – Your employer should provide a letter stating your position, travel purpose, and the Moroccan business contact details.
  • Flight itinerary – Proof of confirmed round-trip flight bookings.
  • Accommodation details – Hotel reservation or an invitation letter from a Moroccan host.
  • Proof of financial means – Recent bank statements or financial documents to demonstrate you can cover expenses during your stay.
  • Travel insurance – Coverage for medical expenses and emergencies during your trip.
  • Visa fee – Fees vary depending on nationality and consulate.

Read also: Best way to transfer money from Morocco to Europe

3. Submit your application

You must submit your application at your country’s Moroccan embassy or consulate. Some locations may allow postal or online applications, so check their specific procedures.

4. Attend an interview (if required)

Some applicants may be required to attend an interview at the consulate to discuss the purpose of their trip.

5. Wait for processing

Processing times can range from a few days to several weeks, so apply well beforehand. Once approved, verify that the visa details are correct before travelling.

For the most accurate and up-to-date information, contact the Moroccan embassy or consulate in your country or visit the official website of Morocco’s Ministry of Foreign Affairs.

Managing your finances in Morocco

Having a reliable payment solution is essential when travelling to Morocco for business. Ensuring seamless international transactions can save you time and avoid unnecessary expenses.

Grey’s multi-currency account allows you to hold, transfer, and receive money in US dollars (USD), British pounds (GBP), and Euros (EUR). You can also convert these currencies to Moroccan Dirham (MAD) at competitive exchange rates.

With Grey’s virtual USD card, you can make international payments for services, subscriptions, and business-related expenses hassle-free.

Sign up on Grey today or download the app to enjoy effortless international transactions on your Morocco business trip.

‍

Transfer money from Algeria to Europe: Best ways

•

•

2 min read

Moving money from Algeria to Europe is not quite as simple as sending a domestic bank transfer. The Algerian dinar is subject to foreign-exchange controls, so the amount that can be moved abroad and the method used can depend on the purpose of the payment and the rules that apply.

A traditional option is a bank transfer through the SWIFT network. This can work for legitimate international payments, but it may involve paperwork, bank charges, exchange-rate costs and processing times. Licensed money-transfer services can provide another route where they are permitted and available for the type of transfer required.

For people who regularly earn money in euros, the situation can look different. Rather than converting and sending dinars every time a payment is needed, a multi-currency account can provide a way to receive and hold euros where the provider and local rules allow it. This guide explains the main options, what to expect from each and the important restrictions to understand before moving money from Algeria to Europe.

Also read: How to open international bank accounts in Algeria

Why sending money from Algeria can be complicated

Moving money from Algeria to another country can involve more than entering an IBAN and pressing send. Algeria has rules governing foreign exchange and transactions with other countries, so banks may need to check the purpose of a payment and whether it meets the applicable requirements. The Banque d’Algérie maintains specific regulations covering foreign exchange and international transactions.

The dinar also does not work like a freely convertible currency that can simply be exchanged and moved anywhere without restrictions. Access to foreign currency is managed through the banking and foreign-exchange system, which can make international transfers less straightforward.

There is another reality: cash still plays an important role in everyday financial life. That can make the move from physical dinars to a formal euro or dollar transfer feel less familiar. The rules also differ depending on why the money is being sent. For example, Algeria has specific provisions for foreign-currency allowances for residents travelling abroad.

That is why the easiest option depends on where the money is coming from, why it is being sent and which route is legally available.

Also read: Best way to transfer money from Egypt to Europe

What to expect when sending money by bank or SWIFT

A bank or SWIFT transfer can be a reliable way to move money from Algeria to Europe, but it is not always as quick as a domestic transfer. The bank may need to establish why the money is being sent and where it came from before approving the transaction.

The exact requirements depend on the bank and the reason for the transfer, but the paperwork may include:

  • Identification: A valid ID or other documents confirming the sender’s identity.
  • Source of funds: Evidence showing where the money came from, such as income or business records.
  • Purpose of payment: An invoice, contract or other document explaining why the payment is being made.
  • Tax documents: Additional tax or clearance documents may be requested for certain transactions.

How much does it cost?

Fees vary between banks and transfers. A SWIFT payment can include the bank’s transfer commission and SWIFT-related charges, with total costs sometimes reaching around €20 to €50.

How long does it take?

International bank transfers commonly take around 3 to 7 business days, depending on the banks involved, compliance checks and the destination country. Delays can occur if additional documents or information are required.

Best ways to send money from Algeria to Europe

Provider DZD support Transfer speed Cost Support Currency coverage
Wise Inbound only; converts foreign currency to DZD for local bank delivery Often seconds to minutes Upfront fee of around 0.4%–1% with mid-market rates In-app chat and email, with phone support for some customers 40+ holding currencies, including EUR, USD and GBP
Revolut Inbound only; converts foreign currencies to DZD for supported transfers Instant between users; 3–5 days for some international bank transfers Free plans available; weekend mark-ups and delivery fees may apply 24/7 in-app chat, depending on plan Holds 36 currencies; card spending available in 150+ countries
XE Inbound only; sends DZD directly to Algerian bank accounts Minutes to 3–4 business days No transfer fee, but exchange-rate mark-ups apply Help centre, online contact and phone support Transfers across 130+ countries and currencies
Western Union Inbound only; cash pickup and bank delivery available Cash pickup can be available within minutes; bank deposits may take 1–3 days Generally higher costs due to exchange-rate margins and variable fees Extensive agent network plus online and phone support Global network covering 200+ countries and territories

Holding and sending money with Grey

Grey can be useful when money needs to move between countries without converting everything straight away. Its multi-currency account lets eligible users hold supported currencies such as EUR and GBP in one place. This means foreign earnings can stay in the currency they were received in until there is a reason to convert them.

The account can also be used to receive foreign payments. Once the money arrives, it can remain in the balance or be converted when needed, with the exchange rate shown before the conversion.

Sending euros to Europe is also supported. Grey allows EUR payments to EEA countries through SEPA, so money can be sent directly to a recipient’s bank account using their IBAN. Transfers are generally completed within 1–3 business days, although timing can vary. Grey currently does not support EUR payments to Switzerland.

Frequently asked questions

Can I send DZD to Europe directly?

No. Algerian dinars cannot simply be sent abroad like a freely convertible currency. International transfers must follow Algeria’s foreign-exchange rules and go through an approved route. Where a transfer is permitted, the bank will generally convert the DZD into the required foreign currency before sending the payment to the European recipient.

What is the cheapest way to send money?

The cheapest option depends on why you are sending the money and which route you qualify for. Transfers made through official banking channels for recognised purposes, such as approved student or medical payments, may offer regulated exchange rates and relatively low transfer costs. Always check the bank’s total charges before sending.

How long does the transfer take?

An international transfer from Algeria can take several business days rather than arriving immediately. A typical bank or SWIFT transfer may take around 3 to 7 business days, although the timing depends on the purpose of the payment, the banks involved, foreign-exchange checks and any additional approval or documentation required.

Do I need a Euro account?

Not necessarily. If your Algerian bank approves the transfer, it can convert your dinars into euros and send the funds directly to the recipient’s euro-denominated bank account in Europe. You therefore do not normally need to hold a separate euro account simply to make an approved international payment.

What documents do I need?

The documents depend on the reason for the transfer. Your bank may ask for identification, proof of the source of funds and documents showing why the payment is being made. An invoice, university letter, medical document, contract or other supporting evidence may be required for certain international transfers.

Can I use Grey to send money to Europe?

Grey can be useful when you already hold supported foreign currency and need to send it to a European recipient. Its multi-currency features allow eligible users to hold and manage currencies such as EUR. However, Grey does not bypass Algeria’s foreign-exchange rules, so DZD transfers remain subject to local requirements.

How to obtain an Algeria business visa

•

•

2 min read

Algeria, Africa's tenth most populous country, is a growing global business destination. The country is strategically located at the crossroads of Africa and Europe. This makes it a favourable location for businesses seeking to tap into both markets. As an Arab nation with vast natural resources and government incentives for foreign investments, many eyes are turning to Algeria for international trade.

However, many visitors experience challenges making international transactions and getting favourable currency exchange services. Hence, before you travel, have a concrete plan to manage your finances to avoid losing money or getting stranded.

If you are considering a business trip to Algeria, you must know the visa requirements. This article will show you all you need to know about getting a business visa to Algeria. You will also learn how to manage your finances efficiently with Grey, your reliable travel partner.

What is an Algeria business visa?

A business visa allows foreign nationals to enter Algeria for professional purposes, such as attending meetings, signing contracts, or participating in trade events. It is typically issued for short stays and can be single or multiple-entry, depending on the applicant’s needs.

Read also: Grey vs. local banks: The smarter currency exchange option in Algeria

How to obtain an Algeria business visa

The procedure for obtaining an Algeria business visa depends on your stay duration, your passport, and the country from which you are travelling.

Follow this guide to obtain an Algeria business visa.

1. Determine your visa type

Algeria offers different types of business visas, including short-term and long-term ones. Choose the appropriate visa based on your needs.

2. Gather required documents

Although requirements vary by country, these are the general documents you might need:

  • Valid passport – Ensure your passport is valid for at least six months beyond your intended stay in Algeria and has two blank pages.
  • Completed visa application form – Complete the online application form on the Algerian embassy or consulate website.
  • Two recent passport photographs (as per embassy specifications).
  • Invitation letter – Obtain an invitation letter from your Algerian business partner or employer. The Algerian Chamber of Commerce should stamp the letter.
  • Mission letter – Where relevant, obtain a letter from your employer. The letter should state the purpose of your visit and their commitment to covering your expenses.
  • Flight itinerary and hotel booking or accommodation details.
  • Proof of financial means, such as bank statements.
  • Visa fee payment receipt.

Read also: How freelancers in Algeria can receive payments from US, UK & EU clients.

3. Apply Online

  • Go to the website of the Algerian embassy or consulate in your country.
  • Complete the form. Fill out the online visa application form accurately.
  • Print two copies of the completed form. Sign them in the designated areas.
  • Affix the passport photographs to the forms.

4. Submit your application

  • Visit the Algerian embassy or consulate in your home country. Some embassies require appointments. So, check in advance.
  • Submit your documents and pay the visa fee (fees vary by country).

5. Attend an interview (if required)

Some embassies may request an interview to verify the purpose of your visit.

6. Wait for processing

Processing times vary but usually take 5 to 15 business days. Check with the embassy/consulate for estimated timelines. It’s advisable to apply at least a month in advance.

7. Collect your visa

Arrange to collect your passport with the visa once it’s processed. Once approved, collect your visa from the embassy. You can opt for courier delivery if it is available.

Read also: The ultimate digital bank account for freelancers in Algeria

Managing your finances in Algeria

It is essential you have a reliable payment solution as you plan your business trip to Algeria. This ensures you can transact internationally without hassle.

Grey's multi-currency account allows you to hold, transfer and receive money in US dollars (USD), British pounds (GBP) and Euros (EUR). You can also convert from these currencies to Algerian Dinar (DZD) on Grey at competitive exchange rates.

With Grey's versatile virtual USD card, you can make international payments for products, subscriptions and services.

Sign up on Grey today or download the app to enjoy easy international transactions on your Algeria business trip.

‍

How to avoid scams when sending money to Algeria

•

•

2 min read

The first time many people send money to Algeria, the process is simple: choose a platform, enter bank details, and transfer the funds. But for others, one small mistake turns into a stressful experience involving fake agents, suspicious exchange offers, cloned websites, or payments that never arrive. In some cases, scammers exploit urgency, pretending to be relatives, payment processors, or “trusted” currency dealers offering better rates outside regulated channels.

As international transfers into Algeria continue to grow through freelancing, family support, and online business, so do scams targeting people unfamiliar with the payment process. Learning how to avoid scams when sending money to Algeria is no longer optional, especially when large amounts or foreign currency are involved.

This guide explains the most common money transfer scams in Algeria, warning signs to watch for, and safer ways to protect your funds before sending payments internationally.

Also read: The ultimate digital bank account for freelancers in Algeria

How do people get scammed when sending money to Algeria?

Many money transfer scams begin with good intentions. Someone wants to send $2,000 to family or a business partner in Algeria and starts looking for the “best rate” so the recipient gets more dinars. In the process, they ignore platform verification, skip regulated services, or trust informal agents promising better black-market exchange rates. That’s usually where the problem starts.

Some people hand cash to travellers “going down to Algeria” to avoid transfer fees entirely. Others use social media contacts, WhatsApp currency dealers, or unofficial exchange groups that claim they can beat banks and fintech platforms. The promise always sounds attractive: lower fees, faster delivery, and more value for the recipient.

But once the money leaves your hands, there is often no protection. Transfers get delayed, rates suddenly change, fake proof of payment is sent, or the person disappears completely. In other situations, the recipient receives far less than expected because hidden exchange manipulation quietly eats into the transfer.

Also read: The best way to receive euros in Algeria

How to calculate what the recipient should actually receive in Algeria

Many transfers look straightforward on the surface, but the real value is often reduced through a combination of fees and exchange rate manipulation that is not always obvious upfront.

For example, assume the market rate is 1 USD = 132 DZD, and you are sending $2,000. On paper, the recipient should receive around 264,000 DZD. However, this is rarely the final outcome once platforms apply their pricing structure.

One service might charge a clear 2% fee, which is easy to see. Another might advertise “zero fees” but instead offer a weaker exchange rate, such as 1 USD = 126 DZD. In that case, even without a visible fee, the recipient receives only 252,000 DZD, resulting in a hidden loss of 12,000 DZD relative to the market value. This is how many people underestimate real transfer costs.

This is why comparing platforms properly matters. You should always check the exchange rate, any direct transfer fees, withdrawal charges, and most importantly, the final amount in dinars that the recipient will receive before confirming the transaction.

Regulated services usually display this final payout clearly, while less transparent ones bury costs inside the rate. For physical services such as Western Union, it is also essential to keep receipts, invoices, and proof of payment, as these documents can serve as evidence if disputes, delays, or discrepancies arise later.

Also read: Receive consulting payments from US clients in Algeria

Safe ways to send money to Algeria without getting scammed

Sending money to Algeria requires careful platform verification, proper exchange rate comparisons, and secure payment records to reduce fraud, disputes, hidden charges, and transfer losses.

Grey

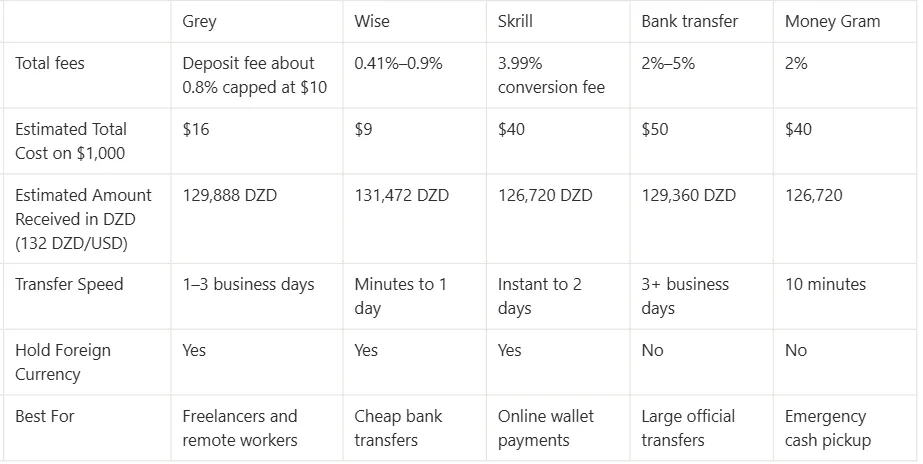
Grey is a useful platform for people sending money internationally while avoiding scams and excessive bank fees. It allows users to hold foreign currencies such as euros and pounds before converting them, giving better control over exchange rates. Deposit fees are low, around 0.8%, while conversion fees are about 1% capped at $6. Transfers usually take one to three business days, depending on the payment method. Grey is especially attractive for freelancers, remote workers, and people receiving international payments because it offers virtual accounts and transparent pricing. Since the platform is digital and regulated, users can track transactions securely and avoid risky black-market exchanges or unverified money agents commonly linked to scams in Algeria.

Wise

Wise is considered one of the safest and most transparent services for sending money internationally. It uses the mid-market exchange rate and clearly shows all fees before a transfer is completed. Conversion fees are usually between 0.41% and 0.9%, making it one of the cheapest options for a $1,000 transfer. Transfers are often completed within minutes or one business day, and users can hold multiple currencies before converting. Wise is heavily regulated and trusted globally, helping users avoid scams associated with informal transfer networks. Real-time tracking, bank-level security, and detailed transaction records increase trust and transparency. Wise is best for users who want low fees, fair exchange rates, and direct bank transfers to Algeria without hidden charges or unreliable middlemen.

Skrill

Skrill is a digital wallet service commonly used for online payments, international transfers, and freelance transactions. It supports multiple currencies and allows users to send money quickly across borders. However, Skrill’s conversion fees are relatively high at around 3.99%, meaning a €500 transfer could lose about €20 in exchange costs. Withdrawal fees can also vary depending on the destination and payment method. Skrill remains secure because it uses account verification, encryption, and fraud monitoring systems. The platform works well for online businesses, gaming platforms, and marketplaces where Skrill is accepted. To avoid scams, users should only transfer money to verified recipients and avoid sharing account credentials. Skrill is best for platform compatibility and fast online transactions rather than low-cost international transfers.

Bank (SWIFT)

Traditional international bank transfers through the SWIFT network are commonly used for large payments and business transactions. Banks are highly regulated and generally secure, making them a reliable option for avoiding scams. However, SWIFT transfers can be expensive because banks often add hidden exchange-rate spreads of 2%–5% along with intermediary banking fees. Sending $1,000 may therefore cost between $20 and $50 or more, depending on the banks involved. Transfers are also slower, sometimes taking three or more business days to arrive. Unlike modern fintech services, banks usually do not allow users to control when currency conversion happens. SWIFT transfers are best suited for large infrequent payments where security and official banking channels are more important than speed or low fees.

Also read: Algeria’s emerging remote work culture: challenges and opportunities

MoneyGram

MoneyGram is a well-known international remittance service used for quick cash transfers worldwide, including Algeria. Transfers are often completed within minutes, making it a strong option for emergencies or recipients who do not have bank accounts. Fees are typically included in the exchange rate, with an approximate 2% spread for currency conversion. This means a $1,00 transfer could cost around $20 overall. MoneyGram is widely accessible because recipients can collect money in cash from local agents using identification and a reference number. The company uses fraud detection systems and secure transfer tracking, helping users avoid scams. However, cash transfers should only be sent to trusted recipients because completed pickups are difficult to reverse. MoneyGram is best for urgent transfers and situations where banking access is limited.

Comparing cost on $1,000

__wf_reserved_inherit

Choosing the best platform to send money to Algeria

The best money transfer platform depends on fees, exchange rates, delivery speed, security, and how much the recipient finally receives in Algeria.

Compare the final amount received

Many platforms advertise low fees but reduce value through weaker exchange rates. Always check the final dinar amount the recipient will receive, not just the transfer cost. A slightly higher fee can sometimes deliver significantly more money if the exchange rate is better and more transparent.

Prioritise regulated and verified platforms

Using licensed banks, fintechs, or recognised transfer services reduces the risk of fraud, fake exchange agents, or missing transfers. Verified platforms also provide receipts, tracking, customer support, and transaction records that protect both the sender and recipient if disputes or delays happen during the transfer process.

Consider delivery speed and urgency

Using licensed banks, fintechs, or recognised transfer services reduces the risk of fraud, fake agents, or missing transfers. Verified platforms also provide receipts, tracking, and support that protect both sender and recipient.

Grey operates under regulated compliance and verification frameworks aligned with standards like FINTRAC-style AML and KYC checks, helping ensure transfers are tracked, transparent, and protected from informal currency risks.

Check withdrawal and access options

Before sending money, confirm how the recipient will access it in Algeria. Some platforms support direct bank deposits, while others rely on cash pickup locations or digital wallets. Choosing a platform that matches the recipient’s preferred withdrawal method helps avoid delays, additional charges, or unnecessary complications later.

Frequently asked questions

What is the safest way to send money to Algeria?

The safest way is to use regulated banks or licensed fintech platforms that offer tracking, receipts, and verified identity checks. Avoid informal agents or social media dealers offering better rates. Platforms like Grey add extra protection through compliance checks, reducing fraud and ensuring transfers are traceable and secure.

How do I know if a money transfer platform is legitimate?

A legitimate platform clearly shows fees, exchange rates, and final payout before confirming a transfer. It should also require KYC verification and provide transaction receipts. If a service hides rates or avoids documentation, it is usually risky and may expose you to scams or unfair exchange manipulation.

Why do people lose money when sending funds to Algeria?

Most losses come from hidden exchange rate spreads, not visible fees. Some platforms offer low fees but poor conversion rates, reducing the final dinar amount. Informal channels may also involve fraud or fake transfers. Always compare the actual amount received in DZD, not just the advertised cost.

Can fintech platforms help reduce scam risks?

Yes. Fintech platforms reduce scam exposure by using regulated systems, identity checks, and transparent pricing. Grey allows users to track funds, hold currencies, and convert at clearer rates, reducing reliance on informal exchange networks where scams and disputes are more common.

What should I avoid when sending money to Algeria?

Avoid sending money through unverified agents, strangers on social media, or cash handovers without receipts. Also avoid platforms that do not show the final payout in dinars before confirmation. Lack of transparency is often the biggest warning sign that you may lose money or face transfer issues.

Sending money to Algeria with Grey

Sending money to Algeria safely depends on using regulated platforms, checking exchange rates carefully, and avoiding informal channels that increase scam risk or hidden losses. Grey helps users manage international transfers more efficiently by offering low conversion fees and the ability to hold multiple currencies before converting. This gives better control over timing and value. Sign up or download the app to manage international transfers more securely and efficiently.

Grey charges fees on deposits, conversions, and withdrawals. Deposits via ACH, SEPA, or FPS incur a 0.8% fee (minimum $2/€2/£2, maximum $10/€10/£10). Currency conversions are charged at 1%, capped at $6. Withdrawal fees vary by currency: ₦35 for NGN, 0.5% for EUR/GBP (minimum €2/£2, maximum €10/£10), and $2 for Egypt. Cross-border card transactions (non-USD purchases on a USD card) incur a 2% fee plus $0.50. Exchange rates are variable and include a margin over the mid-market rate. Always review fees and the rate before confirming a transaction. Visit grey.co/pricing for current rates.

Arrow (up)

Back to top