<script type="application/ld+json">[{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/getting-your-foreign-currency-account#article","headline":"Getting your foreign currency account","description":"Foreign currency accounts help you carry out international transactions with ease. Here's how to get your free account on Grey.","inLanguage":"en","url":"https://grey.co/blog/getting-your-foreign-currency-account","mainEntityOfPage":"https://grey.co/blog/getting-your-foreign-currency-account","datePublished":"2022-11-30T17:29:52.017Z","dateModified":"2022-11-30T17:29:52.017Z","author":{"@type":"Person","name":"Ngozi Enelamah"},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co"},"image":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a301cbf23233f1b03a69b4b_6a301cbe291eb1c90964c1fb_getting-your-foreign-currency-account__header-image.webp"},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/getting-your-foreign-currency-account#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"Getting your foreign currency account","item":"https://grey.co/blog/getting-your-foreign-currency-account"}]}]</script>

Getting your foreign currency account

Ngozi Enelamah

TABLE OF CONTENT

SHARE THIS POST

At Grey, we care about our users and want them to be able to seamlessly make global transactions from anywhere in the world. Which is why we introduced foreign accounts to make it easy for you to send and receive foreign payments directly with your bank account.

In this post, we’ll be walking you through creating a US, UK and EU bank account on Grey.

If you already have a Grey account, you will need to log in to your dashboard or the Grey App, and perform the following:

  1. On the side bar, click “Accounts”
  2. Click the currency tab for the currency you want to create an account for
  3. Click the “Get your [insert currency] bank account”
  4. Double-check your first and last names to ensure they’re correct before proceeding.

However, if you are new to Grey, the process is straightforward:

  1. Sign up for a Grey account: this should only take a couple of minutes. We have written a guide to help you successfully create an account.
  2. Complete your KYC: Know Your Customer (KYC) helps us verify your identity and protect your account.
  3. Request a bank account: To request a bank account, go to the side menu and click “Account.” Next, select the currency tab for the currency you want and click the “Get your [insert currency] bank account” button. Make sure your first and last names are correct before completing your request.

Please note that you will be required to upload a means of identification - this is to help process your account creation. Once your virtual account request is submitted, your account will be created instantly and you’ll be ready to make your first transaction!

Also read: What is Virtual Banking?

Advantages of opening a foreign account on Grey

Opening a virtual account on Grey comes with several benefits:

  • Simple and straightforward: We have ensured that the virtual account creation process is seamless. You don’t need to fill out endless forms to own a foreign account.
  • On-the-go access: You can set it up from any of your devices (including your smartphone). There is no need to visit a physical location.
  • 24-hour banking: Due to the digital nature of our accounts, you are not restricted by office hours to use certain services.
  • Cheaper transfers: On Grey, we cut out unnecessary fees that traditional banks and money transfer agents charge, thus making your transactions more affordable.

Put the troubles of international money transfers behind and experience limitless banking with Grey. Create your free account today to get started.

__wf_reserved_inherit

Last updated:

September 13, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

Online debit cards: How to get one instantly

•

•

2 min read

Waiting for a physical card to arrive feels so 1900s, especially when you need it urgently. Beyond the daily inconvenience of carrying a physical card, using one also puts you at risk of data theft. These are some reasons financial institutions now widely offer online debit cards.

An online debit card, also called a virtual debit card, is a card number you can use for online payments without a physical card. Many providers issue one instantly through an app once you set up your account. It draws from your own balance, so no borrowing is involved.

Whether you need a card for a one-off online purchase, want to avoid exposing your main card number to a new merchant, or simply want to start spending online without waiting days for a physical card to arrive in the post, an online debit card solves the problem immediately. This guide explains what these cards actually are, how to get one, and how to use one safely.

What is an online debit card?

An online debit card is a digital card with the same details as a physical card, including a card number, expiry date, and security code. So, it functions like a standard debit card but is digital rather than a physical piece of plastic.

Online debit cards usually charge directly from a linked account balance. So you only spend money you already have, unlike with virtual credit cards.

How does a virtual card differ from a physical card?

A physical debit card usually arrives by post, which might take days. Some banks let you pick up the card at a branch, which usually takes a few minutes, without queues. On the other hand, an online (virtual) debit card is usually generated instantly from the bank or payment platform’s app once your account and identity are verified. This means you can create an account, get a debit card, and start using it within minutes of signing up.

How does a virtual card differ from a prepaid card?

A virtual debit card is also different from a prepaid card. A prepaid card usually requires you to load money onto it before spending. The card balance is somewhat separate from your account balance. Meanwhile, a virtual debit card connects directly to your account and serves as a spending tool for that account.

Where do digital cards work?

You can use a virtual debit card on any online checkout that accepts card payments. The payment is processed just like a physical card number. Depending on the provider, your card may also support Apple Pay and Google Pay, which you can use for contactless payments at physical stores and on public transport.

How to get one instantly

Getting a virtual debit card typically takes minutes, not days, by following this general process.

Step 1: Choose a provider: Look for a bank or fintech that offers instant virtual cards. Check the supported currencies, fees, spending limits, and other account features.

Step 2: Sign up and verify your identity: Provide the required details and complete identity verification. The platform usually requests a valid government-issued ID (passport, driving licence, or national ID), proof of address, and sometimes a selfie for verification. You usually complete this process entirely within the provider's app.

Step 3: Fund your account: Once your account is created and verified, you can deposit money using a bank transfer or other funding options supported by the bank.

Step 4: Generate the card: Once your account is funded, go to the card section in the app and create your virtual card. This may cost money, which is why you need to fund your account beforehand. You should get your card number, expiry date, and security code almost immediately.

Step 5: Start using your card: Enter the card details into any online checkout. Use the card details to pay for online purchases, subscriptions, and other services that accept card payments. Some providers also let you add the virtual card directly to Apple Pay or Google Pay for auto-fill and contactless payments.

Some providers charge a one-time card creation fee, while others issue the first virtual card for free. Check the specific provider's fee structure before proceeding.

How to use an online debit card safely

Virtual cards can make online spending safer because you do not always have to share your main card details.

  • One-time or per-merchant card numbers: Some payment platforms let you generate a card number for each merchant or transaction. This limits your risk exposure if that merchant's platform ever gets compromised.
  • Spending limits: Setting a specific spending limit on your virtual card prevents unexpected large transactions. This also helps you manage subscriptions and trial periods if you forget to cancel.
  • Freezing the card: If you suspect your card details have been compromised, or you simply want to temporarily pause spending, many providers let you freeze the card instantly in the app. Only that card is frozen, so you can still continue using your account and other cards.
  • Creating multiple cards for different purposes. Rather than reusing the same virtual card number everywhere, creating separate cards for subscriptions, one-off purchases, and recurring bills makes it easier to track spending and limit the blast radius if any single card's details are exposed.

Online debit card vs prepaid and physical cards

‍

Read more about digital Visa gift cards and how they are different from virtual debit cards.

Using a virtual card for international payments

Beyond everyday online shopping, a virtual debit card is particularly useful if you spend, receive, or manage money in more than one currency.

The Grey virtual card is issued instantly within the Grey app and connects directly to your USD, GBP, or EUR balance. This means purchases in the same currency as your balance draw directly from that balance with no cross-border conversion fee. This is considerably better than a domestic virtual card when shopping internationally or paying for services in a foreign currency.

You can also create multiple cards on Grey for different needs, each with set limits. You can have a card for your Meta ads, one for your international trips, and another for your subscriptions and online shopping. This makes budgeting easy, and you can freeze any card at any time.

After a one-time $5 payment, you can access a Grey card instantly, which works anywhere Visa cards are accepted. Link your Grey card with Google Pay and Apple Pay for extra security and auto-fill on trusted websites. You can also use the card for contactless payments at physical stores, or tap at paypoints when using public transport in supported regions.

Beyond the card itself, holding multiple currencies in one Grey account means you can manage USD, GBP, and EUR balances side by side and convert between them at a disclosed rate whenever it suits you, rather than being forced to convert at the point of every purchase.

If you also need to receive payments from US clients or employers, you can send money from the US directly into your Grey USD account via ACH, with the full amount arriving without correspondent bank deductions.

Get an instant virtual card with Grey at $5 and start spending online in minutes.

Frequently asked questions about online debit cards

What is a virtual debit card?

A virtual debit card is a set of card details (number, expiry, security code) that functions like a physical debit card for online payments, but exists digitally rather than as a physical card. It draws from your own linked account balance, so there is no borrowing involved, and it is typically issued instantly within a banking or fintech app.

Can I get one instantly?

Yes, with most modern banking and fintech providers. Once your identity is verified and your account is set up, generating a virtual card typically takes seconds within the app, with card details available for immediate use at online checkout. This is significantly faster than waiting for a physical card to arrive by post, which can take several business days.

Is it safe to use online?

Yes, generally safer than repeatedly sharing your primary physical card details. Many virtual card providers allow you to set specific spending limits, freeze the card instantly if compromised, and, in some cases, generate per-merchant or one-time card numbers, all of which reduce your exposure compared to using the same physical card everywhere.

Can I use it abroad?

Depends on the specific card and provider. Some virtual debit cards work internationally for online purchases with no restrictions, while others may be limited to domestic use. If you plan to make international purchases regularly, check whether your provider supports foreign-currency balances (to avoid conversion fees) and whether the card works for in-store contactless payments abroad via digital wallets.

Do I need a bank account?

You need an account with the provider issuing the virtual card, which functions like a bank account for most practical purposes (holding balance, receiving deposits, and enabling the card). This doesn't necessarily need to be a traditional bank; many fintech platforms offer fully functional accounts with virtual card issuance without requiring a separate traditional bank relationship.

What is the difference from a prepaid card?

A prepaid card requires you to load funds onto the card before use and often exists as a standalone balance rather than a full account. A virtual debit card is typically tied to a full account, with standard features (transfers, deposits, and often a physical card option) available, and the virtual card is simply the digital spending instrument that draws from that account balance.
What is the currency of Turkey? Lira symbol and code

•

•

2 min read

Turkey's currency is the Turkish lira, written as TRY and represented by the symbol ₺. You will see it everywhere, from the price of a coffee in Istanbul to hotel bills along the Mediterranean coast. Knowing the symbol and code makes it easier to understand prices and compare exchange rates when planning a trip.

The lira is issued by the Central Bank of the Republic of Turkey and has been the country’s currency in its modern form since 2005, following a redenomination that removed six zeros from the previous lira. Today, it remains central to everyday spending across the country.

For visitors, however, the lira comes with another consideration: its value has fallen significantly against major currencies in recent years. That makes understanding TRY exchange rates, cash payments and card spending particularly useful before travelling to Turkey.

What you need to know about the Turkish currency

The Turkish Lira (TRY/₺) is highly volatile, with inflation at 31.75% and the currency trading at around 48.06 TRY per USD. For travellers, understanding how to access and spend money can help avoid unnecessary costs, particularly as exchange rates and fees can vary significantly between providers.

Visa and Mastercard are widely useful for hotels, restaurants and larger purchases, but carrying some physical Turkish lira remains important. Cash is often needed for street food, traditional markets, public transport and small tips, where card payments may not always be accepted.

When exchanging money, avoid airport exchange booths and standalone tourist ATMs, which can charge unfavourable rates and high transaction fees. If you use a card, always choose to be charged in Turkish lira (TRY) rather than your home currency. This helps you avoid Dynamic Currency Conversion, which can apply an additional exchange-rate markup at the point of payment.

How to recognise Turkish lira prices when you’re in Turkey

When you are looking at prices in Turkey, the first thing to recognise is the ₺ symbol. It represents the Turkish lira, so a price such as ₺500 simply means 500 Turkish lira. You will see the symbol on restaurant menus, shop signs, hotel websites and receipts, making it one of the easiest ways to spot prices in the local currency.

Its international ISO code TRY, is what you are more likely to see when checking exchange rates or using a banking app. For example, a currency converter might show GBP/TRY or USD/TRY rather than using the ₺ symbol. The lira is issued by the Central Bank of the Republic of Turkey.

Prices in Turkey are generally written with the ₺ symbol before the amount, although you may also see “TL” used in shops, menus and online listings. Once you know the symbol and code, comparing Turkish prices with your home currency becomes much easier.

What do Turkish lira banknotes and coins look like?

Turkey’s banknotes are easy to tell apart once you get used to their colours and the people featured on the reverse. The ₺200 note is the highest denomination currently in circulation, while smaller notes cover everyday spending.

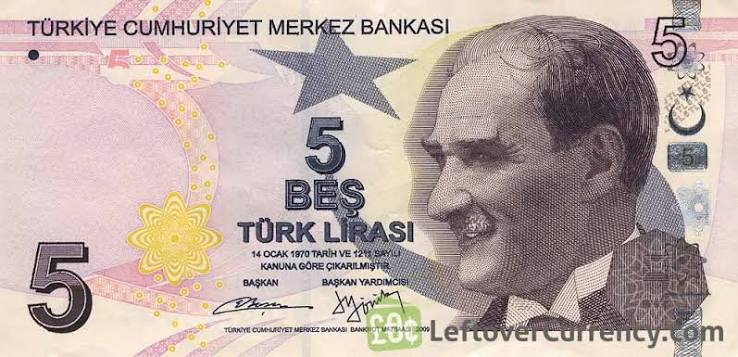
₺5: A purple-toned note featuring scientist Aydın Sayılı, with his contribution to the history of science represented on the reverse.

__wf_reserved_inherit

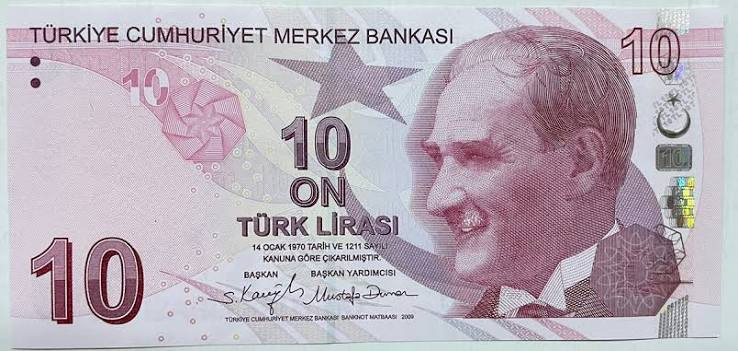
‍₺10: The pink and red ₺10 note honours mathematician Cahit Arf, one of Turkey’s most influential mathematicians.

__wf_reserved_inherit

₺20: Green in colour, the ₺20 note features architect Mimar Kemaleddin, known for his work in Ottoman and early Republican-era architecture.

__wf_reserved_inherit

₺50: The orange ₺50 note features Fatma Aliye Topuz, a pioneering Turkish novelist and writer.

__wf_reserved_inherit

₺100: Blue and easy to spot, the ₺100 note honours musician and composer Buhurizade Mustafa Itri.

__wf_reserved_inherit

₺200: The violet ₺200 note features the poet and mystic Yunus Emre and is Turkey’s highest-value banknote.

__wf_reserved_inherit

Coins are used alongside these notes for smaller purchases, particularly transport, snacks and everyday items.

Also read: Mastercard exchange rate: How it works and what you actually pay

Turkish lira to US dollar exchange rate: where the lira stands today

The Turkish lira has lost considerable value against the US dollar over the past several years. A rate of 1 USD = 47.89 TRY means one US dollar currently buys 47.89 Turkish lira. For travellers, that figure gives a useful starting point when working out what meals, hotels, transport, and shopping will cost in Turkey.

The lira’s decline has been closely linked to Turkey’s prolonged inflation and wider economic pressures. However, it is worth noting that Turkey operates a floating exchange-rate system, meaning the lira’s value is determined by market supply and demand rather than being fixed at a particular level by the central bank.

Exchange rates can move throughout the day, so the figure you see may differ depending on when and where you convert your money. For the latest official reference rates, check the Central Bank of the Republic of Türkiye’s indicative exchange rates. For a live commercial rate, you can also check your bank or exchange provider before making a conversion.

Also read: How to avoid foreign transaction fees when travelling abroad

How to spend Lira as a traveller in Turkey

Turkey is easy to navigate financially, but the way people pay changes depending on where you are. In Istanbul’s modern restaurants, hotels and shopping centres, cards are widely accepted. Step into a local market, smaller café or neighbourhood shop, however, and cash can still be the easiest option. Keeping some Turkish lira available makes those everyday purchases much simpler.

Exchange offices are common in tourist areas, although rates can vary considerably. Airport counters are convenient but often less competitive, so compare rates before exchanging larger amounts. ATMs are another option, but check the charges and choose TRY when asked whether you want to pay in lira or your home currency.

Grey gives travellers a simple way to manage money across currencies while abroad. With a Grey multi-currency account, you can hold supported currencies, manage your money from one place and send TRY right from your account. The Grey card can then be used for everyday spending wherever Visa is accepted, giving you another option alongside cash.

Frequently asked questions

What is the symbol for the Turkish lira?

The Turkish lira uses the ₺ symbol, which you will see before prices in shops, restaurants and online listings. Its international currency code is TRY, while TL is also commonly used in Turkey. So, a price shown as ₺500 simply means 500 Turkish lira.

How much is 1 dollar in lira?

The USD to TRY exchange rate changes regularly, so the amount you receive can vary throughout the day. A reference rate of $1 = ₺47.89 means one US dollar buys 47.89 Turkish lira. Your bank, card provider or exchange service may offer a slightly different rate.

Is USD accepted in Turkey?

US dollars are accepted in some tourist-focused businesses, particularly certain hotels, tour operators and shops in popular destinations. However, the Turkish lira remains the standard currency for everyday spending. Paying directly in lira usually makes prices easier to compare and helps you avoid unfavourable conversion rates charged by individual businesses.

Should I exchange money before I travel?

There is no need to exchange all your money before travelling to Turkey. Arriving with a small amount of cash can be useful for transport or immediate expenses, while more lira can be obtained locally. Compare exchange rates before converting money, and avoid exchanging large amounts at airport counters.

Can I use my card in Turkey?

Cards are widely accepted across Turkey, particularly in hotels, restaurants, shopping centres, supermarkets and other established businesses. Cash still matters for smaller shops, markets, street food, taxis and places without card terminals. Keeping some Turkish lira alongside your card gives you more flexibility when travelling around the country.

Why is the lira so weak?

The Turkish lira has weakened considerably because of prolonged inflation, economic pressures and monetary-policy decisions that affected confidence in the currency. Although Turkey has moved towards tighter monetary policy, inflation remains high. The result is a currency that buys less internationally, while everyday Turkish prices continue changing as costs rise.

Prepaid Visa cards: How they work and where to get one

•

•

2 min read

A prepaid Visa card can be a practical way to manage spending without relying on credit. You load a specific amount onto the card and use that balance for purchases wherever Visa is accepted, subject to the card’s terms and local restrictions. Because you are spending funds already loaded onto the card, there is generally no overdraft or credit limit involved.

This makes prepaid cards useful for different needs around the world. Parents can use them to give children a set spending allowance, businesses can provide them for employee expenses, and travellers can use them to manage a dedicated travel budget. They can also be useful for gifting and online purchases.

However, prepaid cards differ by provider and country. Before choosing one, check the fees, reload options, supported currencies, expiry terms, withdrawal rules and usage restrictions to make sure the card fits your needs.

Also read: How to spend globally with the new Grey Virtual Card

What is a prepaid Visa card and how does it work?

A prepaid Visa card is a card you load with money before you spend it. Unlike a traditional debit card, it's not directly connected to your bank account, and unlike a credit card, it does not give you a line of credit. Once funded, you can spend from the available balance until the money runs out.

Depending on the card and provider, you may be able to add money through bank transfers, direct deposit or cash deposits. The amount you load becomes your spending limit, which can make prepaid cards useful when you want to keep a particular budget separate from your main finances.

The card runs on the Visa payment network, so it can be used at participating merchants and, where supported, ATMs in different countries. That makes a prepaid Visa useful for everyday purchases, online payments, travel and gifting. However, acceptance, withdrawal access and fees vary between cards, so checking the terms before loading money is important.

How prepaid Visa cards work from activation to everyday spending

The process starts when you buy a prepaid Visa card. At checkout, you pay for the card and load it with, say, $300. Depending on the issuer, activation may happen at the register, through the provider’s website or in its app. Once activated, the balance is available for spending.

That $300 becomes your starting balance. Spend $40 on dinner and about $260 remains. Need to add more later? If the card is reloadable, you can top it up using the methods offered by the issuer, such as cash at a participating retailer, bank transfer or direct deposit. Some cards, however, are designed for one-time use.

Where can you use it? Generally, wherever that prepaid Visa is accepted, including:

  • Online shops and subscription services
  • Supermarkets, restaurants and petrol stations
  • Hotels and participating travel businesses
  • ATMs that support prepaid Visa withdrawals

Because prepaid Visa cards operate on the Visa network, they can be useful both locally and abroad. However, international purchases, ATM withdrawals and certain merchants may have restrictions or additional fees. Checking the issuer’s terms before loading a substantial amount can help you avoid unexpected costs.

Also read: Visa eGift Cards and Digital Visa Cards Explained

Prepaid, gift or debit: which card fits your needs?

The easiest way to tell them apart is to ask one question: where does the money come from? A prepaid card uses money you load yourself. A debit card pulls money directly from your bank account, while a credit card lets you spend borrowed money and repay it later.

Prepaid cards are useful when you want a spending limit without exposing your main bank account. Some are reloadable, meaning you can keep adding money after the balance runs down. Others are single-load cards designed to be spent and then discarded.

Gift cards are slightly different. A single-load gift card might be bought with $50 and given to someone for shopping at a particular retailer or, in some cases, across the wider Visa network. Reloadable gift cards exist too, although their terms and availability vary.

So, which makes sense? Use a prepaid card for controlled, repeat spending; a gift card when you want to give someone a fixed amount; and a debit card when you want everyday access to your bank account.

Prepaid card fees and charges to check before choosing one

The price on the front of a prepaid card is not always the full cost. Check the fees attached to activating, loading, using and keeping the card before deciding which one suits you.

  • Activation: Some cards charge a one-off fee when you activate them.
  • Monthly maintenance: Certain cards deduct a regular service charge from your balance.
  • Reloading: Adding money, particularly with cash, may attract a reload fee.
  • ATM withdrawals: Taking out cash can trigger charges from the card issuer or ATM operator.
  • Inactivity: Some cards charge a fee when you leave the balance unused for a set period.

A card with a low activation fee may not necessarily be the cheapest overall. If you expect to reload often, withdraw cash or keep the card for several months, those recurring charges can matter more than the initial cost.

Where to get a prepaid card and the alternatives worth considering

Prepaid Visa cards are commonly sold through banks, supermarkets, convenience stores and other participating retailers, while some issuers let you apply online. The right choice depends on what you need the card for: a one-off gift, controlled spending or something you can reload and keep using. Always check the issuer’s fees, reload rules and expiry conditions before buying.

But what if the main reason you want a prepaid card is online shopping or spending abroad? A virtual debit card may make more sense. Instead of buying and loading a physical card, you can manage your money digitally and use the card for eligible online purchases and international payments.

Grey allows you to create multiple virtual cards and spend directly from your Grey account, without needing to fund each card separately. You can also freeze or unfreeze individual cards whenever needed, while setting spending limits to stay in control.

Frequently asked questions

What is a prepaid Visa card?

A prepaid Visa card is funded before you spend, rather than drawing money from a bank account or borrowing through credit. You load a chosen amount onto the card and use that balance for eligible purchases. Once the money is gone, you cannot spend more unless the card supports another reload.

Can you reload it?

Some prepaid Visa cards are reloadable, while others are designed for a single load. Reloadable cards may allow you to add money through cash at participating retailers, bank transfers or direct deposits. Always check the issuer’s terms because reload methods, limits and fees can vary between different prepaid cards and providers.

Do prepaid cards have fees?

They can. Depending on the issuer, you may encounter activation, monthly maintenance, reload, ATM withdrawal or inactivity fees. Some cards have fewer charges than others, so the cheapest-looking option is not always the best value. Check the full fee schedule before buying or loading money onto a prepaid Visa card.

Is a prepaid Visa card the same as a gift card?

Not exactly. A prepaid Visa can work similarly to a gift card because you spend money loaded onto it, but prepaid cards are generally designed for broader personal spending. Gift cards are often intended as presents and may be restricted to one retailer. Some Visa gift cards can also be single-load only.

Can I use it online and abroad?

Many prepaid Visa cards can be used for online purchases and international transactions wherever the particular card is accepted. However, overseas spending may involve foreign transaction fees, while some issuers restrict international purchases or ATM withdrawals. Check the card’s terms before travelling or relying on it for online payments abroad.

Where can I buy one?

Prepaid Visa cards are available from participating banks, supermarkets, convenience stores and other retailers, as well as directly from some issuers online. Availability depends on your country and the specific provider. Before buying, compare activation costs, reload options, usage restrictions, ATM access and other fees to find a suitable card.

What is the currency of Poland? Zloty symbol and code

•

•

2 min read

Unlike many other European countries that have the euro as the official currency, Poland has it's own currency: the Polish złoty.  Its international currency code is PLN but prices are commonly written with the zł symbol. If you are planning a trip, working with Polish clients or simply checking prices online, recognising these two forms makes Polish money much easier to navigate.

The złoty is issued by the National Bank of Poland and is divided into 100 grosz. You will see the currency everywhere, from supermarket price tags to restaurant menus, often written as an amount followed by “zł”. The name itself has an interesting history too: złoty means “golden” in Polish.

Poland is part of the European Union but has retained the złoty instead of adopting the euro. That means visitors arriving from eurozone countries still need to think about exchange rates when paying in Poland.

What is the currency of Poland?

The currency of Poland is the Polish złoty, usually written as zł and identified internationally by the code PLN. If a shop displays a price such as 50 zł, it means 50 Polish złoty. One złoty is divided into 100 grosz, so you may see prices expressed with both złoty and grosz when paying for everyday items.

The currency is issued by the National Bank of Poland, which is responsible for Poland’s monetary policy and the country’s banknotes and coins. The word “złoty” comes from the Polish word for “golden”, reflecting the historical connection between the currency’s name and gold.

So why does Poland use the złoty when it is part of the European Union? EU membership does not automatically mean adopting the euro. Poland has committed to adopting the euro eventually, but it has not yet met all the conditions required to join the eurozone. For now, the złoty remains Poland’s official currency, meaning travellers from other european countries still need to consider the PLN exchange rate when spending there.

Also read: How to send and receive euros in the UK

How to recognise the złoty code and symbol

The Polish złoty can appear in a few forms, which can be confusing when you first encounter Polish prices. The most familiar symbol is zł, while PLN is the three-letter ISO currency code used by banks, exchange services and financial platforms. So, if you see PLN 200 on a currency converter, that is simply 200 Polish złoty.

On menus, shop signs and price labels, you will more often see zł after the amount. A coffee priced at 15 zł means you will pay 15 złoty. Smaller amounts can include grosz, the currency’s subunit, with 1 złoty divided into 100 grosz. You might therefore see a price such as 12,50 zł, which means 12 złoty and 50 grosz.

For travellers, recognising the difference between zł and PLN is useful because you will encounter both depending on where you are paying or checking prices. A card terminal may process a transaction in PLN, while a supermarket shelf simply displays “29,99 zł”. They refer to the same currency; the difference is mainly how the price is presented. When comparing costs with your home currency, use the current PLN exchange rate rather than assuming the number on the price tag tells you what something costs in euros, pounds or dollars.

What Polish banknotes and coins look like

Polish banknotes are designed around the country’s royal history, with each denomination featuring a different Polish monarch. Their colours, sizes and portraits make them easier to tell apart once you have handled a few.

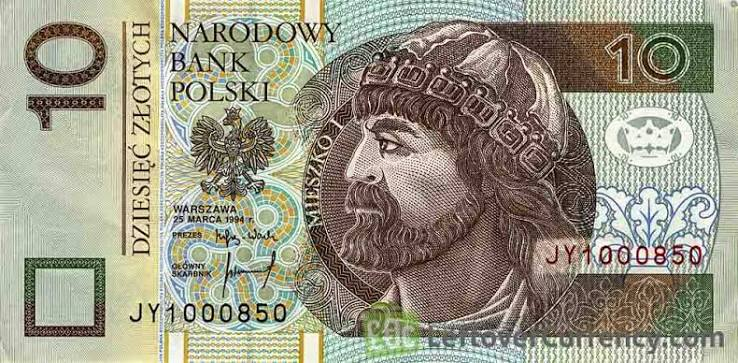
10 zł: Green and brown, featuring Mieszko I. The reverse shows a silver denarius and other references to Poland’s early history.

__wf_reserved_inherit

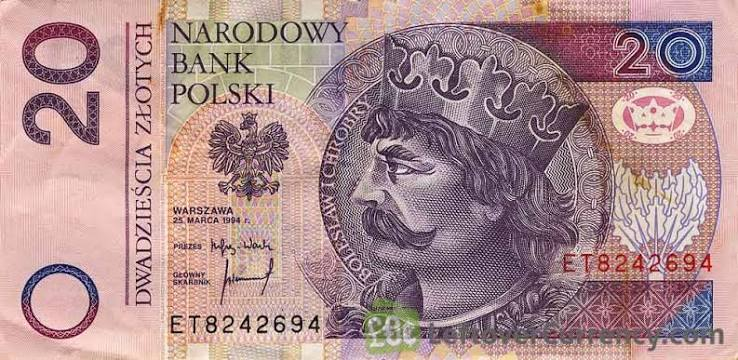
20 zł: Mainly pink and purple, featuring Bolesław I the Brave, with a denarius and Romanesque architecture on the reverse.

__wf_reserved_inherit

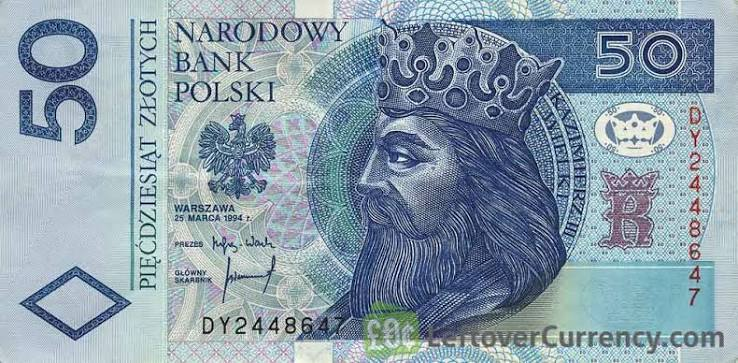
50 zł: Blue, featuring Casimir III the Great. Its reverse includes the royal seal and architectural details.

__wf_reserved_inherit

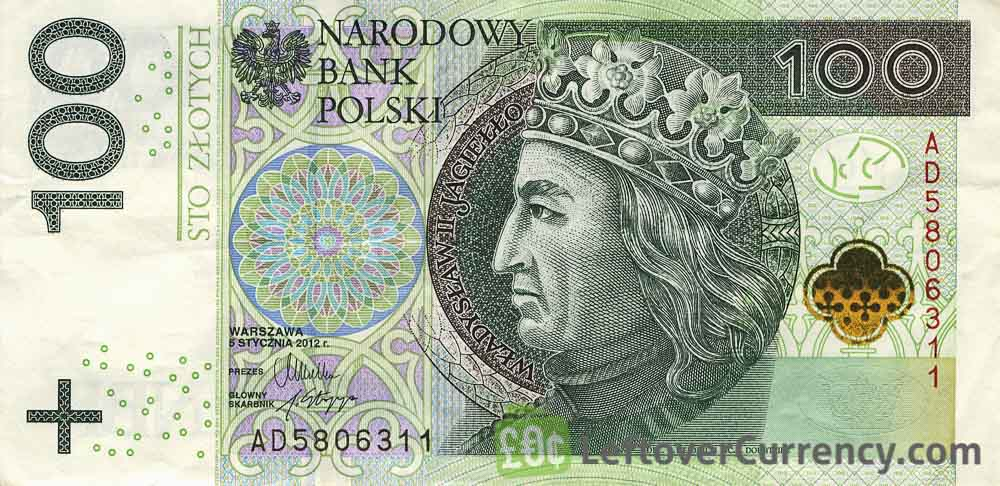
100 zł: Green and brown, featuring Władysław II Jagiełło, with the White Eagle and Teutonic Knights’ symbolism on the reverse.

__wf_reserved_inherit

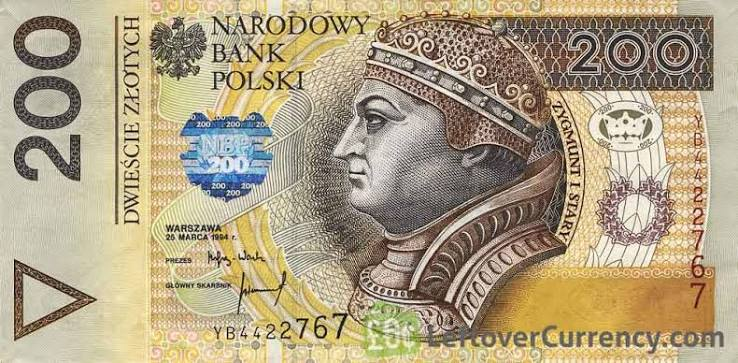
200 zł: Brown and yellow, featuring Sigismund I the Old, with the Wawel Castle chapel and royal eagle.

__wf_reserved_inherit

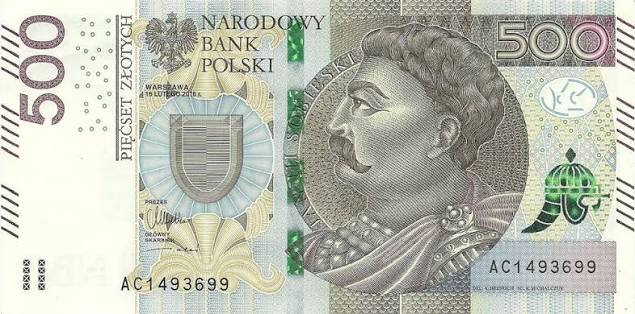
500 zł: Dark blue and brown, featuring John III Sobieski, with the Wilanów Palace and eagle on the reverse.

__wf_reserved_inherit

Coins range from tiny 1 grosz pieces to larger 5 zł coins, with 1 zł, 2 zł and 5 zł being the main złoty denominations.

What’s the exchange value of the złoty vs the USD and EUR?

The Polish złoty does not remain at a single value against the dollar or the euro. Its exchange rate moves as investors react to Poland’s interest rates, inflation, economic data and wider conditions in European markets. For anyone travelling, studying, working or sending money to Poland, even a small movement can change how much your money is worth.

As a guide, recent mid-market exchange rates put US$1 at around PLN 3.69 and €1 at around PLN 4.31, although live rates move throughout the day. The złoty’s performance can also shift against the dollar and euro at different speeds, so it is worth checking the specific pair you need rather than relying on an old conversion.

For the latest rate, you can check live market data on Trading Economics or use a live currency converter before exchanging money. If you are converting a larger amount, also check the provider’s spread and fees, as the rate shown on a market tracker is not necessarily the rate you will receive.

Also read: How to avoid foreign transaction fees when travelling abroad

How to get and spend złoty when travelling in Poland

Arriving in Poland with euros, dollars, or another currency leaves you with a simple decision: exchange some cash, withdraw złoty from an ATM or pay by card. Card payments are widely accepted in cities, hotels, restaurants, shops and transport services, but keeping some cash is useful for smaller purchases or places that do not accept cards.

ATMs make it easy to get złoty when needed, although the exchange rate and fees can differ between providers. If an ATM or card terminal asks whether you want to pay in PLN or convert the transaction into your home currency, choosing PLN is generally the safer option because it lets your card provider handle the conversion rather than accepting the machine’s own rate.

A Grey Card can also be useful for everyday spending in Poland. After downloading the Grey app and setting up your account, you can manage your money digitally and use the card wherever Visa is accepted, subject to applicable restrictions. This gives you another option for paying abroad without carrying large amounts of cash.

Frequently asked questions

Does Poland use the euro?

No. Poland uses the Polish złoty (PLN) for everyday transactions rather than the euro. Although Poland is an EU member, it has not joined the eurozone. Prices in shops, restaurants, hotels and other businesses are therefore normally displayed in złoty, so travellers using euros should check the current PLN exchange rate.

What is the symbol for the złoty?

The Polish złoty is written with the symbol zł, while PLN is its international three-letter currency code. You may see a price such as 50 zł in a Polish shop, while banks and currency platforms may display the same amount as 50 PLN. Both refer to the Polish złoty.

How much is 1 US dollar in Polish złoty?

At the current mid-market rate, US$1 is worth about 3.72 Polish złoty (PLN). Rates move throughout the day, so the amount you actually receive when exchanging money may be slightly different depending on the provider and any fees or markup they apply.

What is grosz?

Grosz is the smaller unit of the Polish złoty. One złoty contains 100 grosz, much like one dollar contains 100 cents. You will see grosz when paying for inexpensive items or when prices include smaller amounts. For example, 12.50 zł means 12 złoty and 50 grosz.

Can I use my card in Poland?

Yes. Visa and Mastercard are widely accepted across Poland, particularly in supermarkets, hotels, restaurants, shops and other businesses in towns and cities. A Grey Card can also be used for eligible purchases wherever Visa is accepted, subject to the card’s terms, giving travellers another way to pay without carrying much cash.

How do I send money to Poland?

Money can be sent to Poland through international bank transfers or online money services. The important thing is to compare the exchange rate, transfer fee and delivery time before choosing a provider. If you use Grey, you can manage supported currencies through the app and send money to Poland.

How to check a Visa gift card balance

•

•

2 min read

Getting a Visa gift card can feel like having a little spending money tucked away for whenever you need it. But whether you received the card as a gift, bought one for someone else, or are using it for everyday purchases, there is one thing you need to keep track of: how much money is left.

Unlike a regular bank account, a Visa gift card does not always show your available balance when you make a purchase. If you are about to buy something online, pay for dinner or use the card while travelling, checking the balance first can help you avoid an awkward declined transaction.

Fortunately, finding your remaining balance is usually quick. Most Visa gift cards offer several ways to check, including online, by phone or sometimes at a participating retailer. The exact process can vary by card issuer, so knowing where to look is the first step.

In this guide, we explain how to check your Visa gift card balance and what information you may need.

Also read: Visa eGift Cards and Digital Visa Cards Explained

How to check your Visa gift card balance

1. Check your balance online

The quickest option is usually the website printed on the back of your Visa gift card. Most issuers provide a balance-checking page that allows you to view your remaining funds in just a few steps.

  • Visit the website shown on the card.
  • Enter your card number.
  • Add the expiry date and security code if requested.
  • Submit the details to view your available balance.

This is particularly useful if you are shopping online or planning a larger purchase and want to know exactly what you have available.

2. Check by phone

Prefer speaking to someone or do not have internet access? Look at the back of the card for the issuer's customer service or toll-free number.

  • Call the number printed on the card.
  • Follow the automated instructions.
  • Enter your card number and other requested details.
  • Listen for your current balance.

3. Check in store

If you are already out shopping, you may be able to ask a cashier to check the balance for you.

Simply hand over the card and ask if they can check the remaining balance. Not every retailer offers this service, so it is worth confirming before relying on this method.

Whichever option you use, check the card issuer's instructions first, as the process can vary between Visa gift cards.

Also read: Debit card vs Credit card: What is the difference?

What you need to check the balance

Before checking your Visa gift card balance, it helps to have the card nearby because you will usually need a few details from it. These details confirm that you are checking the correct card and help protect your balance information.

Card number

Your card number is the long series of digits printed on the front or back of the card. You will usually need to enter all the digits exactly as shown.

Expiry date

The expiry date tells you how long the card is valid for. It is typically printed on the front of the card and displayed as a month and year.

Security code

The security code, often called a CVV or CVC, is a short three-digit number used to verify the card. Depending on the issuer, you will usually find it on the back.

Where to find these details

Before checking your balance online or by phone, have your card number, expiry date and security code ready. The exact location and terminology can vary between issuers, so follow the instructions provided on your specific card.

How to troubleshoot a wrong or zero Visa gift card balance

When a Visa gift card shows a wrong or zero balance, pending transactions, activation problems or an expired card could be responsible.

Check for pending holds

A pending transaction can temporarily reduce the amount available on your card. Hotels, car rental companies and some online merchants may place a temporary hold that affects your available balance even before the final amount is processed.

Confirm the card is activated

If your Visa gift card is showing no available balance, check whether it has actually been activated. Some cards require activation before you can use them or access certain card information. Follow the activation instructions provided with the card, usually found on the packaging or issuer’s website.

Check whether the card has expired

Check the expiry date if your card suddenly stops working or appears to have a zero balance. An expired card generally cannot be used for new purchases, but that does not necessarily mean any remaining funds have disappeared. Contact the card issuer to understand what happens to the balance.

How to spend the remaining balance on a Visa gift card

A Visa gift card with only a few dollars left can be surprisingly difficult to spend. Most purchases exceed the remaining balance, leaving the card unused. One solution is a split-tender payment, where part of the purchase is charged to the gift card and the rest is paid with another card or cash. For example, an $8 balance could cover the first $8 of a $20 purchase, with the remaining $12 paid separately. This option is usually available at participating retailers, although policies vary.

Another possibility is combining the gift card with another payment method when shopping online. Some websites allow multiple payment methods during checkout, while others only accept one card per transaction. If neither option is available, the remaining balance can be used for a smaller purchase that fits within the available funds. Checking the balance beforehand makes it easier to choose a suitable purchase and avoid a declined transaction.

What is the best alternative to a gift card?

Gift cards are convenient, but they are not always the most flexible option. Once the balance runs down, the card often ends up forgotten in a drawer, even when the recipient may still need a convenient way to spend money online or abroad.

Grey’s virtual cards allow supported users to create multiple cards, spend directly from their Grey account without separately funding each card, and manage spending limits from the app. Cards can also be frozen and unfrozen when needed, giving users more control over recurring online purchases and international spending.

This can be particularly useful for people who regularly pay for international subscriptions, online services or purchases from overseas merchants. Instead of treating each payment as a one-off transaction, the same account and cards can be managed over time.

Frequently asked questions

How do I check my Visa gift card balance?

The easiest way is usually through the website or phone number printed on the back of the card. You may need to enter the card number, expiry date and security code. Some retailers may also check the balance at checkout.

Why is my balance zero?

A zero balance does not always mean the money has been spent. A pending transaction or temporary merchant hold could reduce the available amount. The card may also be inactive or expired. Check recent transactions and contact the card issuer if the balance still looks incorrect.

Can I check the balance in a store?

Some retailers allow customers to check their Visa gift card balance at checkout, although this service is not available everywhere. Ask the cashier before making a purchase. Having the physical card with you will usually make it easier for staff to check the available balance.

Does a Visa gift card expire?

Visa gift cards can have an expiry date, which is normally printed on the card. An expired card may no longer work for purchases, but the treatment of any remaining balance depends on the issuer and local regulations. Check the card terms or contact the issuer for clarification.

Can I use the remaining balance online?

Yes, a remaining Visa gift card balance can generally be used online if the merchant accepts Visa and the card meets its requirements. The purchase amount must not exceed the available balance unless the retailer supports split payments. Some online merchants may also place temporary authorisation holds.

Can I reload a Visa gift card?

Most traditional Visa gift cards are not designed to be reloaded once the original balance has been spent. However, some prepaid Visa products are reloadable. The difference depends on the card type and issuer, so check the packaging or card terms before attempting to add more funds.

How to get paid by Amazon in South Africa with Grey

•

•

2 min read

Selling products or earning through Amazon’s affiliate and freelance platforms is a great way to tap into global income streams. But for many South Africans, there’s one persistent challenge — how do you get paid?

That’s where Grey comes in. Grey gives South Africans access to virtual foreign accounts, so you can get paid in Amazon’s preferred currencies and easily convert or withdraw your money.

In this guide, I’ll show you exactly how to get paid by Amazon in South Africa with Grey.

How Amazon pays sellers, affiliates, and freelancers

Amazon uses a standardised system to distribute earnings. You will receive your payouts directly to the bank details you provide.

Here’s how it works:

  • Earnings calculation: Amazon deducts fees and refunds from your sales or commissions.
  • Payment cycles: Most payouts are made every 14 days (biweekly), but this may vary depending on account type and region.
  • Currency: Amazon disburses funds in the local currency of the marketplace (e.g., USD for Amazon.com, GBP for Amazon UK), so a multi-currency account is essential.
  • Bank account requirements: You must add a compatible bank account that matches the payout currency — this is where Grey becomes your best option.

Also read: How to get paid by Amazon in Nigeria, Kenya, and Tanzania with Grey

Why Grey is the best way to get paid by Amazon in South Africa

Grey is a cross-border financial platform that makes international payments easy for freelancers, digital entrepreneurs, and remote workers. With a Grey account, you can:

  • Create virtual USD, GBP, and EUR accounts — perfect for receiving Amazon payouts.
  • Receive payments directly into your foreign account without delays or rejections.
  • Convert funds to South African rand (ZAR) at competitive exchange rates.
  • Withdraw funds locally to your bank account or mobile wallet.

Also read: How freelancers in South Africa can receive payments from the US, UK & EU clients

Step-by-step: How to get paid by Amazon using Grey

Here’s how to set up and receive your Amazon payments through Grey:

1. Open a Grey account

Visit the Grey website or download the Grey app and sign up for free. Fill in your name, email, and phone number to get started.

2. Verify your identity

Upload a valid ID, proof of address, and a selfie. This is required to activate your virtual foreign bank accounts.

3. Generate your bank account details

Once verified, you can create foreign accounts (USD, GBP, or EUR) from your Grey dashboard. These include:

  • IBAN
  • SWIFT/BIC
  • Account number
  • Bank name and address

4. Add Grey account to Amazon Seller Central or Affiliate dashboard

  • Go to Amazon Seller Central or your Amazon Affiliate dashboard.
  • Navigate to Settings > Payment Information.
  • Select “Add new bank account”.
  • Enter your Grey-provided virtual bank account details in the correct currency (e.g., USD for Amazon.com).
  • Save changes.

5. Get paid and withdraw

Once Amazon releases your funds, they’ll arrive in your Grey account. You can:

  • Hold in foreign currency until the exchange rate favours you.
  • Convert to ZAR at competitive rates.
  • Withdraw directly to your local South African bank account.

Also read: How to open a US and UK bank account in South Africa

Tips to make the most of your Amazon payouts with Grey

Here are a few ways you can maximize your Amazon payouts with Grey.

  • Avoid instant conversions if the exchange rate is low — Grey lets you hold multiple currencies.
  • Track your payments in real time using the Grey app or website.
  • Split payouts if you have multiple Amazon accounts or freelance gigs.
  • Stay compliant by keeping a record of your foreign payments for tax purposes.

Get paid by Amazon in South Africa

With Grey, getting paid by Amazon in South Africa is fast, affordable, and stress-free. No more rejected payments, currency conversion issues, or high international transfer fees.

If you’re ready to simplify your finances and get paid like a pro, create your Grey account today or download the app to receive Amazon payouts in USD, GBP, or EUR and convert them to rand with ease.

‍

Arrow (up)

Back to top