


<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/your-comprehensive-guide-to-greys-virtual-card-answers-to-common-questions#article","headline":"Your comprehensive guide to Grey's virtual card: Answers to common questions","description":"Learn everything you need to know about the Grey virtual card, how to use it for shopping and make payments. Get ready for Black Friday deals and start shopping securely today!","inLanguage":"en","url":"https://grey.co/blog/your-comprehensive-guide-to-greys-virtual-card-answers-to-common-questions","mainEntityOfPage":{"@id":"https://grey.co/blog/your-comprehensive-guide-to-greys-virtual-card-answers-to-common-questions#webpage"},"datePublished":"2023-11-23T13:20:26.632Z","dateModified":"2026-06-15T15:33:37.153Z","author":{"@type":"Person","@id":"https://grey.co/authors/toluwani-omotesho#person","name":"Toluwani Omotesho","url":"https://grey.co/authors/toluwani-omotesho"},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/your-comprehensive-guide-to-greys-virtual-card-answers-to-common-questions#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a301b5051e9fcfea6caf77f_6a301b4f8693c6a5eb43880e_your-comprehensive-guide-to-greys-virtual-card-answers-to-common-questions__header-image.webp","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a301b5051e9fcfea6caf77f_6a301b4f8693c6a5eb43880e_your-comprehensive-guide-to-greys-virtual-card-answers-to-common-questions__header-image.webp","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/your-comprehensive-guide-to-greys-virtual-card-answers-to-common-questions#webpage","url":"https://grey.co/blog/your-comprehensive-guide-to-greys-virtual-card-answers-to-common-questions","name":"Your comprehensive guide to Grey's virtual card: Answers to common questions","description":"Learn everything you need to know about the Grey virtual card, how to use it for shopping and make payments. Get ready for Black Friday deals and start shopping securely today!","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/your-comprehensive-guide-to-greys-virtual-card-answers-to-common-questions#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/your-comprehensive-guide-to-greys-virtual-card-answers-to-common-questions#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/your-comprehensive-guide-to-greys-virtual-card-answers-to-common-questions#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"Your comprehensive guide to Grey's virtual card: Answers to common questions","item":"https://grey.co/blog/your-comprehensive-guide-to-greys-virtual-card-answers-to-common-questions"}]}] </script>

Your comprehensive guide to Grey's virtual card: Answers to common questions

Toluwani Omotesho

TABLE OF CONTENT

SHARE THIS POST

Thanks to the Black Friday sales, it’s raining discounts soon. The best part is that with a Grey virtual card, you don’t have to miss out on any of these offers, especially from your favorite international stores and brands. You can use your Grey virtual card to make payments on any platform or website that supports a US card, for instance, Apple, Udemy, Crunchyroll, Spotify, and many more.

However, to make your shopping experience easier, we’ll answer some common questions about the Grey card in this post.

1. How can I use it on AliExpress?

First things first, before making any transaction using your virtual card, it’s important to double-check that it’s adequately funded, as having two failed transactions from insufficient funds will lead to your card being flagged or frozen.

Now, to make payments on AliExpress using your Grey card, the process is quite straightforward. All you have to do is go to the payment section in your account and add a new card. You’ll fill out a short form with the following details: the card number, CVV, card name, and date, and be charged $1 by AliExpress for verification reasons.

After successfully adding your Grey card, you can easily select it as your preferred payment method at checkout.

If your virtual card is rejected, it’s usually due to one of the following reasons:

  • Incorrect card details
  • Incorrect card expiry date
  • Security measures from AliExpress, and you can appeal this by submitting the required documents to prove your identity.

2. Can I receive payments and withdraw from my card?

You can’t receive payments with your virtual card but can withdraw from it. However, a minimum of $1 must be left.

To withdraw from your card, all you have to do is reach out to our support team at support@grey.co, stating the amount you want to withdraw, and your request will be reviewed within 24 hours.

3. Can I use it to pay for my Apple subscriptions?

Of course! But because Grey virtual cards are USD cards, they’d only work in a US Apple store. So, you’re going to have to switch to a US store on your phone, which you can easily do on your settings app in five simple steps:

  • Tap your name and go to Media and Purchases.
  • Select view account (you might need to sign in again)
  • Tap Country/Region and select “Change Country and Region.”
  • Select your new country/region (i.e., the United States) and review the terms and conditions.
  • And finally, agree and confirm
  • Once you’ve confirmed this, you’ll be asked to put in your payment information, which would be the details of your Grey card, and that’s it! You no longer have to jump hoops to make Apple payments.

4. Does my Grey card support all types of transactions?

The short answer to this is no. The Grey virtual card doesn’t support the following transactions:

  • Cryptocurrency
  • Adult entertainment and pornography
  • Gambling
  • Sports betting
  • Drug paraphernalia — items used for drug use
  • For security reasons, your card would get blocked if used on any of these restricted websites.

Wrapping up

For only $4, you can easily create your own Grey virtual card, and you don’t have to worry about paying extra charges for card maintenance, transactions, or funding. Also, there are no hidden fees! So take the first step towards a life of easy and convenient payments by opening a Grey account today.

‍

Last updated:

October 2, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

FX futures trading: How currency futures work

•

•

2 min read

If you’ve read our FX trading beginner's guide, you already know that the forex market is primarily an over-the-counter market, with no central exchange and trades happening directly between participants. FX futures are different. They are exchange-traded, standardised contracts regulated by a recognised authority, with fixed contract sizes, set expiration dates, and publicly visible prices.

That distinction matters. It shapes everything from how you access the market to who regulates it to how much it costs to trade. This guide explains how FX futures work mechanically, how they compare to spot FX, and when they’re the right tool for a specific financial problem, and when they’re not.

What is FX futures trading?

FX futures trading is the buying and selling of standardised contracts that commit the holder to exchange a specified amount of one currency for another at a predetermined price on a specific future date.

Unlike spot FX, where currencies are bought and sold for immediate delivery (typically two business days), FX futures contracts have a defined expiration date in the future, typically quarterly: March, June, September, and December. You don’t have to hold the contract until expiration: most futures positions are closed before the contract expires by taking the opposite position.

The major FX futures markets are operated by CME Group, which runs the Chicago Mercantile Exchange (CME). The CME is one of the world’s largest derivatives exchanges and lists futures contracts on major currency pairs, including EUR/USD, GBP/USD, USD/JPY, AUD/USD, CAD/USD, CHF/USD, and MXN/USD, among others.

Because FX futures trade on a regulated exchange rather than over-the-counter, all participants see the same prices, all transactions are cleared through a central counterparty (the CME Clearing House), and the Commodity Futures Trading Commission (CFTC) in the US regulates the market. This centralised structure is one of the primary differences from spot FX.

Currency futures explained

Understanding the mechanics of a currency futures contract requires knowing its key specifications. Here is how the major CME EUR/USD futures contract works, using CME Group’s published contract specifications.

Contract size: Each EUR/USD futures contract represents 125,000 euros. This is the standardised unit. You cannot trade a partial contract: if you want exposure to EUR/USD, the minimum is one full contract worth 125,000 euros.

Tick size: The minimum price movement (tick) for EUR/USD futures is 0.00005 dollars per euro, which equals $6.25 per contract (125,000 × 0.00005). This is the smallest profit or loss increment per contract per tick.

Expiration months: EUR/USD futures expire quarterly: March, June, September, and December. The contract expiration date is the third Wednesday of the delivery month. The front-month contract (the one with the nearest expiration date) is typically the most liquid.

Settlement: CME currency futures are physically settled, meaning the actual exchange of currency can occur at expiration if a position is held open. In practice, most traders close their positions before expiration by taking the opposite trade, avoiding physical delivery.

Margin requirements: To trade FX futures, you don’t pay the full value of the contract upfront. You deposit an initial margin, a percentage of the contract’s notional value, as a performance bond. CME publishes initial and maintenance margin requirements. For EUR/USD futures, initial margin requirements vary but are typically between $2,000 and $3,000 per contract, depending on market volatility. This means you’re controlling a contract worth approximately $137,500 (at EUR/USD 1.10) with a margin of a few thousand dollars.

Mark-to-market: Unlike some financial instruments, futures positions are marked to market daily. At the end of each trading session, gains and losses are calculated based on the day’s settlement price and credited or debited from your margin account. If your account falls below the maintenance margin level, you receive a margin call and must deposit additional funds or have your position liquidated.

How to trade FX futures

Trading FX futures requires access to a futures broker and a funded margin account. The process differs from opening a standard retail forex account.

  1. Choose a CFTC-regulated futures broker
    FX futures must be traded through a registered Futures Commission Merchant (FCM). Check CFTC registration at cftc.gov before depositing funds with any broker. Major regulated FCMs include Interactive Brokers, TD Ameritrade Futures, and others. Verify that the broker specifically offers access to CME currency futures.
  2. Open a futures account and complete compliance requirements
    Futures accounts require more documentation than standard brokerage accounts. You’ll complete risk disclosures, provide financial information, and confirm you understand the risks of leveraged derivatives trading.
  3. Deposit initial margin
    Transfer funds to meet the initial margin requirement for the number of contracts you intend to trade. Remember that margin requirements can change based on market volatility: CME can raise them at any time.
  4. Place an order. Select the contract (e.g., EURO FX Futures, symbol 6E), the expiration month, the direction (buy or sell), and the order type (market, limit, or stop). Your broker’s platform will show the current bid and ask price for the contract.
  5. Monitor your position and margin
    Because futures are marked to market daily, your account balance will change each day based on price movement. Monitor your account to ensure it remains above the maintenance margin.
  6. Close or roll before expiration
    To exit a long position, sell the same number of contracts in the same expiration month. To exit a short position, buy. To maintain exposure beyond the current contract’s expiration, “roll” the position by closing the front-month contract and opening the next expiration month.

FX futures vs spot trading

The two primary ways to trade currency markets are FX futures (exchange-traded, standardised, regulated) and spot FX (over-the-counter, flexible, broker-dependent). Here’s how they compare:

Feature FX futures Spot FX (retail forex)
Trading venue Regulated exchange (CME, ICE) Over-the-counter, through brokers
Regulation CFTC (US), FCA (UK), other regulators Varies; some markets lightly regulated
Price transparency Full order book visible; same price for all participants Broker-set spread; prices can vary between brokers
Contract size Standardised (EUR/USD = 125,000 EUR) Flexible; can trade micro lots (1,000 units)
Minimum trade size One contract (typically large notional value) Much smaller; micro lots available
Settlement Physical delivery at expiration (usually closed before) Cash settled; no physical delivery
Leverage Yes; margin-based Yes; margin-based (often higher leverage available)
Expiration Quarterly expiration dates No expiration; positions held indefinitely
Counterparty risk Cleared by exchange (low; exchange guarantees trades) Counterparty is the broker (higher risk with unregulated brokers)
Transaction costs Commission per contract plus bid-ask spread Spread only (plus sometimes swap/overnight fees)
Who uses it Institutional hedgers, professional traders Retail traders, smaller hedgers
Access Requires futures broker account Retail forex broker account

‍

The key practical differences: FX futures offer greater regulatory protection and price transparency, but the standardised contract sizes make them less accessible for small-volume traders. Spot FX offers more flexibility on position size, but with variable broker quality and less regulatory oversight in some jurisdictions.

Hedging with FX futures

One of the primary legitimate uses of FX futures, beyond speculation, is hedging: locking in an exchange rate for a future transaction to protect against adverse currency movement.

Worked example: a UK exporter hedging a USD receivable

A UK manufacturer has agreed to sell £500,000 worth of equipment to a US buyer. The invoice is denominated in USD at today’s GBP/USD rate of 1.27, making the USD invoice amount approximately $635,000. Payment is due in three months.

The risk: if the pound strengthens against the dollar (GBP/USD rises) over those three months, the $635,000 will convert to fewer pounds when received. At GBP/USD 1.35, for example, the same $635,000 would only convert to approximately £470,000, a loss of £30,000 versus today’s rate.

The hedge: the exporter sells GBP/USD futures contracts with an approximate notional value of $635,000. If GBP/USD rises to 1.35, the exporter’s futures position profits, offsetting the loss on the physical receivable. If GBP/USD falls (good news for the exporter), the futures position loses money, but that loss is offset by the better conversion rate on the physical USD received.

The hedge doesn’t make the exporter money. It removes the currency risk, allowing the business to plan based on a known effective exchange rate rather than an unknown future rate. This is what hedging is for.

Who uses FX futures to hedge:

Exporters and importers who invoice in foreign currencies, multinational companies consolidating overseas earnings, and fund managers with foreign currency exposure in their portfolios. For most of these users, the objective is risk reduction, not profit generation.

Risks of FX futures trading

The risks in FX futures are specific and worth naming precisely.

Leverage risk: A $3,000 margin controls a contract worth approximately $137,500. A 1% adverse move in EUR/USD costs approximately $1,375 per contract, nearly 50% of the initial margin. The same move in the favourable direction yields the same gain, but most traders focus on the asymmetry: losses can quickly exceed the initial deposit.

Margin calls: If the market moves against your position and your account balance falls below the maintenance margin level, your broker will issue a margin call: deposit more funds immediately or have your position closed at the current market price, potentially at a significant loss.

Expiration management: Futures contracts expire. If you’re not actively monitoring your position, a contract you intended to hold can expire without you realising it, resulting in automatic closing at the expiration settlement price or, for physically settled contracts, an obligation to deliver or receive currency.

Basis risk for hedgers: FX futures hedge currency risk but introduce basis risk: the risk that the futures price and the spot price don’t move perfectly in tandem. For most major currency pairs, basis risk is small, but it exists and means a futures hedge is rarely a perfect offset.

Liquidity risk in less active contracts: Front-month contracts for major pairs (EUR/USD, GBP/USD, USD/JPY) are highly liquid. Further-out expiration months and minor pair contracts can be less liquid, meaning wider bid-ask spreads and potentially difficulty closing positions at the desired price.

A simpler way to manage real-world currency exposure

FX futures are a sophisticated tool designed primarily for institutional hedgers and experienced traders who need to manage specific, quantifiable currency exposures. For most freelancers, remote workers, expats, and small business owners, the practical currency problem is different: receiving income in one currency, holding it efficiently, and converting at a fair rate when needed.

That doesn’t require a futures account. It requires a multi-currency account with a competitive conversion rate.

Grey lets you hold balances in USD, EUR, and GBP, receive payments from international clients through local payment rails (ACH for USD, SEPA for EUR, Faster Payments for GBP), and convert currencies at mid-market rates with Grey at a conversion fee of 1%, capped at $6. The conversion rate is shown before you confirm; there’s no expiration date to manage, no margin calls, and no leverage amplifying your exposure.

For someone who needs to hold USD earned from US clients and convert it to GBP or local currency at an appropriate time, opening a multi-currency account with Grey is a more practical approach than establishing a futures hedging programme. FX futures are the right tool for managing large, quantifiable, time-specific currency exposures. For everyday multi-currency financial management, a Grey account is more practical.
Download the Grey app today to begin.

Frequently asked questions

What is the minimum to trade FX futures?

The minimum to trade FX futures is the initial margin requirement for one contract, plus enough buffer to avoid an immediate margin call if the market moves against you. For EUR/USD futures on the CME, initial margin requirements are typically $2,000 to $3,000 per contract, but this varies with market volatility and can be raised by the exchange at any time. In practice, most experienced futures traders maintain significantly more than the minimum margin in their account to absorb adverse moves without being forced out of a position.

How are FX futures different from forex spot trading?

FX futures are standardised contracts traded on regulated exchanges like the CME, with fixed contract sizes, quarterly expiration dates, and prices visible to all participants equally. Spot forex is traded over-the-counter through brokers, with flexible position sizes, no expiration dates, and prices set by the broker. Futures offer greater regulatory oversight and price transparency but require larger minimum positions. Spot forex is more accessible to retail traders, but broker quality and regulatory protection vary by jurisdiction.

Are FX futures suitable for beginners?

No. FX futures involve leverage, daily mark-to-market settlement, contract expiration management, and margin call risk. The standardised contract sizes mean a single EUR/USD futures contract controls 125,000 euros, which represents significant notional exposure for a beginning trader. Beginners who want to understand currency markets should start with educational reading rather than live trading, practice on simulated accounts before risking capital, and understand leverage mechanics fully before entering any leveraged position. The FX trading beginner's guide covers foundational concepts for those starting from scratch.

What is the contract size for EUR/USD futures?

One EUR/USD futures contract on the CME represents 125,000 euros. At an exchange rate of EUR/USD 1.10, one contract has a notional value of approximately $137,500. The minimum price move (tick) is 0.00005, worth $6.25 per contract. CME also offers E-micro EUR/USD futures contracts at one-tenth the size (12,500 euros per contract), which lowers the capital required per contract and may be more accessible for smaller traders.

When do FX futures expire?

CME currency futures expire quarterly: in March, June, September, and December. The specific expiration date is the third Wednesday of the delivery month, though the last trading day is typically the Monday before that Wednesday. Most traders close their positions before expiration to avoid the settlement process. Those who want to maintain exposure beyond the front-month contract “roll” their position by closing the expiring contract and opening the next quarterly contract.

Is Grey an alternative to FX futures for hedging small businesses?

For small businesses with straightforward multi-currency needs, Grey addresses the practical problem more simply than futures contracts do. A Grey multi-currency account lets you hold USD, EUR, and GBP balances, receive payments from international clients at low cost, and convert at a transparent rate. This is effective for managing the timing of currency conversion and avoiding forced conversion at poor bank rates, which covers the currency exposure most small businesses actually face. FX futures are appropriate when a business has a specific, large, time-defined currency exposure it needs to hedge precisely, such as a confirmed export contract in a foreign currency with a known settlement date. For most small businesses, that level of complexity and capital commitment isn’t justified.
Convert currencies with Grey

How much should you save from each paycheck?

•

•

2 min read

There is no single correct answer to how much of each paycheck you should save. What can help, however, are guidelines and methods for determining what’s realistic for your specific income, costs, and goals.

The most common mistake in savings advice is presenting targets as fixed obligations rather than starting points. Telling someone they must save 20% of their income when their rent takes up 50% of it is great, but it isn’t always helpful. Neither is suggesting they save nothing until the perfect amount is clear. The right savings rate is the highest one you can maintain consistently, and it will change as your income and circumstances do.

This guide covers the standard guidelines, how to adapt them, and how to make saving automatic so the decision doesn’t have to happen every payday.

How much of each paycheck should you save?

The most widely cited starting point is 20% of your take-home pay. This figure comes from the 50/30/20 rule, a budgeting framework that allocates income across three broad categories.

For many people in high-cost-of-living areas, or in the early stages of their careers when income is lower, and rent takes a larger share, 20% is not realistic from day one. That’s fine. The goal is to establish a consistent saving habit at whatever level is sustainable now, and increase it over time.

A more useful framing than a fixed percentage is to build an emergency fund first. Before you think about longer-term savings goals, having three months of essential expenses set aside protects you from going into debt when something unexpected happens. Once that foundation is in place, directing additional savings toward specific goals becomes the priority.

If you're starting from nothing and 20% feels out of reach, start with 5%. On a £2,000 monthly take-home, that’s £100. It won’t build wealth quickly, but it establishes the habit and the account structure that larger contributions can flow into as your income grows. Consistently saving a small amount reliably beats irregularly saving a large amount.

The 50/30/20 rule and other savings percentages

The 50/30/20 rule divides your take-home pay into three categories

50% for needs: Essential expenses that you can't avoid: rent or mortgage, utilities, groceries, insurance, transport to work, and minimum debt repayments. If this category is consuming more than 50% of your take-home pay, which is common in high-cost cities, the other percentages have to adjust accordingly.

30% for wants: Discretionary spending: dining out, subscriptions, entertainment, holidays, and new clothes. This is the category that can be reduced most easily if you need to redirect more toward savings.

20% for savings and debt repayment. This covers everything from an emergency fund to retirement contributions to a deposit for a flat. If you carry high-interest debt, prioritising accelerated debt repayment within this 20% makes sense before directing it all toward long-term savings.

Here’s a worked example on a take-home salary of £2,400 per month:

Category Percentage Monthly amount
Needs (rent, utilities, groceries, transport) 50% £1,200
Wants (dining out, subscriptions, entertainment) 30% £720
Savings and debt repayment 20% £480

‍

For someone whose needs take 60% of income, the adjusted version might look like:

Category Percentage Monthly amount
Needs 60% £1,440
Wants 20% £480
Savings 20% £480

‍

The saving percentage stays the same while the wants category absorbs the adjustment.

Alternative savings percentages

The Consumer Financial Protection Bureau notes that the right savings rate varies significantly by household size, income level, and financial goals. Some financial planners suggest directing the first 10% of income to retirement savings before anything else, treating it as non-negotiable. Others advocate a flat 1% annual increase, so someone saving 5% today saves 6% next year, 7% the year after, and reaches 20% over time without a single dramatic change.

The common thread across all frameworks is that you should consistently save, increase it gradually, and automate it so the decision doesn’t require willpower each month.

How to set your own savings target

A more reliable method than applying a percentage is working backwards from your actual goals.

List every financial goal you’re currently saving toward or know you should be: an emergency fund, a holiday, a deposit, a career break fund, or retirement. Give each one a target amount and a date. Divide each target by the number of months until the deadline. This gives you the minimum monthly contribution required for each goal.

Add the required contributions together. That’s your savings floor. It’s the minimum you need to save each month to hit every goal on the current timeline. If it’s more than you can currently direct toward savings, something has to give: a timeline extends, a target reduces, or spending in another category decreases.

For people with irregular income, freelancers, contractors, and commission-based workers, a fixed percentage works better than a fixed amount. Saving 15 or 20% of whatever comes in means savings scale with income without requiring monthly adjustments. In low-income months, contributions are lower. In high-income months, they're higher. The percentage stays consistent.

For decisions about whether to direct savings toward short-term goals or longer-term investments, see our guide on saving vs investing. The answer varies depending on your timeline and the specific goal. For people in economies where local currency devaluation is a concern, consider holding savings in a stable currency when structuring your emergency fund and medium-term savings.

How to automate saving every payday

The most reliable savings system is one that doesn’t require a decision each month. When saving is automatic, it happens in good months and difficult months equally, without relying on remembering or on having enough willpower to resist spending first.

The principle is called paying yourself first. Before any discretionary spending, before any non-essential transfers, a fixed amount moves from your income account to your savings account on payday. What remains in the income account is what you spend. You never see the savings as available.

Here’s how to set it up:

Step one: Decide your monthly contribution amount or percentage. Use the worked method above if the right figure isn’t clear.

Step two: Set up a standing order or automatic transfer to leave your account on the same day your salary arrives, or the day after.

Step three: Direct that transfer to a separate account or named goal, not your current account. When savings sit in the same account as spending money, they get spent. A named goal with a visible target and a separate balance is significantly harder to spend casually.

Grey's Pouch feature lets you set money aside for each financial target you're working toward. Each Pouch is named, has a target amount, and is separate from your main balance. You can also save part of it in USD if protecting against local currency depreciation is relevant to your situation. The combination of automation and separation is what makes saving consistent over time rather than occasional.

Set up a Pouch goal with Grey and move a set amount aside every payday at grey.co/pouch.

Frequently asked questions

How much should I save per paycheck?

The 50/30/20 rule suggests saving 20% of take-home pay. In practice, the right amount is the highest percentage you can save consistently, given your actual income and costs. Starting at 5 to 10% is reasonable if 20% isn't currently achievable. The priority is establishing a consistent habit and increasing the percentage incrementally over time, particularly when income rises.

Is saving 20% of income enough?

For most people at most stages of life, 20% is a solid savings rate that covers an emergency fund, retirement contributions, and medium-term goals if maintained consistently over time. Whether it's "enough" depends on your specific goals, your timeline, and when you start. Someone who starts saving 20% at 22 is in a very different position from someone who starts at 42. Earlier is always better, and more is always better, but 20% consistently over a long period produces substantial results.

What is the 50/30/20 rule?

The 50/30/20 rule is a budgeting framework that divides take-home pay into three categories: 50% for needs (rent, utilities, groceries, insurance, minimum debt payments), 30% for wants (dining out, subscriptions, entertainment), and 20% for savings and debt repayment. It's a starting structure, not a fixed rule. People in high-cost areas often need to allocate more to needs, which adjusts the other categories accordingly.

Should I save or pay off debt first?

It depends on the interest rate on the debt. High-interest debt (above 7 to 8%) typically costs more than savings earn, so accelerating repayment on high-interest debt before building savings beyond an emergency fund usually makes financial sense. For low-interest debt (below 5%), it's generally reasonable to save and repay simultaneously. The exception is an emergency fund: having at least one to three months of essential expenses saved before aggressively paying down debt protects you from going further into debt if an emergency occurs during repayment.

What happens if I can't save 20% right now?

Save less. Start with whatever is realistic, 5%, 3%, even £50 a month, and increase it gradually. A consistent small saving habit is more valuable than an inconsistent large one. Each time your income increases, direct a portion of the increase toward savings before adjusting your spending. Over several years, incremental increases compound into a meaningful savings rate without requiring a dramatic change at any single point.

Why separating your money makes it easier to keep

•

•

2 min read

A friend checked their balance at the end of last month, and thankfully, it was more than he expected. He hadn’t deliberately saved anything, but nothing catastrophic had happened either. I can’t remember the fine details, but I know he ended up spending it.

On the surface, it looked like a spending or discipline problem. But I had a different view, and in the following paragraphs, I’ll explain my thoughts and what I believe the best fix was, and the fix is simpler than most financial advice suggests.

Why one balance makes saving hard

When your savings and your spending money are in the same account, every pound or dollar in that account looks available. The balance doesn’t distinguish between money you’re keeping and money you’re spending.

This creates a specific cognitive problem. You make spending decisions based on whether the balance looks healthy, not based on whether you’ve set anything aside. If the number looks fine, spending feels fine. If you’ve mentally noted that £400 of that balance is “for savings,” that mental note competes with every spending opportunity you encounter between now and whenever you transfer it somewhere else, and mental notes lose that competition regularly.

The money then seeps out in small, individually reasonable amounts. A round at the bar. A delivery fee that didn’t seem worth avoiding. A subscription that renewed, and you forgot to cancel. Each decision was fine in isolation. Collectively, the balance is gone before you’ve done anything intentional with it.

The psychology of separating your money

There is a well-established concept in behavioural economics called mental accounting: the tendency people have to treat money differently depending on where it is and what they’ve labelled it as. The same £50 feels very different depending on whether it arrived as a birthday gift, a work bonus, or leftover change from a supermarket run, even though all three are identical once they’re in your account.

This tendency is usually described as a bias to be corrected. But I think it can be a useful tool. When money is in a named savings account, clearly separate from your spending account, it takes on a different psychological status. It’s not spending money. It's the holiday fund, the emergency buffer, the new laptop money. Spending it requires a conscious decision to override its purpose, which creates friction that a vague mental note never does.

The separation doesn’t have to be dramatic. A second account at the same bank, a different balance in the same app, a jar on a shelf: all of these work because they create a visual and psychological boundary between money that is available and money that is not. Artificial barriers are what make behaviour change sustainable without requiring constant willpower.

Separation is not the same as locking money away

A common hesitation about separating money is the fear of losing access to it. If something comes up, will it be there? If an emergency happens, can it be reached quickly?

The answer is yes. Separating your money is not the same as locking it away. It’s not a fixed-term account, a notice period, or a commitment you can’t undo.

What separation does is add one small step between you and the money. That step shouldn’t be a barrier for genuine emergencies. It is a barrier for the kind of casual, unconsidered spending that drains balances without leaving any clear decision behind.

This is precisely the kind of friction that works in your favour. It works passively in the background every day, without you having to actively choose to protect your money each time you open your banking app.

Simple ways to separate your money today

The simplest version of this is a second account. Open one, give it a name that reflects its purpose, and move a fixed amount into it on payday and don’t touch it until the purpose it was created for arrives.

If you have more than one goal you’re working toward, the approach extends naturally. One account for the emergency fund. One for the holiday. One for the thing you’re saving toward that doesn’t have a name yet but represents a general sense of having something to show for the year. For a method to handle several goals at once, see our piece on how to save for several goals at once.

The amount you move matters less than the consistency with which you move it. A small amount transferred every payday builds the habit and the structure, and it grows over time, even if the early contributions feel negligible. For a closer look at how this plays out in practice, see our piece on how small amounts add up.

How Pouches create separation without friction

The Pouch feature on Grey takes this idea and removes most of the friction. A Pouch is a named savings space within your Grey account. You give it a name and contribute to it from your balance. It sits separately from your spending money in the same app, clearly labelled, tracking its own balance against its own purpose.

The name is more important than it might seem. “£1,200” is abstract. “Japan trip” is not. A named Pouch for a specific goal carries the same psychological weight as money in a jar labelled on the outside. You know what it’s for, and you can see how close you are. Spending it means consciously deciding to set the goal back, which is a different decision from spending money that has no label.

Because the Pouch is within your Grey account, there’s no need for multiple bank accounts or juggling between apps.

Create your first Pouch and set money aside today.

Frequently asked questions

Why is it easier to save when money is separate?

Because money sitting beside your spending money looks spendable. When your savings are in the same account as everything else, every spending decision competes with the saving intention, and the saving intention usually loses. Separation removes the competition. The savings are in a different space with a different purpose, and spending them requires overriding that purpose consciously rather than just not thinking about it.

What is mental accounting?

Mental accounting is the tendency to treat money differently based on where it is or how it arrived, even though money is functionally identical regardless of source or location. People spend windfall money more freely than earned money, treat a bonus differently from a salary, and protect money that’s been given a specific purpose more carefully than money that sits in an undifferentiated balance. When used deliberately, it’s a useful tool. By naming and separating money for a specific purpose, you activate the same psychological protection that makes people reluctant to “break into” money they’ve mentally reserved.

Does separating money mean locking it away?

No. The money remains fully accessible. Separation creates a psychological barrier, not a legal or structural one. A Pouch in your Grey account, a second current account at your bank, or a named savings pot: all of these can be accessed immediately if needed. The purpose of separation is to make casual or unintentional spending less likely, not to make genuine access impossible. For real emergencies, the money is always there.

How many savings pots should I have?

As many as you have distinct goals, within reason. One pot per clear goal is a useful starting point: one for an emergency fund, one for a specific planned purchase or trip, one for a medium-term goal like a deposit or career break. Beyond five or six active pots, contributions start to feel too small to be meaningful, and the system becomes harder to manage. Focus on the goals that matter most right now, and add new pots as old goals are reached.

How do I start separating my money?

Start on your next payday. Before spending any discretionary funds, move a fixed amount to a separate account. It doesn’t have to be large. The first move establishes the structure and the habit, and both of those matter more than the initial amount. Name the space after what you're saving for. Set a target if you have one. Then repeat the transfer every payday until the goal is reached. The system is as simple as that, and its power comes from consistency rather than size.

International freelance platforms Indians trust for steady payments

•

•

2 min read

Finding freelance work as an Indian professional has never been easier. Many platforms connect you to clients worldwide, often paying in foreign currencies. However, the reality of how difficult it is to get paid eventually comes up.

If you’ve ever watched your earnings shrink because of hidden FX markups, or waited for weeks for a payout that was supposed to take five days, you’ll know what I’m talking about. For Indian freelancers, creating a payment system that doesn’t leak money at every step is a significant challenge.

This article breaks down the international freelance platforms Indian professionals actually trust for steady, reliable payments. I’m not ranking them by popularity or features. I’m focusing on what matters most: payout reliability, transparency, and how well they actually work for freelancers based in India.

What does "steady payments” actually mean for Indian freelancers?

Before diving into platforms, let’s clarify what steady payments look like in practice.

  1. Payout speed and frequency: Some platforms pay weekly, others monthly, and a few offer instant withdrawals. The key is predictability. For example, a platform that pays every Friday is more reliable than one that pays “within 7-10 business days”, which sometimes stretches to 15.
  2. FX transparency and hidden fees: This is where most freelancers lose money. A platform might advertise "no fees,” but then apply a 3 - 4% markup on currency conversion. Steady payments mean transparent foreign exchange rates with minimal hidden costs that eat into your earnings.
  3. Escrow and dispute protection: Platforms with escrow systems hold client payments until work is delivered and approved. This protects you from clients who ghost after you’ve completed the job. Dispute resolution processes are also important, especially when dealing with international clients across different time zones.
  4. Regulatory and compliance considerations: Indian freelancers earning foreign income must comply with FEMA regulations and file taxes properly. Platforms that provide clear invoices, payment records, and integrate well with Indian tax systems make compliance easier, not harder.

Also read: Best freelance platforms to earn US dollars in Indonesia

Trusted international freelance platforms

Let’s examine platforms grouped by what they excel at for Indian freelancers.

Platforms with escrow-based payment protection

  1. Upwork: Upwork remains one of the most trusted platforms for Indian freelancers, primarily due to its escrow system. The escrow system protects you from non-payment. Once a client funds a project, you know the money exists. Weekly billing cycles mean regular income if you’re on an hourly contract.
  2. Fiverr: Fiverr’s escrow model is simple: clients pay upfront, and funds are released to you after order completion. For Indian freelancers offering fixed-price services, this creates predictable cash flow. Once the order is marked complete and the buyer doesn’t request revisions within three days, payment is guaranteed. A small downside, however, is that the payment cycle is 14 days.
  3. Toptal: Toptal is an exclusive network for top freelancers in software development, design, and finance. It operates on an escrow basis, with clients funding work upfront and payments released on a predictable schedule. Toptal handles invoicing, contracts, and payment collection. Payments are reliable, and disputes are rare because clients are vetted as thoroughly as freelancers.

Also read: Freelance platforms with high payout rates in Egypt

LDMAG1

Platforms known for fast, predictable payouts

  1. Freelancer.com: Freelancer.com offers milestone-based escrow and weekly payouts for hourly projects. It’s not as polished as Upwork, but Indian freelancers appreciate the speed of payouts and flexibility. You can request withdrawals as frequently as you like (though fees apply per transaction).
  2. Guru: Guru operates with SafePay, an escrow system that releases funds after work approval. Payouts are processed quickly, and the platform supports multiple withdrawal methods for Indian freelancers. Guru’s relatively lower service fees (5 - 9%) make it attractive for many freelancers. Generally, payments are processed within 24 to 48 hours of receiving withdrawal requests.

Also read: Top platforms to receive freelance payments worldwide

What to consider when choosing the right freelance platform

Your ideal platform depends on where you are in your freelance journey.

Beginners

Start with Upwork or Fiverr. Both offer escrow protection, steady workflows, and built-in client pipelines. Yes, the fees are high, but the security and volume of available work justify the cost while you’re building your portfolio and reputation.

Full-time freelancers

Consider diversifying your work across Upwork, Toptal and direct clients found through LinkedIn. Use Grey to receive payments from direct clients.

Also read: Safe ways to receive international payments in India

Made a decision yet?

Steady payments don’t necessarily come from platform loyalty or luck. They come from understanding how money moves, choosing platforms that align with your work style, and setting up a payment stack that doesn’t leak income at every step.

For you, that could mean using escrow-based platforms for security, understanding FX markups, and pairing marketplace work with tools that give you better control over your earnings. The platforms you choose and how you get paid matter as much as the work itself.

Create your free Grey account today or download the app and start receiving international payments with better FX rates, faster payouts, and full transparency.

‍

Planning a location-flexible career from the UK

•

•

2 min read

A location-flexible role offers the freedom to choose where you work, a better work-life balance, and removes the constraints of a daily commute. It also bypasses the fixed, traditional office environment, which can feel like a cage at times. And even though it sounds like a promising idea, delving into remote work without taking the right steps can land you in trouble. So whether you want to work in various locations across the UK or embrace a full-time global digital nomad lifestyle, you must be adequately prepared. This is how to plan a location-flexible career from the UK to ensure a smooth transition.

Also read: What remote workers should plan before relocating

Get the right skills

To set yourself up for a successful location-flexible career, you need to get location-flexible skills. This means you should be able to use your skills remotely and that they should have cross-border relevance. Roles in software development, data, design, content, marketing, consulting, customer success, product management, and research are remote-friendly.

If your current role isn’t remote-friendly, look for ways to make it more remote or switch roles. This could mean looking into freelancing or contract-based jobs. Having a niche improves your odds for success and better pay. Build a portfolio that showcases your capabilities and keep honing your skills.

Also read: Paying abroad from the UK: a simple guide for first-time traveller

Review tax regulations and legal status

Before hopping on a flight to a new work destination, you must ensure that you have the right paperwork to work in that country. A UK passport might give you access to many countries, but confirm this with the right authorities. If you need to apply for a visa, prioritise countries with digital nomad visas.

Another overlooked aspect of a location-flexible career is tax planning. If you are a UK resident, your tax obligations depend on residency status, days spent in the UK, and where your income is sourced. Working abroad doesn’t always mean you don’t have to pay taxes in the UK anymore. Review the Statutory Residence Test, double taxation agreements, and how they apply in your situation.

Set up a travel-friendly payment system

A location-flexible career requires a location-flexible payment system that works across borders. Traditional UK bank accounts are often not optimised for international payments. Many UK remote workers now rely on multi-currency accounts to receive payments in USD, EUR, and GBP. They can choose to keep their money in foreign currencies and convert whenever they want without excessive fees. You can withdraw to local bank accounts at competitive rates wherever you go.

LDMAG1

Have a financial plan

In addition to setting up a reliable payment system, you should also plan your finances based on your income. Budget for your monthly expenses and set aside some money for savings and emergencies. Use separate accounts for income and daily spending. A clear financial structure reduces stress and gives you confidence to move freely without the fear of getting stranded. Don’t forget to always track your spending.

Also read: How Grey differs from a UK bank

Research your destination

Planning a location-flexible career means researching destinations in advance. Your destination largely determines your experience, positive or negative. Consider the living costs, security, time zone overlap, digital infrastructure, community, and quality internet coverage.

Have a work structure

Flexibility can easily breed indiscipline, and if you don’t check it early enough, you can end up with burnout and lower productivity. If you must be an excellent remote worker, you must have a strict work routine that ensures work doesn’t eat into social life, and your social life doesn’t affect your work. Have defined working hours, communication boundaries, reliable internet plans, and systems for productivity regardless of location.

Grey: Location-flexible payment solution for location-flexible workers

If you are tired of the rigid traditional work structure holding you back in the UK, then transitioning into a location-flexible career is a step in the right direction. Planning adequately for this transition ensures you have a great experience. The right cross-border payment solutions help you manage receiving payments and withdrawing funds to local bank accounts wherever you go.

Grey offers USD, EUR, and GBP accounts that let you receive payments easily and withdraw funds to various local currencies at competitive rates. You also get a virtual USD debit card to further simplify your payments while travelling. If you are freelancing on global platforms, you can add your Grey account details to withdraw your earnings without delays and cut-throat platform fees.

Get started on Grey today or download the app for a reliable location-flexible payment solution.

‍

How to earn yield on USDC: Best options in 2026

•

•

2 min read

USDC is a stablecoin designed to maintain a value close to one US dollar, making it an option for people who want to hold digital dollars without the usual price swings associated with cryptocurrencies like Bitcoin. However, holding USDC in a wallet does not automatically generate interest. To earn a return, you need to invest your holdings in a programme or platform that pays a yield.

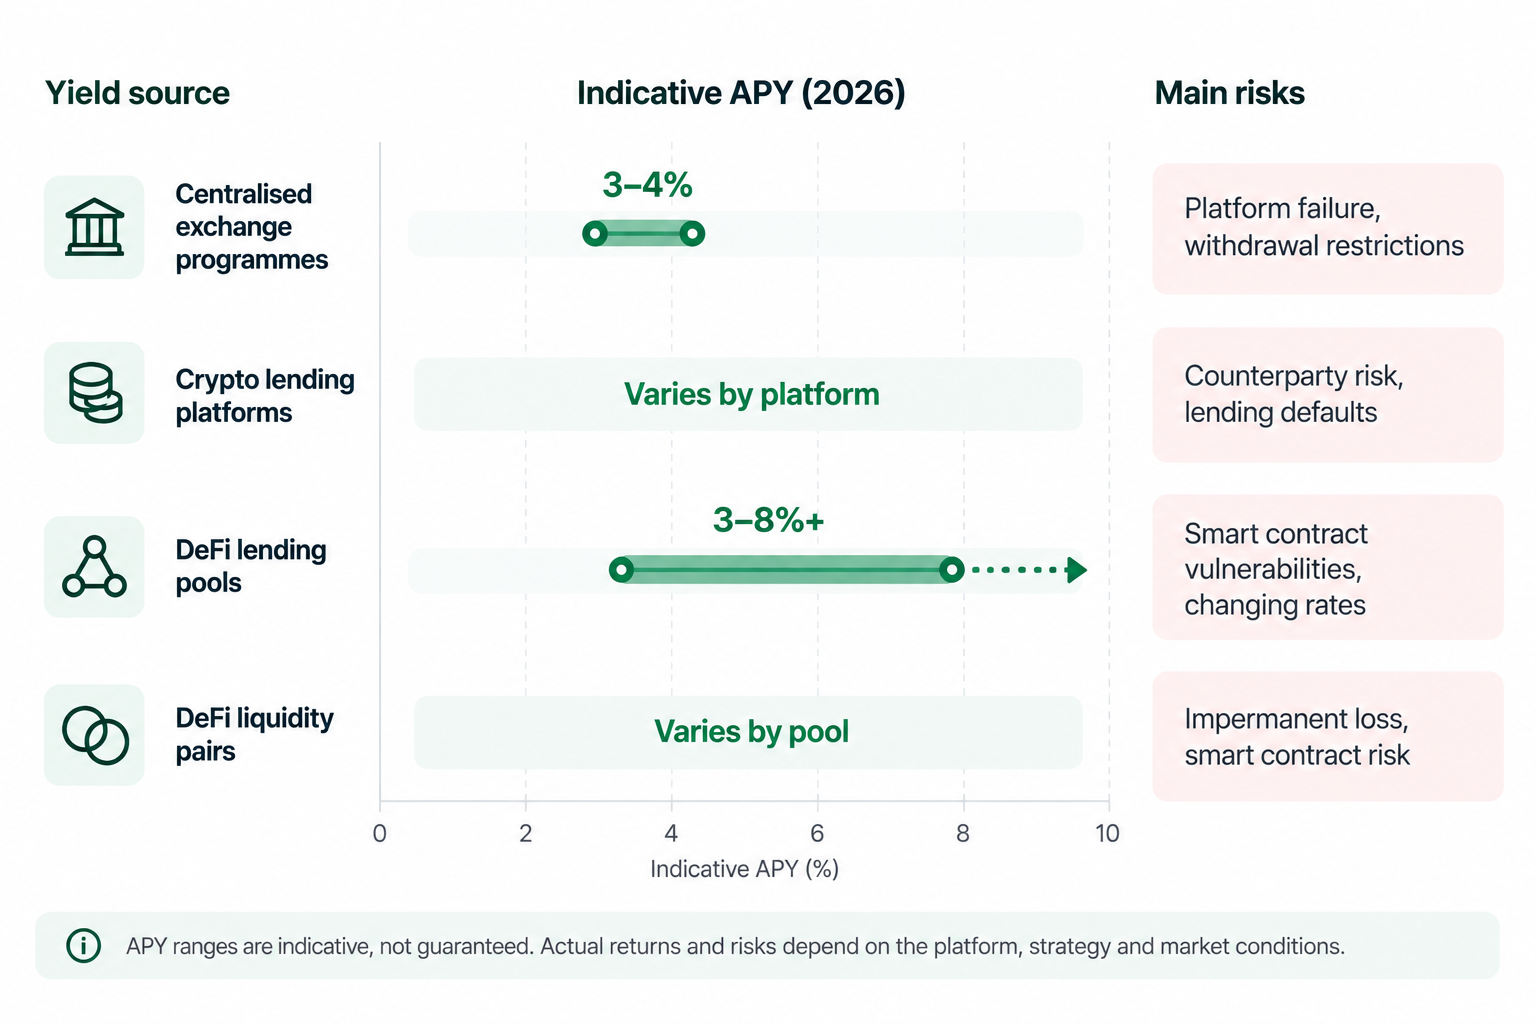
USDC itself pays no interest. Yield comes from lending it out through a centralised exchange programme, a crypto lending platform, or a DeFi protocol such as a lending pool or liquidity pair. Rates ranged from about 2 to 8% APY in 2026, depending on the platform, strategy and market conditions.

Each option comes with different levels of risk, access requirements and withdrawal conditions. Before choosing where to earn yield, understand how returns are generated, whether your funds are protected, and what could happen if a platform fails or a smart contract is exploited.

Does USDC pay interest on its own?

No, holding USDC in a crypto wallet does not earn interest by itself. USDC is a stablecoin designed to maintain a value close to one US dollar, but simply owning it does not generate additional income. Whether it sits in a personal wallet or an exchange account, your balance remains unchanged unless you receive additional USDC through another transaction or service.

To earn yield, you need to use a separate financial product built on top of USDC. These products generate returns through activities such as lending your stablecoins to borrowers, supplying liquidity to decentralised finance (DeFi) protocols, or participating in yield programmes offered by cryptocurrency exchanges.

Each option works differently and carries its own risks. A lending platform may pay interest from borrower repayments, while a DeFi protocol may distribute fees or lending revenue to participants. Centralised exchanges may offer promotional rates or rewards under specific conditions.

Before depositing USDC into any yield product, understand how returns are generated, what fees apply, and whether you can withdraw your funds when needed. Yield is never guaranteed.

Also read: How USDC compares with USDT

Centralised exchange and lending platforms

Centralised exchanges and crypto lending platforms allow you to earn yield by depositing your USDC into programmes that generate returns. Exchange earn programmes may lend your USDC to borrowers or use other permitted strategies to generate revenue, sharing a portion of the earnings with you.

Crypto lending platforms work similarly, connecting you with borrowers and paying interest on the funds you supply.
The annual percentage yield (APY) you receive depends on the platform, market demand, lending activity and programme conditions. Rates can change, and promotional offers may have limits or eligibility requirements.

Custody is another important consideration. When you deposit USDC into a centralised platform, the platform typically controls your assets rather than you holding the private keys directly. It may lend, transfer or otherwise use your deposited coins according to its terms.

This exposes you to counterparty risk. If the platform becomes insolvent, freezes withdrawals or suffers a hack, you may struggle to access your funds or lose them entirely. Before depositing your USDC, review the withdrawal terms, fees, security measures and how the platform uses your assets.

DeFi options: lending pools and liquidity pairs

Decentralised finance (DeFi) offers another way to earn yield on USDC without relying on a traditional financial intermediary. Two common options are lending pools and liquidity pairs, each generating returns in different ways.

With a lending pool, you deposit USDC into a protocol where borrowers can access the funds and pay interest. A portion of that interest is distributed to depositors as yield. Your returns depend on borrowing demand, utilisation rates and the protocol’s rules.

With a liquidity pair, you deposit USDC alongside another cryptocurrency into a trading pool. Traders use this pool to swap assets, and liquidity providers may earn a share of trading fees. However, the value of the two deposited assets can change relative to each other, creating impermanent loss.

Both strategies carry risks. Smart contract bugs can expose deposited funds to theft or loss. Impermanent loss can reduce returns compared with simply holding the assets. Depegging occurs when USDC falls below its intended one-dollar value, reducing the value of your holdings even when the yield remains positive.

How the main risks compare

When you earn yield on USDC, your biggest risks depend on where you deposit your funds and how the platform generates returns. Counterparty risk, smart contract risk and depeg risk can all affect how much you earn and whether you recover your initial deposit.

Counterparty risk arises when you trust a centralised exchange or lending platform with your USDC. If the provider fails or freezes withdrawals, you may lose access to your funds. Smart contract risk affects you when a vulnerability in a DeFi protocol allows your deposited funds to be stolen or lost. Depeg risk means your USDC falls below its intended $1 value, reducing the value of your holdings.

Chart comparing USDC yield options by risk and return.

There is no universal ranking because your exposure depends on the product you choose. However, higher advertised APY usually means higher risk. Before depositing, consider how returns are generated, who controls your funds and what could go wrong.

Your choice of blockchain also matters. Learn how USDC on Solana compares with Ethereum when considering transaction fees, network activity and the platforms available to you.

USDC yield vs a bank savings account

USDC yield can offer a potentially higher return than a regular savings account, but you give up an important protection: USDC does not have government-backed deposit insurance. Your returns depend on the platform and strategy you use, and higher yields often come with greater risk. A bank savings account may offer less, but eligible deposits have protection and more predictable access to your money.

Before choosing USDC for yield, consider whether you can afford the risks, including platform failure, smart contract vulnerabilities and changes in USDC’s value. It is generally better to keep emergency funds in an insured bank account rather than expose money you need urgently to crypto-related risks.

USDC can also make moving money across borders easier. For example, if you need to send money from the US to Nigeria, you can use a platform that supports USDC transfers and local withdrawals. With Grey, you can send, receive and spend USDC, then convert your balance and withdraw funds to a supported local bank account.

The right choice depends on your priorities: bank deposits for protection, USDC for global access and potential yield.

Frequently asked questions about how to earn yield on USDC

1. Is earning yield on USDC safe?

Earning yield on USDC carries risks, including platform failure, smart contract vulnerabilities and loss of funds. Although USDC is designed to maintain a one-dollar value, your investment is not guaranteed. Review the platform’s security, withdrawal terms and yield strategy before depositing funds, and never invest money you cannot afford to lose.

2. What is a typical USDC APY in 2026?

USDC yield varies by platform, market conditions and strategy. In 2026, some centralised reward programmes offer around 3–4% APY, while DeFi lending may offer approximately 3–8% or more. These are indicative ranges, not guaranteed rates. Check current offers, fees and risks before choosing a platform.

3. Do you pay tax on USDC yield?

Yes, USDC yield may be taxable, depending on your country’s tax laws and how you earn it. In the United States, rewards are generally reportable as income. Keep records of payments, dates and amounts, and consult a qualified tax professional to understand your reporting obligations.

4. Can you lose your USDC principal earning yield?

Yes, you can lose some or all of your USDC principal. Platform insolvency, lending defaults, smart contract exploits and liquidity problems can prevent withdrawals or cause losses. USDC can also trade below one dollar. Assess the risks carefully, diversify where appropriate and avoid committing essential savings.

5. What is the difference between USDC yield and USDC staking?

USDC yield usually comes from lending, reward programmes or providing liquidity through a platform or DeFi protocol. Staking typically involves locking cryptocurrency to support a proof-of-stake blockchain. USDC does not use proof-of-stake itself, so products marketed as USDC staking generally involve a different yield-generating mechanism.

6. How do you convert USDC yield into cash you can spend?

First, withdraw your USDC and earn rewards to a supported exchange or financial platform. Convert the balance into your preferred currency, then withdraw it to an eligible bank account or payment method. With Grey, you can send, receive and spend USDC, subject to supported services, currencies and applicable fees.

While USDC yield offers the potential for higher returns, a bank savings account provides greater protection for eligible deposits. For international transactions, Grey gives you a practical way to send, receive and spend USDC, with access to supported currencies for your everyday financial needs.

Arrow (up)

Back to top

