If you are a Nigerian earning in dollars from freelance clients, a remote job, an international consultancy, or a business with customers abroad, consider opening a dollar account. Receiving USD payments into your local account means you are forced to convert every payment to naira the moment it arrives, often at marked-up rates worse than you would get elsewhere.
A Nigerian dollar account holds US dollars without automatically converting them to naira. You can open a bank domiciliary account at banks like GTBank or UBA, or a virtual USD account through a fintech, which gives you real US account details to receive payments and usually opens faster with lower fees.
This guide explains how to open a dollar account in Nigeria and compares domiciliary accounts with virtual accounts, so you can decide what works best for you.
What is a Nigerian dollar account?
A Nigerian dollar account lets you receive and hold USD instead of automatically converting it to naira. Most often, this term refers to a domiciliary account.
A domiciliary (or dom) account is a foreign currency account offered by Nigerian commercial banks (UBA, GTBank, First Bank, Standard Chartered, and others) and regulated by the Central Bank of Nigeria. This account lets you hold a foreign currency account with a Nigerian bank.
Both fintechs with virtual USD accounts and traditional banks with domiciliary accounts serve the same purpose. They both let you hold dollars as dollars without converting to naira. You only convert when you choose.
Domiciliary account vs virtual USD account
At a glance, here is how a domiciliary account is different from a virtual USD account.
| Factor |
Bank domiciliary account |
Virtual USD account |
| Where it is held |
Nigerian commercial bank |
Issued via a US partner bank, accessed through a fintech app |
| Documents required |
Usually requires more documentations, including an application form, a valid ID, proof of address, BVN, NIN, recent photographs, and sometimes, proof of the source of funds and references. |
Usually simpler online verification requiring a valid ID, proof of address, and a selfie. |
Opening balance
|
Often requires a minimum opening deposit, amount varies. |
Usually no minimum opening balance |
Account opening speed
|
Can take days, sometimes requiring an in-branch visit |
Often same-day, fully online |
| Receiving USD |
Through international (SWIFT) wire with correspondent bank deductions |
Via ACH (like domestic transfer), no correspondent bank involved. |
| Fees |
Account maintenance, correspondent bank, and international wire fees |
Often lower or no monthly fee, transaction-based pricing instead |
| Best for |
Large or occasional foreign transfers |
Freelancers and remote workers receiving regular USD payments |
The most important difference between virtual USD accounts is how you receive your dollars.
A domiciliary account usually receives international payments through SWIFT. The payment may pass through one or more intermediary banks before reaching your Nigerian bank. These banks deduct fees along the way.
A virtual USD account with a US routing number can receive ACH payments directly through the US banking system, like a local transaction. This avoids the extra cost of intermediary banks.
How to open a bank domiciliary account
Opening a domiciliary account might have some differences in requirements across banks and depend on the account tier. But here is how to open a dollar account in Nigeria generally.
Step 1: Choose a bank
Compare domiciliary accounts from banks such as GTBank, UBA, First Bank, Zenith and Standard Chartered. Check their fees, minimum balances and requirements before choosing one.
Step 2: Prepare your documents
Typically required: a valid means of identification (National ID, international passport, or driver's licence), your Bank Verification Number (BVN), proof of address (a recent utility bill or tenancy agreement), and passport photographs. Some banks request additional documentation depending on the account tier or your source of income.
Step 3: Visit a branch or apply through the bank's digital platform
Some banks now allow you to open a domiciliary account online, especially if you are an existing customer. Others may still require an in-person visit, especially if you are a new customer or requesting a higher-tier account.
Step 4: Make your opening deposit
Many domiciliary accounts require a minimum opening balance. This usually depends on the bank and account tier. Confirm the current requirement directly with your chosen bank.
Step 5: Receive your account details
Once your application is approved, you will receive your domiciliary account number and the bank's SWIFT code, which is what senders abroad will need to wire USD to your account.
How to open a virtual USD account in Nigeria
Different virtual USD account providers have slightly different sign-up processes. Here’s a general process to give you an idea of what to expect.
Step 1: Sign up with a fintech provider offering virtual USD accounts
Download the app or visit the provider's website and create an account with your basic details.
Step 2: Complete identity verification
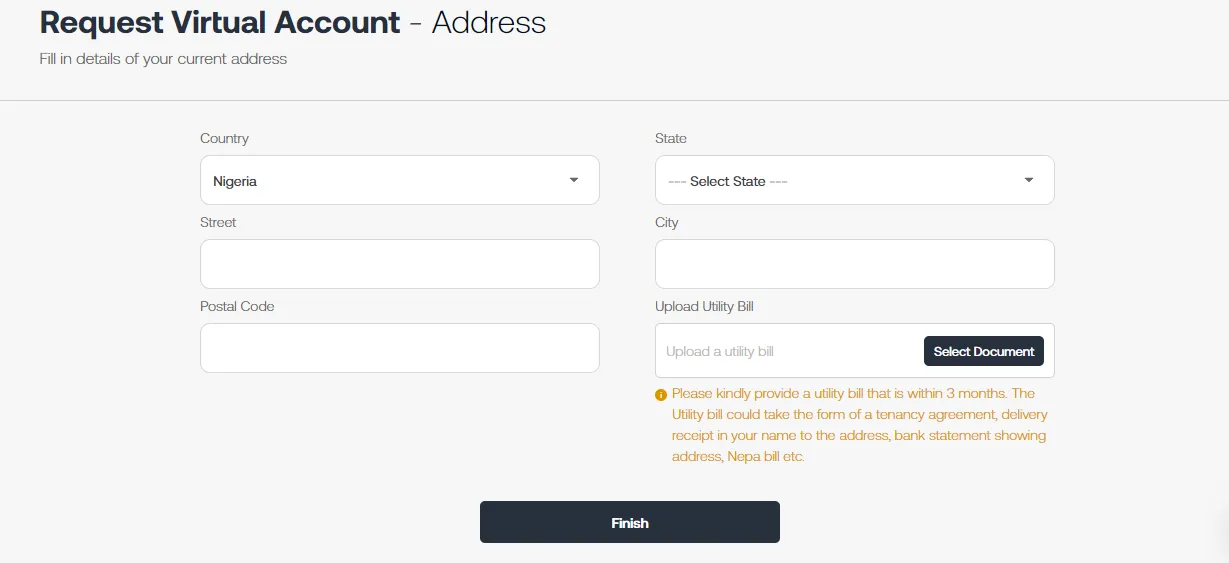
Upload a valid government-issued ID (typically your BVN-linked National ID, international passport, or driver's licence) and complete the standard identification verification process.
Step 3: Open your USD account
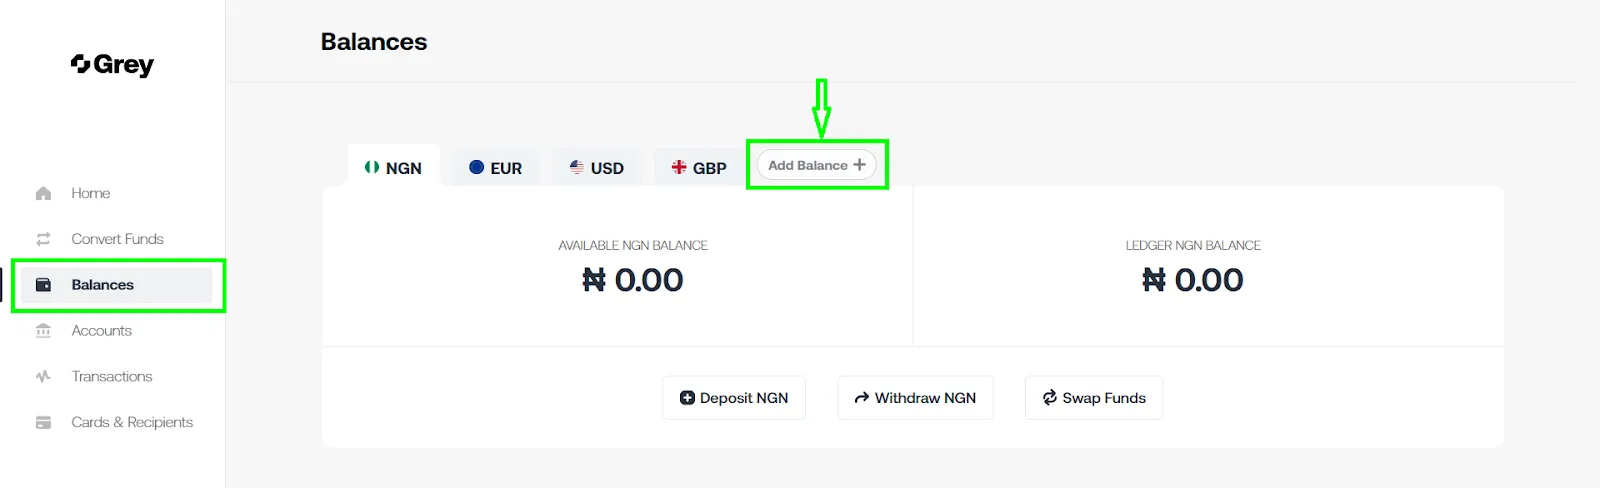
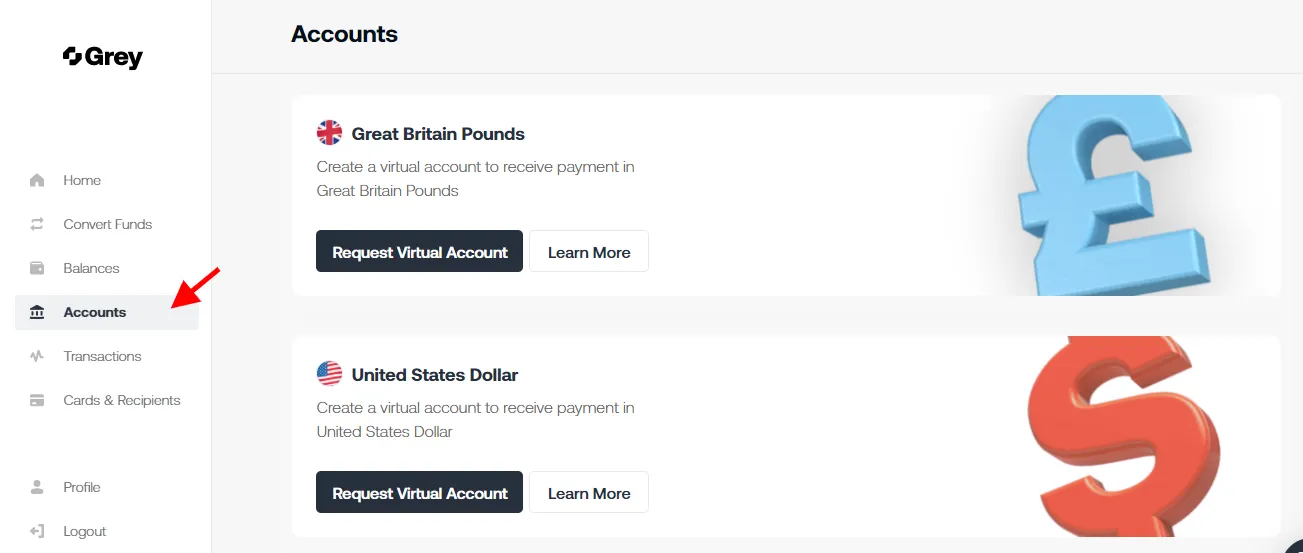
Once your account is verified, open a USD account in the app and receive your account details. Grey, for example, provides a USD account through a US partner bank and gives you a US routing number and account number rather than a Nigerian domiciliary account number.
Step 4: Share your account details with payers
Share your US routing number and account number with your clients and employers or add to the platforms. This way, you can get paid via ACH.
Step 5: Receive, hold, or convert
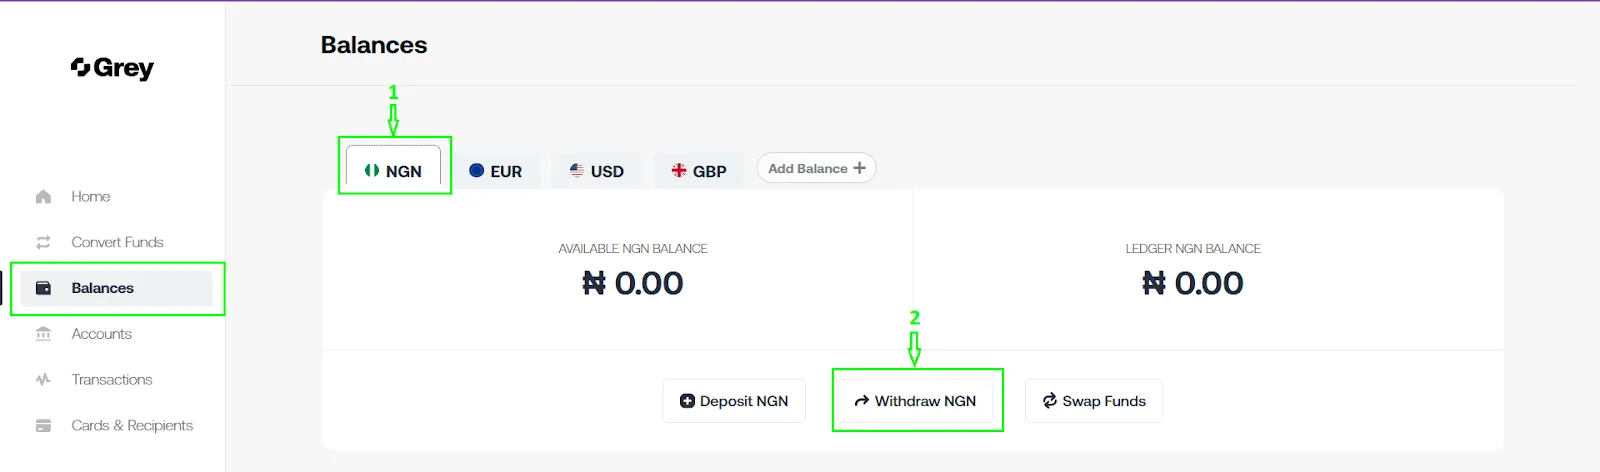
When the USD lands in your account, you can keep the money in USD or convert to naira and withdraw whenever you choose. The rate is usually disclosed before you confirm the transaction. Platforms like Grey also provide virtual cards linked with your USD account, so you can spend directly in USD.
See our guide on the best ways to receive international payments in Nigeria.
Fees, limits and receiving USD
Receiving USD through a domiciliary account can involve several charges. These may include the sender's bank fee, correspondent bank charges and fees from your Nigerian bank. The amount you receive can therefore be lower than the amount originally sent. You might also be charged a maintenance fee, which varies by bank.
A virtual USD account in Nigeria that receives payments through ACH avoids the correspondent banks used by SWIFT transfers. Providers may still charge a fee for receiving or processing payments, so check the fee before receiving a large payment. For example, Grey charges 0.8% for USD deposits (minimum: $2, maximum: $10). This is shown clearly before any transaction. So, you can tell how much you will be getting at the end, unlike SWIFT transfers that come with undisclosed layered fees.
Here is how to receive US dollars with Grey.
Converting USD to naira
Both options require you to consider the exchange rate when converting your dollars to naira. With a bank, the rate you receive depends on the bank's rate at the time of conversion.
On the other hand, fintech usually offers a rate close to the mid-market rate and charges a separate conversion fee, which is also disclosed before initiating the conversion. With Grey, the conversion fee is 1%, capped at $6.
Whether it is a dom account or a virtual USD account, monitoring the exchange allows you to decide whether to convert now or wait, especially when there is no urgent need.
For guidance specifically on receiving USD from the US into a domiciliary account, see our detailed guide on sending USD from the USA to a Nigerian domiciliary account.
Transaction limits
The Central Bank of Nigeria regulates traditional banks, and each bank sets its own policies governing how domiciliary accounts may be used. This includes setting limits on withdrawals per time.
Virtual USD account limits are set by the individual fintech provider rather than the CBN. However, standard anti-money laundering practices may still impose limits depending on the account’s verification tier.
Grey offers USD, EUR, and GBP accounts, allowing you to receive and manage these currencies in one place without monthly maintenance fees. You have full control over when you want to convert, and the fees are disclosed beforehand.
Open a USD account with Grey and receive dollars with real US account details, and avoid international wire fees.
Frequently asked questions about Nigerian dollar accounts
What documents do I need?
For a bank domiciliary account, you typically need a valid means of identification, your BVN, proof of address, and passport photographs, with some banks requesting additional documentation depending on the account tier. For a virtual USD account like Grey, requirements are generally lighter: a valid government-issued ID linked to your BVN and standard identity verification completed within the app, without the need for a physical branch visit.
What is the minimum balance?
Domiciliary accounts often require a minimum opening deposit, with the specific amount varying considerably by bank and account tier, so confirm directly with your chosen bank before applying. Virtual USD accounts like Grey typically have no minimum opening balance requirement, making them more accessible for those starting with smaller or irregular USD income.
Can I receive USD without a bank domiciliary account?
Yes. A virtual USD account, provided through a fintech platform's US banking partner, gives you real US routing and account number details for receiving USD via ACH, entirely separate from a Nigerian bank's domiciliary product. This is often faster to set up and avoids the correspondent bank deductions that can reduce SWIFT wire transfers into a domiciliary account.
How long does it take?
Opening a bank domiciliary account can take anywhere from the same day to several days, depending on the bank and whether you need an in-branch visit. A virtual USD account through a fintech provider is typically faster, often completed the same day online, since the entire process, from sign-up to verification to receiving your account details, happens within the app without requiring a physical visit.